A private-client guide to establishing a Florida homestead after Dallas, separating Save Our Homes portability from Texas benefits, and coordinating deed ownership with tax eligibility and estate planning.
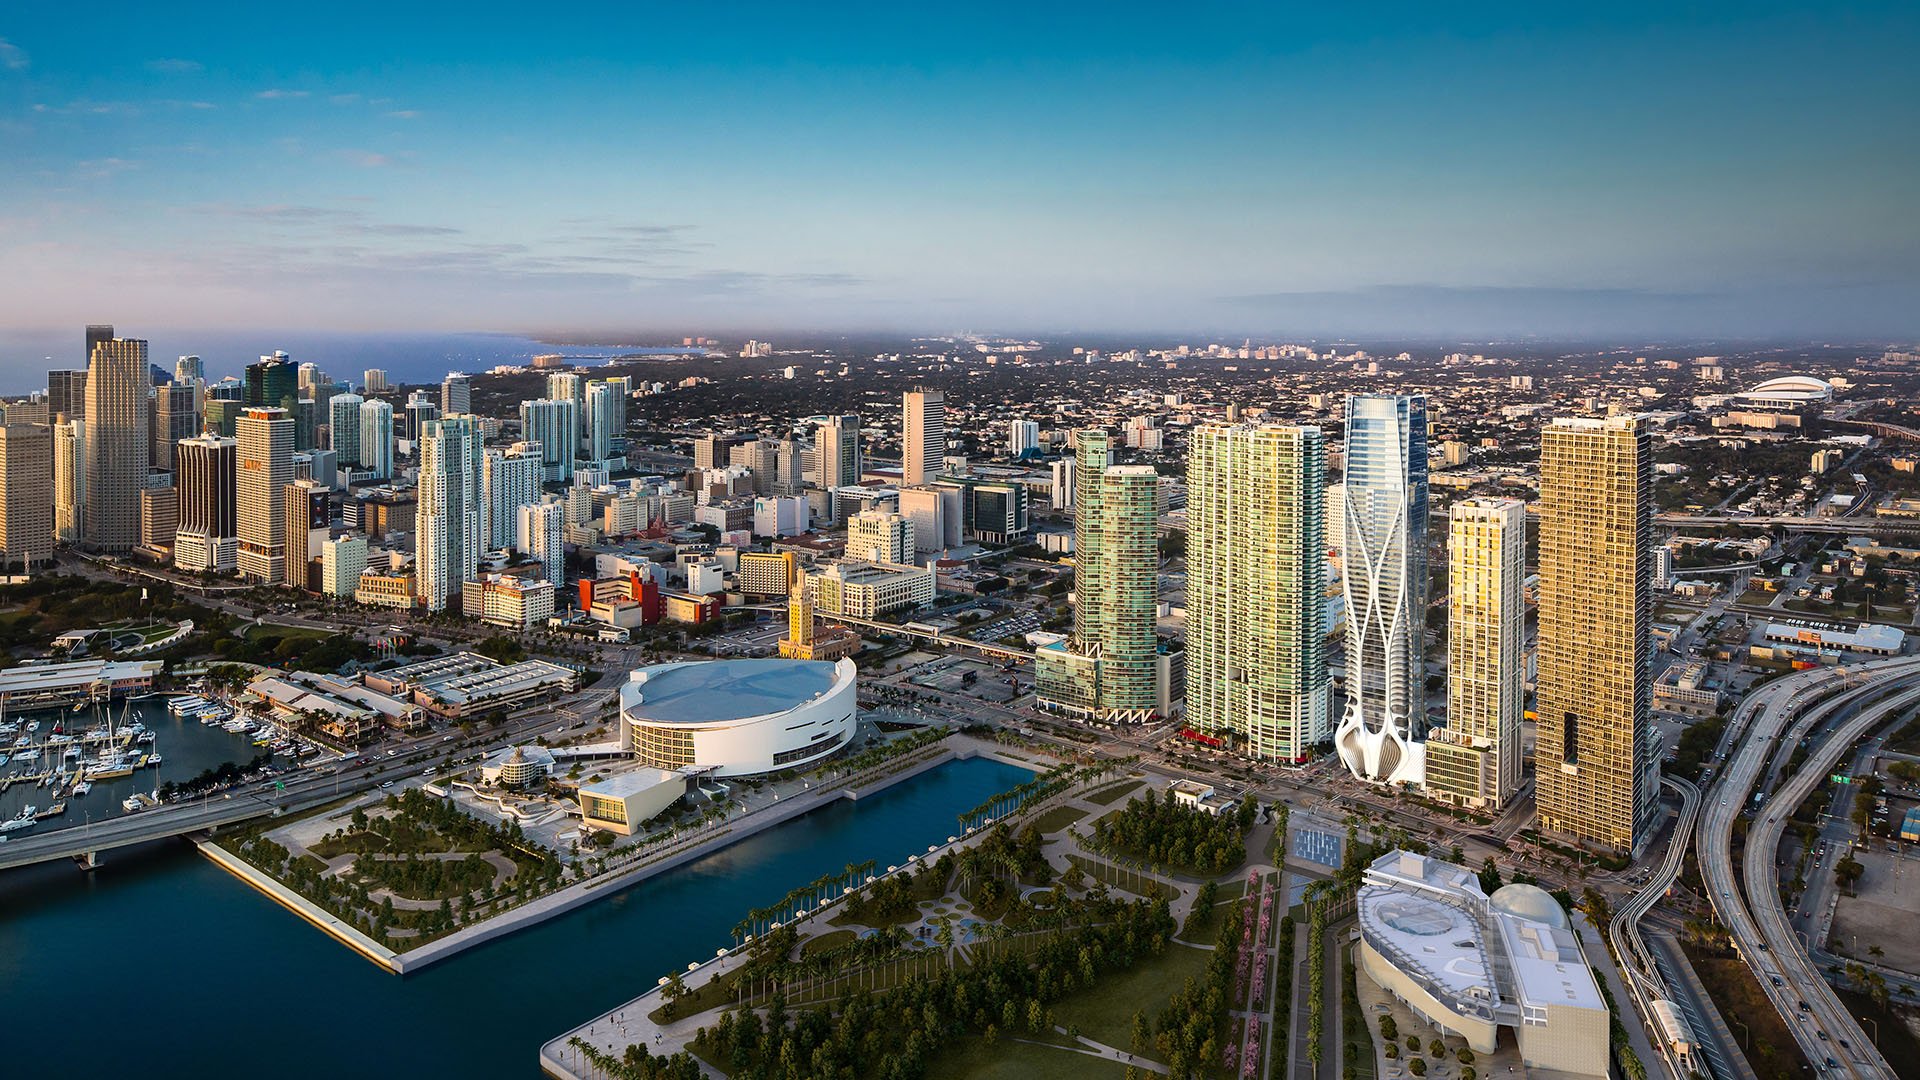
Moving from Dallas to Downtown Miami involves more than choosing a residence. For a private client, the acquisition should align three decisions: when Florida becomes the permanent home, which property-tax benefits are available, and how ownership is recorded on the deed. Those decisions belong in the purchase brief, not in a corrective conversation after closing.
A Dallas homestead does not create Florida Save Our Homes portability. Texas benefits do not travel with the household. Unless a qualifying prior Florida homestead exists, the starting point is a new Florida homestead application-not a transfer of accumulated tax advantages.
For a buyer considering Aston Martin Residences Downtown Miami, the practical question extends beyond whether the apartment suits the household. Ownership, actual permanent residence and the proposed title structure must align for the intended tax year.
The homestead exemption reduces taxable value, not the tax bill dollar-for-dollar. Because annual inflation adjustments affect the benefit, planning should use the applicable tax year's exemption figures rather than treat the full exemption as a permanently fixed $50,000 ceiling.
Save Our Homes serves a different purpose: it limits annual increases in an established homestead's assessed value. It does not freeze market value. A residence can appreciate while its assessed value follows a different path.
Portability concerns the eligible difference between a former Florida homestead's just, or market, value and its assessed value. The exemption itself does not transfer when the owner moves. A qualifying assessment difference may transfer, subject to the applicable rules.
This distinction matters when reviewing carrying costs at One Thousand Museum Downtown Miami. A seller's capped assessment is not a reliable forecast for the purchaser: a purchase can trigger reassessment under change-of-ownership rules. Ask advisers to model the buyer's position rather than carry forward the seller's tax bill.
Florida homestead eligibility generally requires ownership and use of the property as the permanent residence of the owner or a legally or naturally dependent person. Ownership and permanent residence generally must be established by January 1 of the tax year claimed.
The general application deadline is March 1. The property appraiser in the county where the home is located handles filing. For a Downtown Miami purchase, that means coordinating the application with Miami-Dade's property appraiser.
Create a residence file before closing. Evidence can include a Florida driver's license, voter registration, vehicle registration and a declaration of domicile. The objective is a consistent record supporting the claimed permanent residence, not a collection of disconnected documents.
For a household comparing Downtown with Brickell, apply the same discipline to both locations. Identify the intended permanent home, review remaining Dallas residency indicators with advisers, and align documentation with the actual move. Neither a signed contract nor a preferred mailing address substitutes for satisfying ownership and permanent-residence requirements.
A direct Dallas-to-Miami move should not include a portability allowance in the budget merely because the Dallas property enjoyed homestead treatment. The relevant question is whether the applicant had a qualifying Florida homestead exemption in one of the three immediately preceding tax years.
If that history exists, investigate it separately. Portability can transfer an eligible assessment difference of up to $500,000. That is a maximum assessment benefit-not a $500,000 tax credit, an exemption amount or a transferable tax bill. Eligibility does not mean every applicant receives the maximum.
Portability is not automatic. Eligible applicants generally submit Form DR-501T with the new homestead application, Form DR-501. Ask advisers to confirm the prior Florida qualification, the relevant years and the available assessment difference before including a portability benefit in an ownership-cost projection.
When evaluating Casa Bella by B&B Italia Downtown Miami, keep that review separate from the property's appeal. Portability depends on the applicant's qualifying Florida history, not the residence's branding or purchase price alone.
Title is not merely an administrative field on closing documents. Tax homestead, constitutional creditor protection, and spousal or inheritance rights are related but distinct. Florida counsel should coordinate the deed with the estate plan rather than assume one ownership choice resolves every issue.
Individual and co-owned title.
The homestead-exemption statute recognizes ownership by the entireties, jointly or in common. Exemption apportionment may depend on qualifying owners' interests. Co-owners occupying separate residential units on jointly owned property can face allocation based on their ownership interests and qualification. Co-ownership is not a shortcut to a full exemption for everyone.
Tenancy by the entireties.
For married owners, this structure offers survivorship and potential protection from an individual spouse's creditors, provided Florida's ownership requirements are satisfied. Those advantages require legal review; they are not a blanket promise against every creditor claim.
Trust ownership.
Trust-held property may qualify through the applicant's beneficial ownership. The property appraiser may require the trust agreement to assess eligibility. Confirm Miami-Dade's submission requirements rather than assume another county's practices apply. Review tax eligibility, creditor protection and inheritance restrictions separately. Probate avoidance does not establish that every homestead benefit survives.
LLC ownership.
An entity should not be the default for a permanent residence. LLC ownership generally jeopardizes homestead eligibility, and transferring an already-homesteaded residence into an entity can affect both the exemption and assessment protections. Resolve that tension before signing or later changing the deed.
For a household evaluating Waldorf Astoria Residences Downtown Miami, the checklist should be as disciplined as the property selection. A residence's identity does not replace an applicant-specific eligibility review.
Before closing, have the legal and tax advisers confirm these items:
Residence timeline: Identify when ownership and permanent residence will be established relative to January 1.
Documentation: Align Florida residency evidence and resolve inconsistent Dallas indicators.
Tax projection: Account for possible reassessment rather than relying on the seller's capped assessment.
Portability review: Check qualifying prior Florida homestead history before including any benefit.
Ownership approval: Coordinate the deed, marital circumstances and estate plan before execution.
Filing responsibility: Assign responsibility for preparing the application and any portability form, and for meeting the general March 1 deadline.
The objective is a coherent ownership plan, not simply an exemption application. This checklist is general planning guidance, not individualized legal or tax advice; eligibility and deed consequences require review of the household's circumstances.
For a discreet conversation about selecting your Downtown Miami residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Save Our Homes portability applies between qualifying Florida homesteads, not to Texas homestead benefits.
Ownership and permanent residence generally must be established by January 1 of the tax year claimed. The residence may qualify through the owner or a legally or naturally dependent person.
The general deadline is March 1. File with the property appraiser in the county where the residence is located.
Evidence can include a Florida driver's license, voter registration, vehicle registration and a declaration of domicile. Documentation should consistently support the claimed permanent residence.
No. The exemption reduces taxable value, and annual inflation adjustments mean the full benefit should not be described as a fixed $50,000 ceiling.
Not reliably. A purchase can trigger reassessment, so the seller's capped assessment may not reflect the buyer's future assessment.
It is the maximum portable assessment difference between a qualifying former Florida homestead's just value and assessed value. It is not a $500,000 tax credit or a guaranteed benefit.
Eligible applicants generally submit Form DR-501T with the new homestead application, Form DR-501. Portability generally requires a qualifying Florida homestead exemption in one of the three immediately preceding tax years.
It may qualify through the applicant's beneficial ownership, and the property appraiser may require trust documents. Tax eligibility, creditor protection and inheritance restrictions require separate review.
LLC ownership generally jeopardizes homestead eligibility, and transferring an existing homestead into an entity can affect exemption and assessment protections. Review the proposed deed with Florida counsel before proceeding.