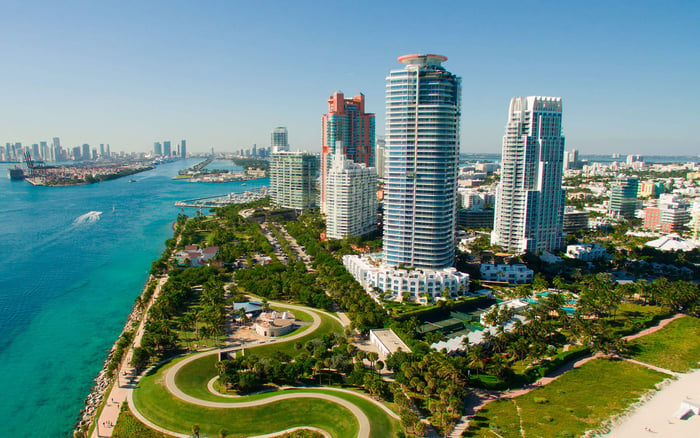
Before bidding on a South Florida luxury home, establish the sale type, investigate title and condition, confirm payment terms, and set a ceiling that accounts for unresolved risks.
A South Florida luxury home at auction should be evaluated as a legal acquisition first and a residence second. Architecture, setting, and an attractive opening bid do not establish which interests will transfer, which obligations may remain, or when the property can be occupied. The decisive work happens before the auction.
Begin with a written acquisition brief: identify the sale type, reconcile the property description, obtain professional title review, investigate condition, and confirm the payment timetable. If a material question remains unanswered, the appropriate response may be a lower ceiling or no bid at all. An auction discount is meaningful only when weighed against the obligations and uncertainty that accompany it.
Mortgage foreclosure, tax-deed sale, association-lien foreclosure, and county-owned surplus sale are not interchangeable. Establish which process applies before interpreting a listing or arranging funds. The governing documents and published terms should guide your preparation-not assumptions borrowed from another auction.
A tax-deed auction concerns the recovery of delinquent property taxes. That purpose does not establish that every other claim against the property disappears. County-owned surplus property is a separate transaction category, potentially involving competitive solicitations or sealed bids rather than a foreclosure auction.
For a buyer weighing an auction opportunity against Una Residences Brickell, the useful comparison is the acquisition path, not simply the price. This residential comparison does not imply that the alternative is offered at auction. The auction candidate requires its own legal and financial assessment.
For a Miami-Dade foreclosure purchase, review the court file before bidding. Read the final judgment and notice of sale rather than treating the auction listing as a complete account of the transaction. Have your attorney explain the proceeding and identify issues requiring further investigation.
Reconcile the legal description with the parcel record and the property you believe you are buying. A street address alone is not enough. Where the residence includes separately described interests or advertised features, ask counsel to establish exactly what the sale documents encompass. Do not assume that everything presented visually transfers together.
The objective is precise: the case, parcel, and intended residence should align. Resolve any discrepancy before bidding rather than leaving it as a post-purchase administrative task.
Order an independent title search and have a Florida real-estate attorney or title company evaluate recorded interests and potential surviving liens. A foreclosure auction carries no blanket promise of clear title. The auction administrator is not a substitute for independent advice.
Tax-deed purchases require the same caution. Certain governmental liens and judgments can survive such a sale. Whether a particular interest remains must be evaluated for the property and proceeding involved; the label “tax deed” is not a universal answer.
Ask about title insurance before committing funds. Determine whether an insurer anticipates requiring releases, other curative work, or litigation. Willingness to acquire the property is not confirmation that its title will be insurable on acceptable terms.
Request a written explanation of unresolved issues and proposed next steps. Where cost or timing cannot yet be established, carry that uncertainty into the investment decision rather than assigning it a convenient estimate.
Treat a tax-deed opportunity as an as-is acquisition, not an assurance of quality. Investigate the property before bidding and establish what access is available. Photographs and exterior impressions are not substitutes for an interior assessment.
For waterfront property in Miami Beach, a buyer comparing an auction candidate with The Perigon Miami Beach should keep lifestyle preferences separate from technical diligence. Views and design cannot resolve questions about condition or future expenditure.
Prudent buyer inquiries include insurance availability and pricing, flood exposure, and, where relevant, seawall condition. For a condominium, request available structural information, reserve information, association financial documents, and an estoppel for professional review. These are suggested investigation priorities-not a statement that every auction provides these materials or that each is a universal statutory prerequisite.
If inspection or documentation is unavailable, record the limitation explicitly. Unseen condition is an unresolved risk, not evidence that repairs will be modest.
Do not assume a successful bid delivers immediate vacant possession. Investigate occupancy and ask counsel what further steps may be needed to obtain possession in the specific case. Do not schedule a move, renovation start, or rental commencement based on the auction date alone.
For a second-home buyer, timing can matter as much as price. Assess whether the acquisition remains suitable if occupancy or title-related work takes longer than hoped. The home should fit your intended use under a cautious scenario, not only the most favorable one.
For a Miami-Dade foreclosure or tax-deed auction, confirm the applicable registration requirements through the county’s official auction system. Complete registration and verify the rules for the particular sale well in advance.
Confirm the deposit calculation, funding deadline, accepted payment methods, and deadline for the remaining balance. Do not import another county’s deposit percentage or assume the timetable of a negotiated residential closing. Broward and Palm Beach transactions require confirmation of their own applicable terms.
Ensure that funds can be delivered in the required form and within the stated period. If financing is part of your plan, establish whether it can satisfy those requirements before bidding. A preferred financing structure is not the same as available auction funds.
The maximum bid should reflect more than the amount displayed on screen. Build an acquisition budget that accounts for identified title work, potential surviving obligations, condition-related expenditure, insurance, professional advice, and possession-related uncertainty. Distinguish documented amounts from provisional allowances.
For a West Palm Beach search that also includes Alba West Palm Beach, compare alternatives on a consistent basis: total expected commitment, unresolved risks, and suitability for your intended use. A lower auction bid does not automatically mean a better acquisition.
Consider the eventual resale decision as well as the purchase. Before authorizing a bid, your advisers should be able to distinguish what is established, what requires further work, and what remains uncertain. Keep the ceiling fixed once bidding begins; unresolved diligence does not become less important because another bidder is active.
For a considered perspective on South Florida luxury residential opportunities, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIdentify whether the transaction is a mortgage foreclosure, tax-deed sale, association-lien foreclosure, or county-owned surplus sale. Confirm the governing documents and terms for that specific process.
No; review the court file, final judgment, and notice of sale with your attorney before bidding.
Reconcile the legal description, parcel record, and intended residence. Do not rely on the street address or photographs alone.
No; obtain an independent title search and professional review of recorded interests and potential surviving encumbrances.
Yes, certain governmental liens and judgments can survive. Have counsel assess the particular property and proceeding before committing to a bid.
Yes; ask whether coverage would require releases, other curative work, or litigation before deciding how much to bid.
Consider available inspections, insurance quotes, flood exposure, and relevant waterfront or condominium documentation. Treat unavailable access or records as unresolved risks, not assurances of acceptable condition.
Do not assume it will. Investigate occupancy and ask counsel what steps may be necessary to obtain possession.
Do not assume uniform terms. Verify the deposit, accepted funds, and payment deadlines for the applicable county and sale.
Evaluate total expected exposure, including title work, potential surviving obligations, condition-related costs, and possession uncertainty. Separate documented costs from provisional allowances before setting a ceiling.