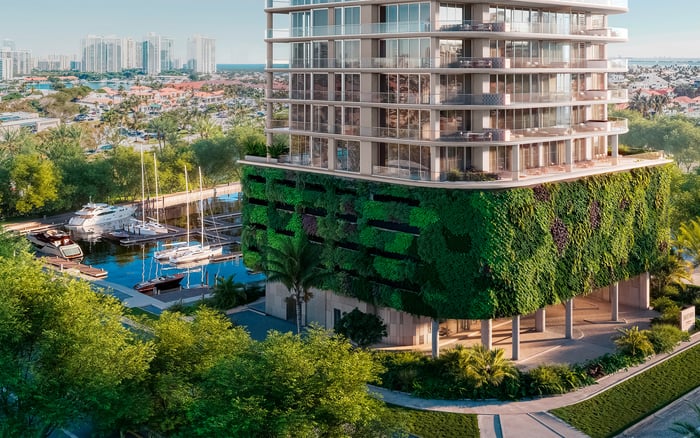
For a Zurich household considering Aventura, a disciplined purchase starts with the intended use, a buyer-specific tax estimate and a holding-period model that separates assessment protection from future resale economics.
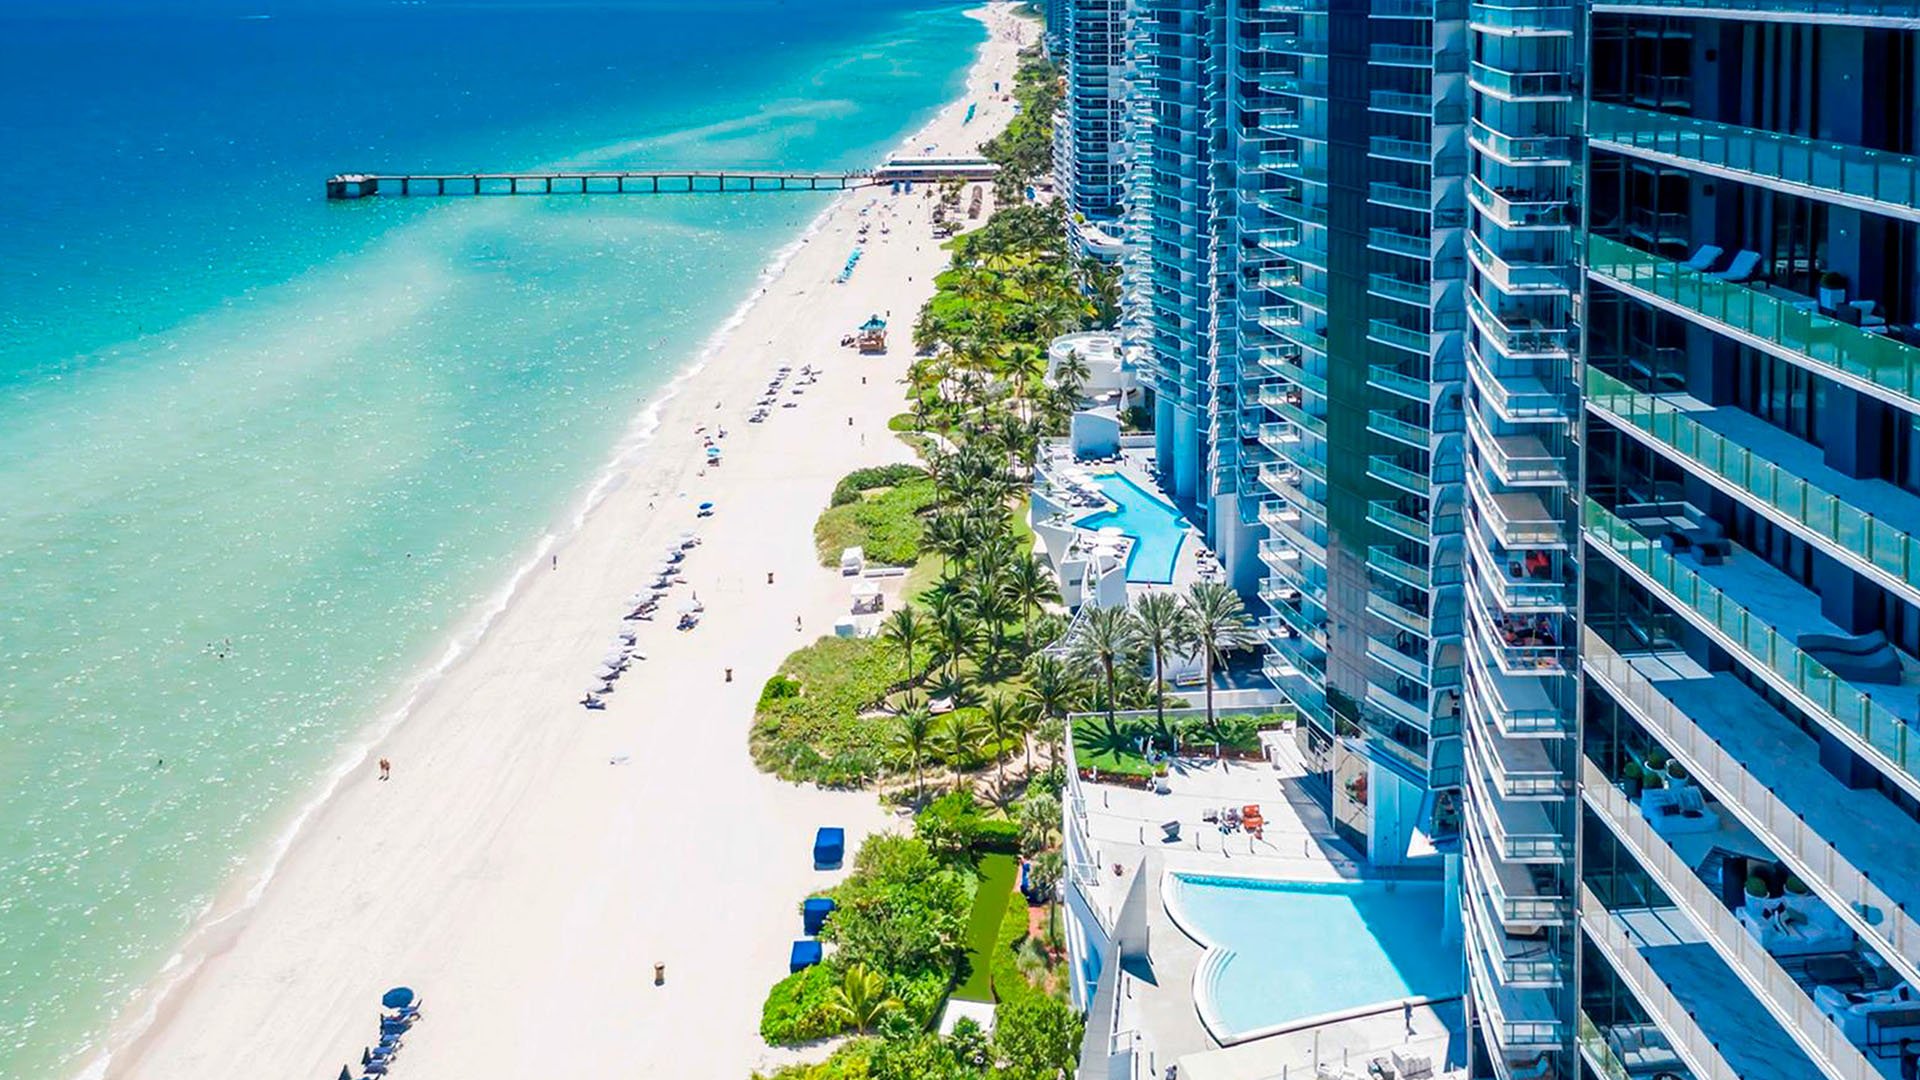
A move from Zurich to Aventura calls for two parallel decisions: which residence suits the household, and how it will be used. A primary home and a seasonal base may offer the same rooms, views and daily pleasures, yet follow materially different property-tax assessment paths. That distinction belongs in the acquisition brief, not in a discussion after closing.
For a buyer considering Avenia Aventura, start with two ownership scenarios: a qualifying homesteaded residence and a nonhomestead second home. Neither should be assumed simply because the family describes the purchase as a relocation. Confirm eligibility, documentation and applicable dates with qualified advisers before relying on homestead treatment.
The seller's tax bill describes the seller's position, not your future cost of ownership. That principle should guide the initial budget, the comparison between residences and the eventual exit plan.
A qualifying change of ownership or use generally triggers reassessment at just, or market, value on January 1 following the change. For a nonhomestead purchase, the new owner's assessment limitation then applies to subsequent annual assessments. It does not preserve the seller's accumulated protection.
A low existing assessment can therefore be misleading during negotiations. A longstanding owner's bill may reflect a substantial gap between capped assessed value and current market value. That accumulated nonhomestead benefit neither transfers to the purchaser nor travels with the seller to another property.
Request a buyer-specific estimate that distinguishes the existing assessment from the anticipated post-change assessment. Keep the acquisition-year estimate separate from the first post-reset year, and confirm the applicable adopted tax rates rather than carrying forward a headline figure. The purchase price alone is not a completed tax calculation.
Apply the same discipline when comparing One Park Tower by Turnberry North Miami. Evaluate each candidate using its own property details and confirmed tax assumptions, rather than applying one Aventura estimate across the shortlist.
Florida's nonhomestead assessment limitation generally caps annual increases in assessed value at 10% for nonhomestead residential property. Second homes, vacation homes and investment condos without a homestead exemption generally fall within this regime.
The protection is narrower than the phrase “tax cap” suggests. It limits assessment growth, not market value, tax rates or the total annual bill. Crucially, the 10% limitation does not apply to school-district assessments. A credible forecast therefore requires separate school and non-school calculations, with the relevant taxable values and rates applied to each.
Nor does 10% mean an automatic annual increase. It is a ceiling, and capped assessed value cannot exceed just value. An assessment can nevertheless rise while market value stays flat if the previous capped assessment remains below market value. A flat resale valuation is not sufficient reason to assume flat tax carry.
For budgeting, examine both the size of the assessment gap and the assumed direction of market value. Neither measure alone explains the next bill.
For qualifying homesteaded residences, Florida's Save Our Homes protection generally limits annual assessment increases to the lesser of 3% or the applicable CPI change. The homestead assessment limits were 2.90% for 2025 and 2.70% for 2026, compared with the 10% nonhomestead ceiling, excluding new construction.
Those percentages describe assessment rules, not a ready-made annual saving. A narrower limit may become significant over a holding period, but the difference depends on the assessment path, market values, exemptions and applicable levies. Purchase price alone cannot establish a dependable four- or five-figure advantage.
For the Zurich household, keep the qualifying primary-residence scenario conditional until eligibility is confirmed. An exemption filing date is not a substitute for establishing the applicable residency requirements. If the family initially retains the property as a second home, model that status for the relevant period rather than assuming future homestead protection applies from acquisition.
The property decision should remain financially comfortable under the ownership status you can actually support.
Build the tax forecast year by year across the intended holding period. Begin with the anticipated reset, then show assessed-value growth separately from tax-rate assumptions. Include a flat-market case in which an existing assessment gap can still produce increases, alongside scenarios for different market-value paths.
Keep school taxes visible rather than folding them into a single capped growth line. Review renovation plans separately: additions and improvements can add assessed value outside the ordinary 10% limitation. Before assigning a tax consequence to condo works, confirm the property classification and the treatment of the proposed improvements. A blanket renovation threshold is no substitute for that review.
If the search extends to Sunny Isles Beach and Turnberry Ocean Club Sunny Isles, use the same modeling structure with property-specific inputs. This allows a consistent comparison of tax carry without suggesting that different residences have identical costs.
Keep other ownership expenses in separate budget lines. The property-tax forecast should be transparent enough to revise without obscuring the household's wider annual commitment.
During ownership, an accumulated nonhomestead assessment benefit can reduce the assessment relative to market value. At resale, however, that benefit is not an asset the purchaser inherits. Your holding-period tax economics and the next buyer's post-reset economics require separate calculations.
Maintain both views when considering an exit: your projected cost of continuing to hold, and the buyer's potential carry after reassessment. A modest current bill should not be presented as the purchaser's dependable future obligation.
The assessment cap alone does not identify an optimal resale year. It establishes neither future Aventura pricing nor buyer demand or time on market. Selling solely because a particular ownership anniversary is approaching would give the tax rule more predictive power than it has.
Instead, compare candidate exit dates against your household's plans, remaining carrying costs and current market evidence. Treat accumulated assessment protection as one consideration in the decision to hold, not a promise of resale value.
Before committing, assemble a decision file covering intended use, confirmed eligibility assumptions, the expected reset assessment, separate school and non-school estimates, proposed improvements and alternative holding periods. Revisit it if the move becomes seasonal or the anticipated stay lengthens.
The objective is not to select a residence for its seller's tax history. It is to choose a home whose future obligations remain compatible with the life you intend to build.
For a discreet conversation about aligning your Aventura search with your ownership horizon, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe seller's assessment may reflect accumulated protection that does not transfer. A qualifying ownership change generally triggers reassessment at just value on January 1 following the change.
It generally limits annual increases in assessed value for nonhomestead residential property, excluding school-district assessments. It does not cap market values, tax rates or the total tax bill.
No. The 10% figure is a ceiling, and capped assessed value cannot exceed just, or market, value.
Yes. A nonhomestead assessment can rise if the previous capped assessment remains below market value, even when market value is flat.
Model them separately from capped non-school levies because the 10% nonhomestead limitation does not apply to school-district assessments.
Do not assume that relocation alone establishes eligibility. Confirm the applicable qualification requirements, documentation and dates before budgeting for homestead treatment.
Save Our Homes generally limits annual assessment increases on qualifying homesteaded residences to the lesser of 3% or the applicable CPI change. The 2026 homestead assessment limit is 2.70%.
No. The accumulated nonhomestead cap benefit is not portable to another property and does not transfer to a purchaser.
Yes. Additions and improvements can add assessed value outside the ordinary 10% limitation; confirm the treatment of specific condo works before budgeting.
No. Compare your continuing holding costs with the next buyer's post-reset carry, but assess resale timing against household plans and current market evidence rather than the cap alone.