A financed purchase at St. Regis® Residences Brickell calls for separate scrutiny of deposits, appraisal exposure and mortgage timing. The buyer’s executed contract and written lender terms should guide liquidity planning, not historical pricing or estimated construction milestones.
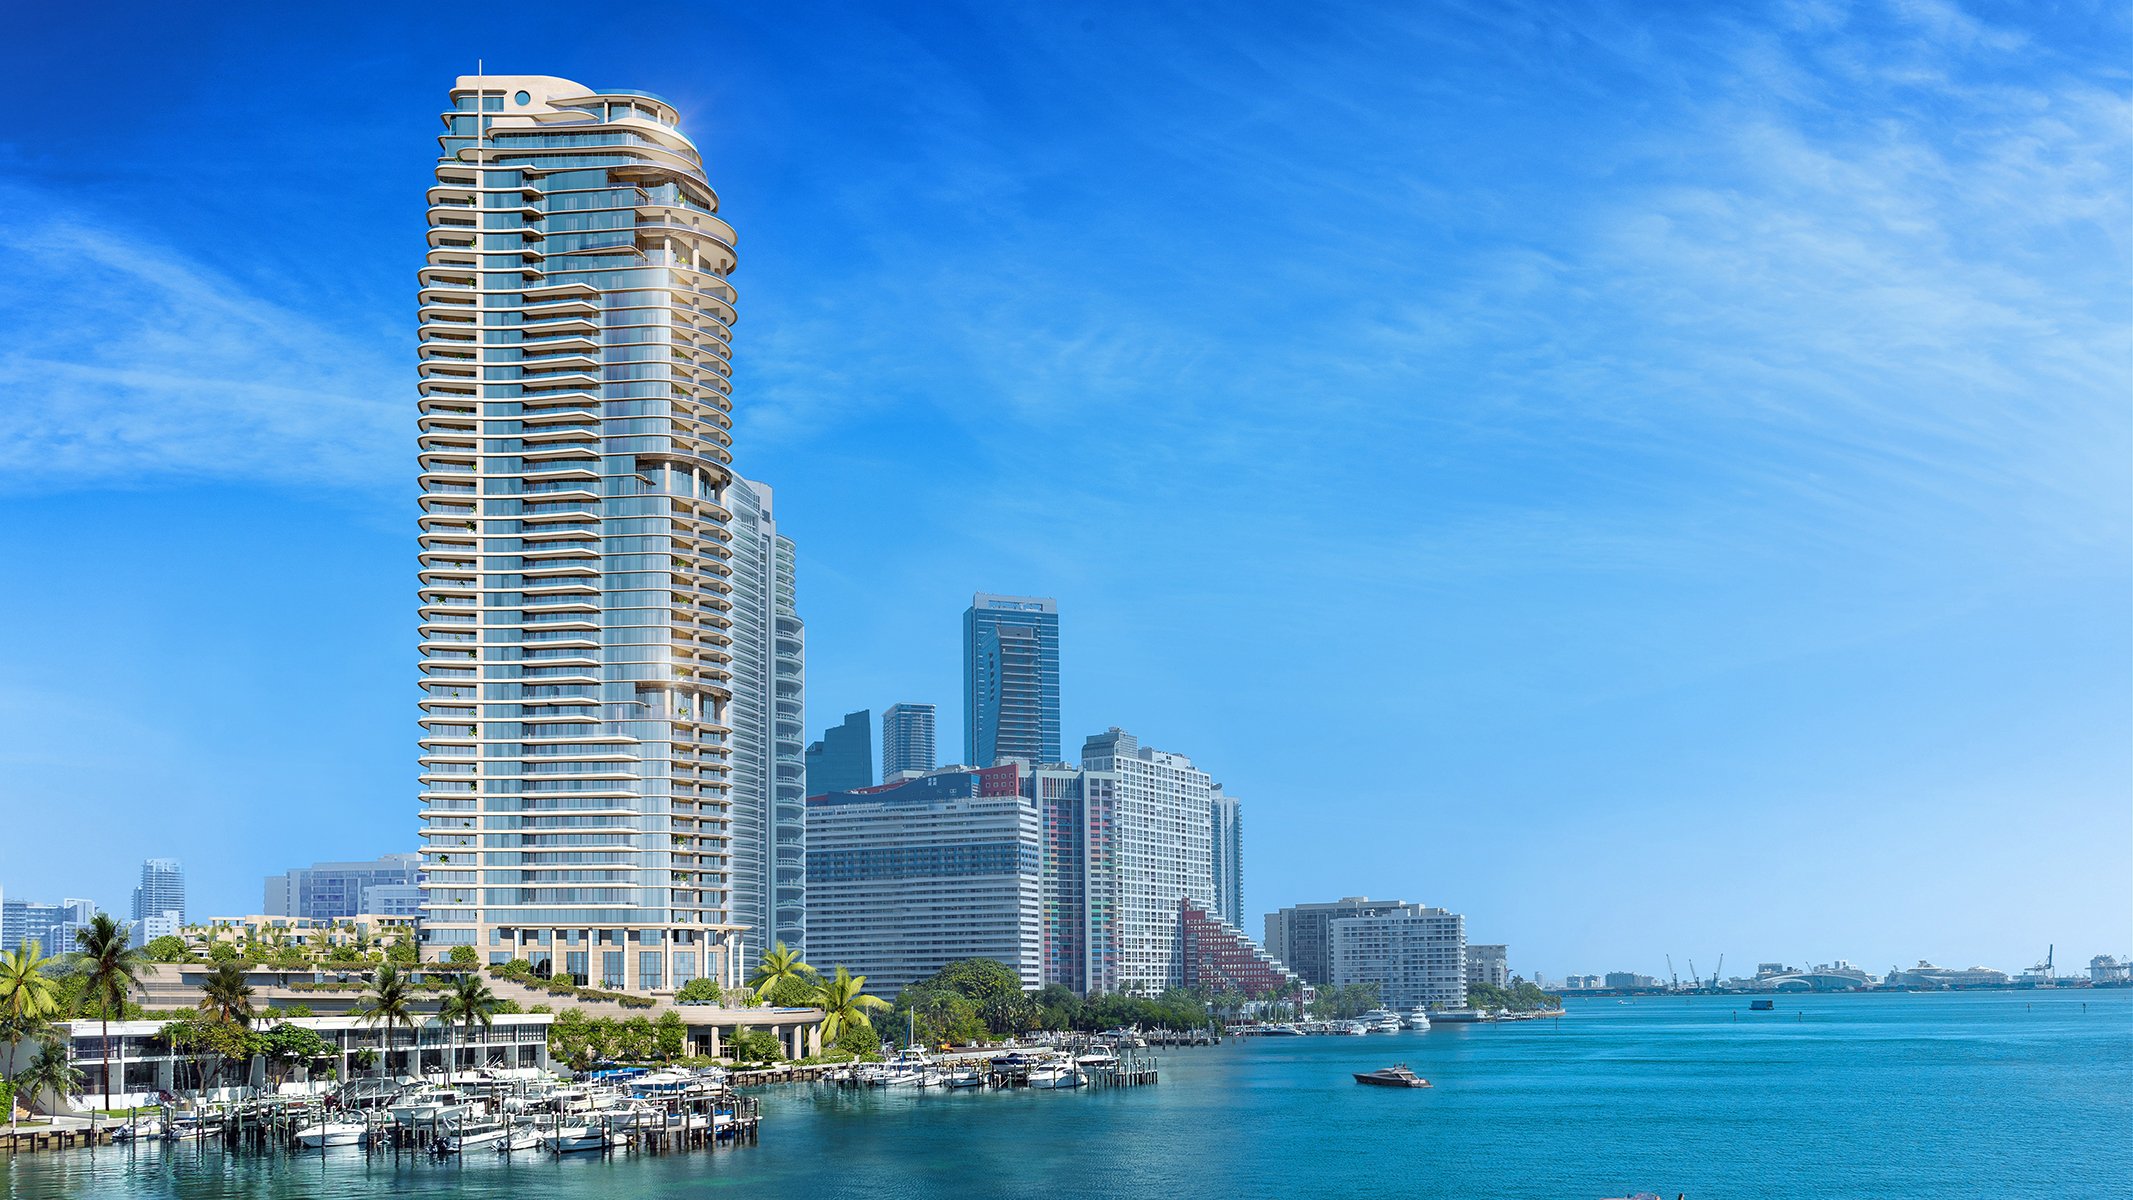
At St. Regis® Residences Brickell, the setting is specific: 1809 Brickell Avenue, on Miami’s Biscayne Bay waterfront. Related Group and Integra Investments are the developers. For a financed purchaser, however, the essential ownership question goes beyond residence selection: will the purchase contract, available liquidity and eventual mortgage terms remain aligned through closing?
An appraisal gap and a rate-lock deadline represent distinct risks. The first concerns valuation relative to the agreed price. The second concerns how long a lender’s quoted financing terms remain protected, subject to its written conditions. Neither risk is resolved simply because a buyer has committed substantial deposits.
The discipline is to separate the decision to buy from the financing assumptions that make the purchase comfortable. A desirable residence still warrants a conservative closing plan.
Groundbreaking took place in November 2024. Describing the development as still awaiting construction would therefore be misleading. The historical completion target was 2027, but that year is not a guaranteed closing date for an individual residence.
In November 2024, more than 65% of residences were under contract, with starting prices of $4.5 million and penthouse prices reaching $24.5 million. These are dated presale and pricing references-not completed-sale evidence, current inventory quotations or an appraisal of a particular unit.
The developers also secured a $527 million construction loan from Tyko Capital in September 2024. That financing belongs to the development, not to purchasers. It is neither an individual mortgage offer nor an assurance that a buyer’s preferred lender will fund a closing.
Before setting a financing calendar, request current, unit-specific closing guidance and ask counsel to identify the contract’s notice provisions. A target year is a planning reference; the contractual timetable requires separate attention.
Deposit schedules differ materially. One describes five construction-stage deposits totaling 50% of the purchase price, with 50% due at closing. Another sets out 20% initially, 10% at groundbreaking and 10% at top-off, leaving 60% at closing. The latter requires 40% before closing, not 50%.
Neither schedule should be assumed universal. Review the buyer’s executed agreement, amendments, payment triggers and treatment of deposits with counsel. Estimated milestone dates in a marketing schedule are no substitute for a current construction update or a contractual payment notice.
For liquidity planning, maintain a ledger separating deposits already credited, deposits still payable and the remaining purchase-price balance. Alongside it, record expected loan proceeds and other closing amounts confirmed by the relevant professionals. This keeps a substantial deposit history from obscuring the cash still needed at settlement.
If Cipriani Residences Brickell is also on the shortlist, apply the same contract-by-contract review rather than carrying St. Regis assumptions over to another address. Comparing residences is not the same exercise as comparing payment obligations.
An appraisal gap is the shortfall when a property’s appraised value falls below its contract price. It is a conditional risk here, not an established outcome: there is no basis to assume that a St. Regis residence will appraise below its agreed price.
The valuation shortfall and the buyer’s additional cash requirement are not necessarily equal. If a lender reduces anticipated proceeds under its valuation rules, the practical question is how much financing remains available relative to the unpaid purchase balance. Existing equity, the requested loan amount and the lender’s written terms all belong in that calculation.
Ask the lender to model both a valuation at the contract price and a lower valuation, with explicit assumptions. Request the resulting loan proceeds and cash-to-close figures, not merely a percentage description of the shortfall. This is a planning exercise, not a prediction of value.
Separately, ask counsel whether the agreement provides any appraisal or financing protection and what obligations remain if financing is reduced or unavailable. Do not assume a right to renegotiate, cancel or recover deposits. Nor should a generic appraisal-gap guarantee be treated as a project requirement or a suitable trophy-purchase reserve.
A completion target and a mortgage rate lock belong on separate lines of the buyer’s calendar. Before paying for a lock, establish what closing window the lender can accommodate and what evidence it requires to proceed.
No St. Regis-specific lock duration, extension fee, float-down right or purchaser mortgage program is established here. These require a written lender proposal; they should not be inferred from the building’s brand or construction financing.
Request clear answers on when the lock begins and expires, what happens if closing moves, whether extensions are available and how any cost is calculated. Ask whether a lower-rate adjustment is offered, what conditions apply and which borrower or property approvals remain outstanding. Confirm availability rather than presume it.
The useful comparison goes beyond the lowest quoted rate. Assess the proposed financing arrangement under both the expected closing window and a delayed one. A lock decision should reflect closing readiness and the buyer’s tolerance for uncertainty-not an attempt to forecast interest rates.
A buyer also considering The Residences at 1428 Brickell can use the same framework without assuming equivalent deposit terms, appraisal outcomes or mortgage access. Each purchase requires its own document set and financing analysis.
For St. Regis, assemble the executed contract and amendments, a deposit ledger, the residence specifications, current closing correspondence and the lender’s written proposal. Ask the lender which property documents it needs for valuation and approval, and who will obtain them. Keep those responsibilities explicit.
Bring the appraisal and timing reviews together in one final exercise: what happens if anticipated loan proceeds decline while the closing window also shifts? Ask the team to quantify the cash requirement under those stated assumptions, without double-counting deposits already credited.
The strongest position is not a universal reserve amount or a particular lock strategy. It is a documented plan showing what the buyer must pay, what the lender has actually committed to provide and which uncertainties remain. Have counsel and the financing adviser reconcile that plan before relying on it.
For a discreet perspective on Brickell ownership and residence selection, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe development is located at 1809 Brickell Avenue on Miami’s Biscayne Bay waterfront.
Related Group and Integra Investments are the project’s developers.
No. The historical completion target was 2027, not a guaranteed closing date for an individual residence; buyers should confirm current guidance and contractual notice requirements.
Published schedules differ, with one requiring 50% before closing and another requiring 40%. Buyers should confirm their executed contract and any amendments rather than assume either schedule applies universally.
An appraisal gap arises when the appraised value is below the contract price. The additional cash a buyer might need depends on how the lender’s terms affect available loan proceeds.
No appraisal-gap pattern is established here. Buyers should treat a lower valuation as a scenario to evaluate, not an expected outcome.
The $527 million construction loan secured in September 2024 was developer financing. It should not be treated as a mortgage program or financing assurance for individual buyers.
Coordinate the decision with a credible closing window and the lender’s written lock conditions. A historical completion target alone is not enough to establish suitable lock timing.
Ask about expiration, extension availability and costs, any lower-rate adjustment option, and outstanding approvals. No St. Regis-specific terms for these features are established here.
No. The $4.5 million starting price and penthouse prices up to $24.5 million are historical references, not verified current inventory quotations.