A buyer-oriented review of Shorecrest condominium transaction planning, with a focus on complete resale disclosures, reliable estoppel information, and expressly negotiated transfer-approval protections.
For a luxury condominium buyer, operational clarity is part of the asset. A carefully selected residence deserves an equally disciplined closing: complete documents, reconciled association charges, and certainty about the status of any required transfer approval. At Shorecrest Flagler Drive West Palm Beach, the review should begin with the legal framework governing the purchase, not assumptions drawn from the project's presentation.
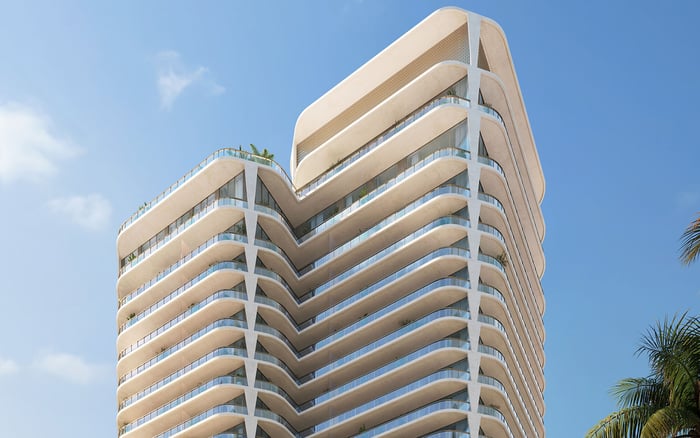
Shorecrest is a condominium project at 1701 N. Flagler Drive, West Palm Beach. Buyers should consult the condominium offering documents and applicable purchase agreement, rather than rely on project representations unless incorporated into the prospectus or applicable agreement. The practical implication is straightforward: expectations that matter should be confirmed in the controlling documents.
An original developer purchase and a nondeveloper resale are not interchangeable. The discussion below addresses nondeveloper resale planning where applicable. It does not establish that Shorecrest currently requires transfer approval or prescribe its screening criteria, fees, processing time, or assessment balances. Those details require transaction-specific confirmation.
The required condominium resale package includes the declaration, articles of incorporation, bylaws, and association rules. It also includes required FAQs and governance documentation, the most recent year-end financial statement, and the annual budget. For a nondeveloper resale, the seller generally supplies the required documents at the seller's expense.
These materials serve distinct purposes. Governing documents establish the framework for ownership and transfers; financial materials help buyers evaluate the association's operating commitments. A polished marketing package is no substitute for either. Ask the transaction team to distinguish required disclosures from supplementary material and identify what has actually been delivered.
Unlike the estoppel certificate, residential condominium resale documents have no comparable fixed statutory delivery deadline. An express contractual deadline is therefore important. The agreement should identify the required package, the delivery method, and a date that allows time for review before closing. Keep a record of receipt rather than relying on an informal assurance that documents were sent.
For buyers also considering Alba West Palm Beach, the same discipline provides a useful comparison framework: identify the transaction type first, then examine the documents applicable to that purchase. Do not assume another project's disclosure requirements or approval procedures carry over to Shorecrest.
Receipt of the required documents affects the applicable nondeveloper buyer cancellation period. The operative contract disclosure clause deserves attention before signing, not only when the package arrives. Counsel should confirm the applicable statutory language, triggering events, and calculation of the review period against the executed agreement.
A statutory cancellation opportunity is not an unlimited right to renegotiate every concern uncovered during diligence. Broader document-review objections, additional termination rights, deposit-return provisions, and closing extensions should be expressly negotiated where desired. They are not automatic remedies.
The strongest approach separates two questions: when must the seller deliver the complete package, and what may the buyer do after reviewing it? A delivery obligation without a clear contractual response to delay can leave practical uncertainty. Conversely, a review provision is difficult to administer without a reliable record of receipt.
Florida condominium associations must issue an estoppel certificate within 10 business days after receiving a qualifying written or electronic request. The request may come from the unit owner, the owner's designee, the unit mortgagee, or the mortgagee's designee. Assign responsibility early and retain evidence of receipt.
The certificate's effective period matters as much as its delivery deadline. An estoppel delivered by hand or electronically generally has a 30-day effective period; one sent by regular mail generally has a 35-day period. These periods are distinct from the 10-business-day issuance requirement.
Order early enough to investigate discrepancies, but check the certificate's effective period against the expected closing date. Ordering alone does not complete the task. If closing moves, the team should reassess whether the certificate remains effective and whether updated documentation is needed.
A buyer evaluating Forté on Flagler West Palm Beach alongside Shorecrest should apply the same calendar discipline to each transaction independently. A similar location does not establish identical association procedures, account balances, or closing readiness.
The condominium estoppel must disclose amounts owed and applicable assessment information, including scheduled assessments and approved special assessments. Late fees and applicable transfer-related charges belong in its required account and transaction disclosures. Treat the certificate as a financial control document, not merely another closing attachment.
Compare it with the seller's ledger, association statements, assessment notices, and the contract's allocation of charges. Determine whether a listed amount is already due, scheduled for later payment, or subject to allocation between buyer and seller. Even an accurately disclosed assessment must be handled consistently with the purchase agreement.
Resolve discrepancies before closing. If a ledger and certificate differ, seek clarification rather than assuming the smaller figure controls. Likewise, an approved special assessment should not fall out of the discussion simply because its payment schedule extends beyond the planned transfer.
Florida's estoppel framework limits an association's ability to collect amounts omitted from required disclosures from a purchaser who relies on the certificate in good faith. That protection supports careful reliance; it does not justify ignoring conflicting account information already in hand.
The estoppel must state whether the association's rules require board approval to transfer the unit. If approval is required, it must also indicate whether the board has approved the transfer. Financial information in a certificate does not, by itself, establish that an outstanding approval has been granted.
If Shorecrest's governing documents require approval, negotiate a separate written-approval contingency. It should address application responsibility, submission requirements, fees, deadlines, and the consequences of delay or denial. Any intended extension, termination, or deposit-return rights should be written into the agreement, not inferred.
For purchasers comparing Mr. C Residences West Palm Beach, this is another point to evaluate independently. Approval requirements must come from the applicable documents, not assumptions about the wider market.
Before closing, confirm three matters separately: delivery and review of the required resale package, an effective and reconciled estoppel, and written transfer approval if required. This is general transaction-planning guidance; counsel should confirm the applicable law and negotiated protections for the actual purchase.
For a considered approach to West Palm Beach ownership, explore the residential collection at MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationShorecrest is a condominium project at 1701 N. Flagler Drive, West Palm Beach.
They should not be assumed to apply. The transaction type determines the relevant disclosure framework and documents.
Required materials include the declaration, articles of incorporation, bylaws, association rules, required FAQs and governance documentation, the most recent year-end financial statement, and annual budget.
For a nondeveloper resale, the seller generally supplies the required condominium documents at the seller's expense.
Residential condominium resale documents do not have a fixed statutory delivery deadline comparable to the estoppel issuance deadline. An explicit contractual delivery date helps coordinate review and closing.
A Florida condominium association must issue the certificate within 10 business days after receiving a qualifying written or electronic request.
An estoppel delivered by hand or electronically generally has a 30-day effective period. One sent by regular mail generally has a 35-day effective period.
Check amounts owed, scheduled assessments, approved special assessments, late fees, and applicable transfer-related charges. Reconcile those disclosures with account records and the contract's allocation of charges.
That requirement must be confirmed in the applicable governing documents. The estoppel must state whether approval is required and, if so, whether the board has approved the transfer.
They should not be assumed to be automatic. Intended protections for approval delays or denial, including termination, deposit return, and extensions, should be expressly negotiated.