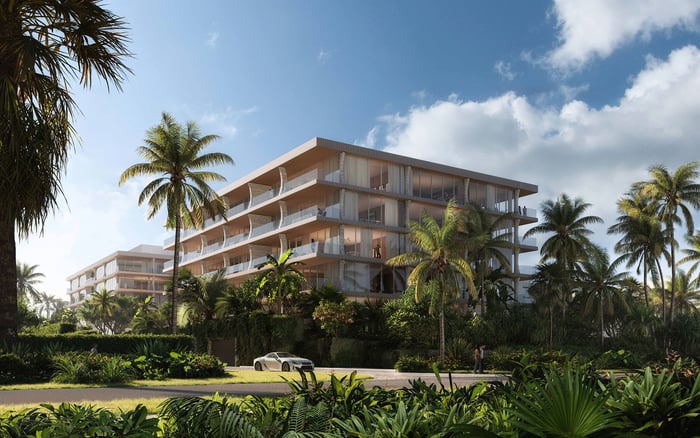
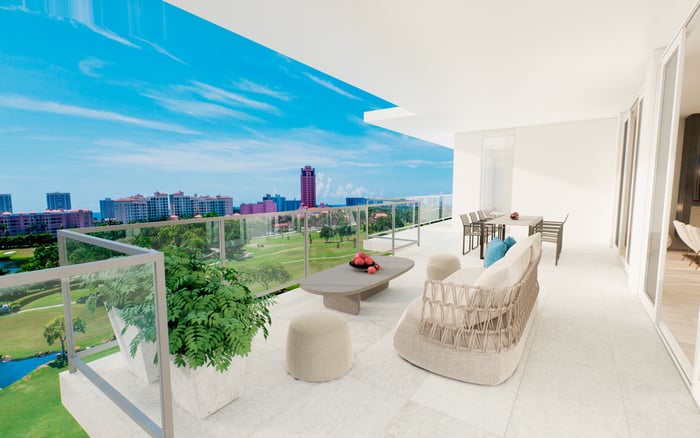
A multigenerational move from Beverly Hills to Boca Raton calls for more than a compelling floor plan. Separate closing cash from household reserves, confirm insurance effective dates, examine title restrictions, and keep financing protections aligned with the contract.
Moving a multigenerational household from Beverly Hills to Boca Raton is both a residential decision and a coordination exercise. The home must accommodate shared time, private routines, and changing needs. The purchase plan demands equal care: sufficient closing cash, insurance effective when needed, a clear understanding of title, and financing protections that remain useful through closing.
Start with a written household brief. Identify who will live in the residence, whether separate living areas are essential, and which alterations are prerequisites rather than future preferences. For a family considering Alina Residences Boca Raton, that brief should guide questions about the specific residence and its governing documents-not assumptions about permitted occupancy or modifications.
The objective is to align the purchase with the household’s actual needs before deadlines narrow the choices. Keep household requirements and transaction milestones in the same planning file.
Avoid treating closing costs as a single percentage of the purchase price. Request an itemized estimate that separates transaction charges from prepaid insurance, taxes, and escrow deposits. For a financed Florida purchase, potential expenses include note documentary stamp tax, mortgage intangible tax, recording charges, lender fees, appraisal costs, surveys, and inspections.
Boca Raton is in Palm Beach County, where the deed documentary stamp tax is $0.70 for each $100 of taxable consideration. At $3 million in taxable consideration, the charge is $21,000. That calculation does not establish who must pay it. The purchase contract should determine expense allocation; local custom is no substitute for the signed agreement.
Build a separate discretionary post-closing reserve for the family’s priorities. Repairs, accessibility work, backup power, and furnishings belong in that plan, but no universal reserve amount suits every household. Do not confuse this reserve with prepaid escrows or the cash required to complete the purchase.
Ask for an updated estimate as financing and insurance figures become firmer. The useful measure is not simply total liquidity, but what remains available after the transaction and planned work.
Treat insurance binding as a scheduled task, not a final administrative detail. Ask the insurance professional to confirm what is needed to put coverage in force, its effective date, and the evidence the lender will accept. A premium estimate alone is not confirmation that coverage is active.
Evaluate flood coverage separately. Standard homeowners insurance generally does not cover flooding. Federally regulated or insured lenders require flood insurance for mortgaged properties in designated high-risk flood areas, and some lenders require it outside those areas. Boca Raton’s Special Flood Hazard Areas include Zones AE, AH, AO, and VE; verify the particular property’s designation rather than relying on its appearance or neighborhood.
Confirm any waiting period, applicable exceptions, and the policy’s actual effective date rather than assuming immediate coverage or an unavoidable delay. NFIP coverage is available for eligible buildings and contents in participating communities both inside and outside floodplains.
For a household coordinating several arrivals, align insurance effective dates with closing and intended occupancy before finalizing the move.
A title examination reviews public-record evidence of ownership and identifies restrictions, easements, defects, and claims affecting the property. Request the title commitment early enough for counsel to assess both the requirements for issuing the policy and the exceptions to coverage.
The review should address the legal description, outstanding mortgages, liens, ownership complications, access rights, and recorded use restrictions. For a multigenerational household, the practical question is whether those restrictions conflict with the intended use, including separate living areas or planned modifications.
When evaluating Glass House Boca Raton, apply the same residence-specific discipline: ask counsel to compare the household brief with the relevant documents. A project name or appealing layout does not establish permission for a particular occupancy arrangement.
Title review is only one part of that inquiry. Zoning, permits, occupancy requirements, and association rules require separate verification. Do not assume that a satisfactory title review confirms the legality of a proposed guest suite, alteration, or living arrangement.
A financing contingency can make the purchase dependent on obtaining a specified loan amount and terms within a contractual deadline. Its value lies in the signed language, dates, and required notices-not simply in a preapproval letter.
Review the financing provision for loan terms, the approval deadline, valuation requirements, and procedures if financing cannot be obtained. Where the contract requires an appraisal or alternative valuation acceptable to the lender, that valuation must support the contemplated financing. Strong borrower qualifications do not eliminate property-related financing conditions.
A low appraisal can therefore create a cash gap even when the borrower qualifies. Additional cash, renegotiation, or a timely contractual remedy may become relevant, depending on the agreement. Decide in advance how much additional cash the household is willing to commit without undermining its post-closing plans.
If financing is delayed, request extensions of both the closing date and the financing-contingency period. Extending closing alone does not necessarily preserve financing protection. Have counsel confirm the agreed dates and any required notices rather than relying on an informal understanding.
For a family weighing The Residences at Mandarin Oriental Boca Raton, the same four-part review should accompany the residential comparison: cash allocation, insurance timing, title and use restrictions, and financing deadlines. None should be deferred simply because the residence otherwise suits the family.
Before signing closing documents, compare the proposed settlement statement’s charges, credits, and prorations with the purchase contract and financing documents. Resolve unexplained differences with the closing team. Recheck which expenses are buyer obligations and which amounts are prepayments or escrow deposits.
Finally, confirm that the household’s discretionary reserve remains intact after any changes to cash due at closing. A purchase can be financially achievable yet leave too little flexibility for the work that makes multigenerational living comfortable. A considered purchase aligns the residence’s legal use, insurance, financing, and remaining budget with the same family plan.
Explore Boca Raton residences with MILLION and bring a clear household brief to your next property conversation.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe rate is $0.70 per $100 of taxable consideration. At $3 million in taxable consideration, the charge is $21,000, but the contract determines payment responsibility.
An itemized estimate is more useful because it separates transaction charges from prepaid insurance, taxes, and escrow deposits. Review expense allocation against the purchase contract.
There is no universal reserve amount appropriate to every household. Budget separately for anticipated repairs, accessibility work, backup power, and furnishings rather than treating these funds as closing cash.
Standard homeowners insurance generally does not cover flooding. Buyers should evaluate flood coverage separately and confirm the lender’s requirements.
Federally regulated or insured lenders require it for mortgaged properties in designated high-risk flood areas. Some lenders also require coverage outside those areas.
Confirm any waiting period, applicable exceptions, and the policy’s actual effective date with the insurance professional. Do not assume coverage begins immediately or that a delay is unavoidable.
Counsel should review issuance requirements and coverage exceptions, along with the legal description, liens, outstanding mortgages, access rights, ownership issues, and recorded restrictions.
No. Zoning, permits, occupancy requirements, and association rules need separate verification alongside title review.
Yes, a low appraisal can create a funding gap despite the borrower’s qualification. Additional cash, renegotiation, or a timely contractual remedy may be relevant, depending on the signed agreement.
Not necessarily. If financing is delayed, request extensions of both the closing date and the financing-contingency period, with counsel confirming the agreed deadlines and required notices.