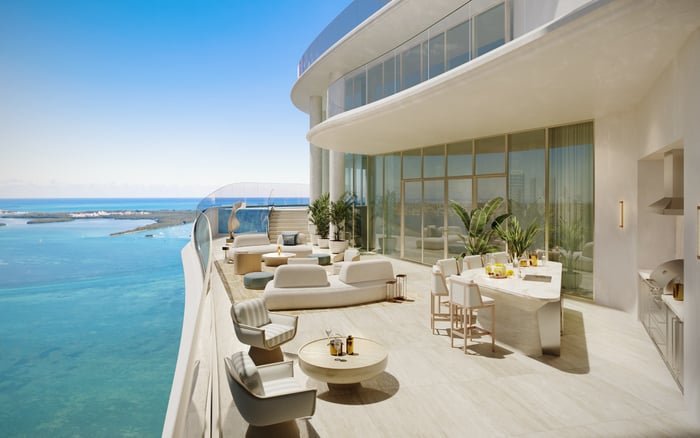
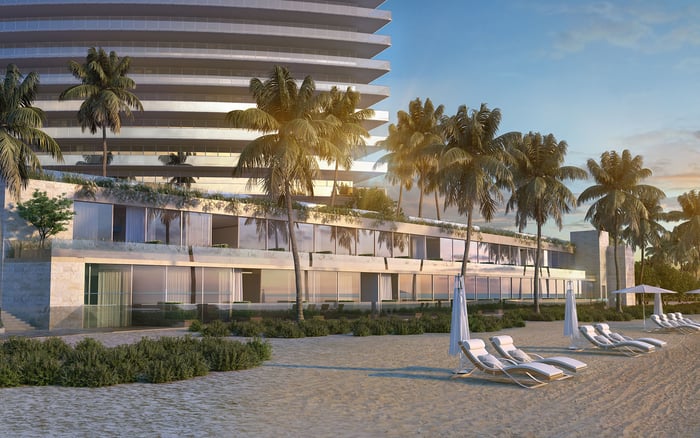
Moving a primary residence from Dubai to Sunny Isles Beach calls for more than finding the right apartment. A disciplined plan separates sale proceeds, purchase commitments and verified liquidity, while preserving room to negotiate without relying on an unconfirmed bridge or transfer timetable.
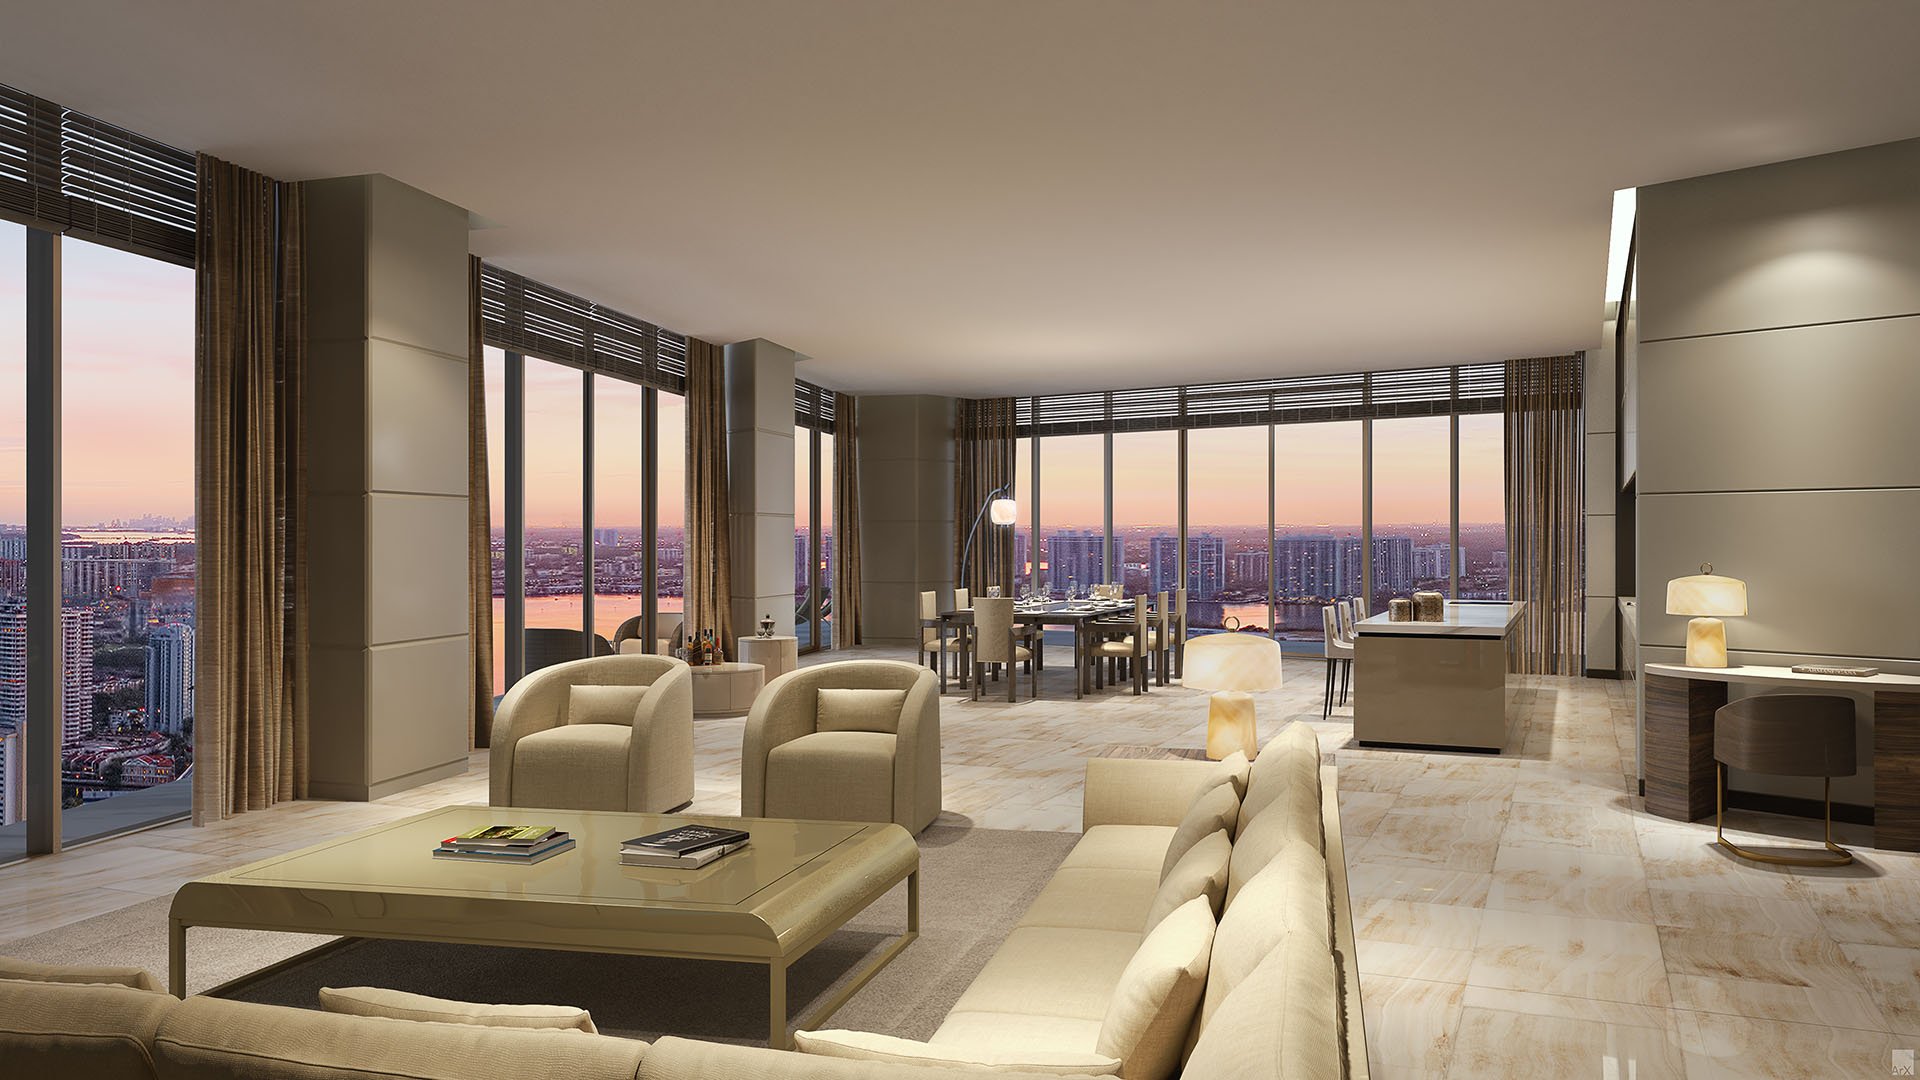
Making Sunny Isles Beach the primary residence after Dubai is as much a capital-planning decision as a residential one. The objective is not simply to exchange one property for another. It is to secure the right home without letting an unfinished sale, an unconfirmed loan or an uncertain transfer schedule dictate the purchase.
Start by separating three amounts: money available now, net proceeds expected from the Dubai sale and financing that remains conditional. Build the Florida acquisition plan around the first until the others are confirmed. The sequence below is a planning framework, not a lender requirement or a substitute for negotiated contract terms.
Sunny Isles Beach had an estimated 22 months of supply in Q1 2026. That suggests negotiating room across the market, but it does not establish the position of a particular building or residence. More broadly, average marketing time stood at 189 days, versus 148 a year earlier. Those figures describe time on the market, not the interval between signing and settlement.
Distinguish resale conditions from ultra-luxury preconstruction, where supply was constrained in Q2 2026. Neither segment should be treated as a proxy for the other.
For buyers considering Jade Ocean Sunny Isles Beach, mid-year 2026 conditions across Jade Ocean, Jade Beach and Jade Signature included increased inventory, longer marketing periods and greater willingness to negotiate than during 2021-2023. That context supports a measured offer strategy-not an assumption that a seller will accept a Dubai-sale contingency.
Some sellers were accepting 5%-15% below previous peak pricing in mid-2026. That does not represent a citywide discount from current asking prices. Keep the price discussion separate from requests for extra time, furnishings or closing-cost credits.
Consider three possible structures before making an offer.
Sell first, then purchase.
This replaces an estimated sale outcome with known proceeds. The trade-off is residential timing: consider whether temporary accommodation would be acceptable if the preferred Florida home is not ready when the Dubai sale completes.
Purchase with independent liquidity.
If available capital can cover the acquisition without the Dubai proceeds, evaluate the purchase on that basis. Preserve a separate reserve rather than treating every accessible dollar as purchase money. The sale can then be considered independently, subject to the household's wider financial priorities.
Coordinate the transactions.
A purchase linked to the Dubai sale requires careful negotiation of dates and protections. Ask counsel to assess any proposed sale contingency or extension provision before relying on it. Longer marketing periods do not guarantee acceptance.
When assessing a residence at Jade Signature Sunny Isles Beach, distinguish its suitability as a home from its fit with your timetable. A compelling apartment can still be the wrong transaction if its proposed funding dates outpace confirmed liquidity.
Evaluate a bridge; do not presume it will be available. Do not assume that a Dubai property will qualify as collateral, that a particular lender will finance the transition or that approval will arrive before a Florida deposit is due.
Ask prospective lenders for written answers on collateral eligibility, borrower requirements, net usable proceeds, pricing, fees, maturity, repayment conditions and draw requirements. Clarify which conditions remain outstanding and what must happen before funds can be accessed.
Stress-test the proposal against a delayed Dubai sale and lower net sale proceeds. Ask what additional cash would be needed, whether an extension is available and what it would cost. An expected sale date is no substitute for an agreed repayment plan.
For a purchase under consideration at Armani Casa Sunny Isles Beach, compare the full proposed financing cost with the value of buying sooner. Avoid paying for temporary liquidity merely to preserve a timetable that could reasonably be adjusted.
Treat evidence of wealth, evidence of available purchase funds and confirmation of closing funds as separate planning questions. A property valuation or expected sale price should not be presented as cash already available.
Establish three checkpoints with the relevant transaction parties:
Before the offer: Ask what evidence the seller will accept, how recent it should be and whether the account holder matches the proposed purchaser. Identify any amount that depends on financing or an unfinished sale.
Before each deposit: Confirm the contractual amount and due date, then verify that the designated funds are accessible. Do not build the deposit plan around an unconfirmed bridge draw.
Before closing: Ask the closing team and banks to confirm required documentation, transfer instructions and the date by which funds must be received and usable.
These are recommended checkpoints, not universal proof-of-funds deadlines. Obtain transaction-specific instructions rather than assuming one bank statement will serve every purpose.
Florida closings may occur approximately 30-90 days or more after contract, particularly with financing. That is a planning range, not a settlement guarantee or an international-wire timetable. Build a calendar with counsel, the closing team, lender and banks, allowing time for unresolved conditions. Do not promise a transfer arrival date without confirmation from the institutions involved.
Create an acquisition budget alongside the liquidity calendar. Ask for estimates of closing expenses and applicable documentary stamp taxes on the relevant deed and mortgage instruments. Confirm which charges apply and who pays them under the proposed transaction.
For any candidate, including Turnberry Ocean Club Sunny Isles, request current, property-specific information to assess recurring ownership costs. Budget separately for the move and any intended furnishing or alterations. These are diligence requests, not assumptions about a particular residence.
Primary-residence planning also warrants a separate review. Florida owners may qualify for homestead treatment when the property is their permanent residence or their dependent's permanent residence. The exemption can reduce taxable property value by as much as $50,000; it does not reduce the tax bill by $50,000. Confirm eligibility and filing requirements with the county property appraiser rather than treating the benefit as automatic upon purchase.
The strongest relocation plan leaves room to decline a transaction whose dates cannot be supported. Before signing, know which funds are available, which remain conditional and what happens if the Dubai sale takes longer than expected.
Negotiate price and timing together, but assess them separately. A lower price does not cure a funding gap, and a preferred closing date does not make an unconfirmed bridge dependable. The goal is a primary residence acquired on terms the household can comfortably execute.
For a discreet conversation about your Sunny Isles Beach search and purchase priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationSelling first replaces expected proceeds with a known amount, but may require flexibility on accommodation and purchase timing. Independent liquidity or a negotiated coordinated transaction are alternatives to evaluate.
No. The approximately 22 months of supply estimated for Q1 2026 is a market-level measure, not a building-specific indicator.
No. Marketing periods are distinct from contract-to-closing timelines and should not be used to schedule settlement.
Acceptance must be negotiated. Longer marketing periods and greater inventory do not guarantee a sale contingency or closing extension.
No. Ask a prospective lender to confirm collateral eligibility, borrower requirements and access conditions before relying on a bridge.
Clarify acceptable evidence before making an offer, then verify funding readiness before each deposit and closing. Exact documentation and deadlines must be confirmed for the transaction.
Keep expected proceeds separate from funds already accessible. Do not present an estimated sale outcome as money already available for the purchase.
Approximately 30–90 or more days is a planning range, particularly with financing, not a guarantee. Confirm contractual dates and funding arrangements with the transaction team.
No. The exemption may reduce taxable property value by as much as $50,000, subject to eligibility and filing requirements, rather than reducing the tax bill by that amount.
Include applicable documentary stamp taxes on relevant deeds and mortgage documents. Ask the closing team to confirm applicable charges and contractual payment responsibility.