A Boston-to-Pompano Beach move calls for a residence-specific cash-flow plan. Separate association dues from owner insurance, property taxes, optional services, furnishing, and assessment exposure before setting the first-year budget.
Making Pompano Beach your primary residence after Boston changes the financial brief. The apartment is no longer simply a coastal retreat; it becomes the setting for daily routines, entertaining, work, and the possessions that make a home complete. The question is not just what ownership costs annually, but when each payment leaves your account.
Start with two schedules: recurring ownership expenses and one-time establishment costs. Keep association dues, property taxes, owner insurance, and optional services in the first. Place furnishing in the second, and track special assessments separately rather than folding them into ordinary dues. This framework covers those ownership categories, not acquisition costs or mortgage payments.
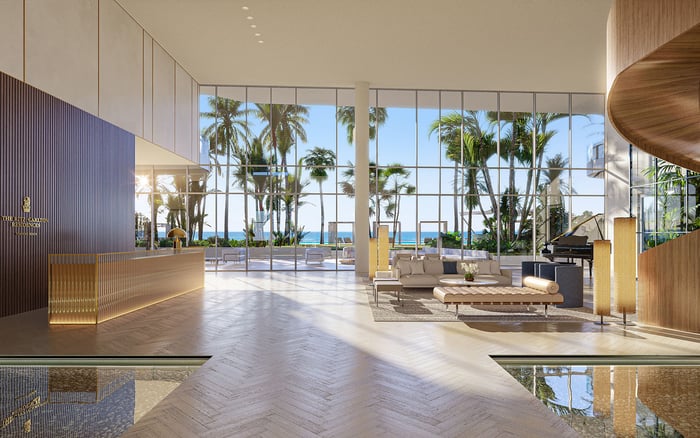
For a buyer considering The Ritz-Carlton Residences® Pompano Beach, the same discipline applies: obtain residence-specific financial documents before translating a preferred lifestyle into an annual allowance. A project name is no substitute for a written operating budget.
Two Pompano Beach examples show why association costs require unit-level attention. At 407 N. Riverside Drive #602, disclosed HOA dues are $2,063 monthly, or $24,756 over 12 months. At Pompano Beach Club South, disclosed association fees span $704 to $1,342 monthly, equivalent to $8,448 to $16,104 annually.
These calculations assume 12 months of unchanged dues and exclude separate assessments or charges. They are individual examples, not a representative range for luxury condominiums, and should not be applied to another building or residence.
Pompano Beach Club South includes internet in its association fees. That inclusion does not establish that every utility, insurance component, or optional service is covered. Build a checklist that separates what the association pays from what the owner must arrange independently.
Before committing, request the association budget, reserve information, assessment notices, inspection documentation, and master-policy declarations. Ask which charges apply to the selected residence and whether approved changes affect the first year of ownership. The goal is a confirmed baseline with a clear record of inclusions, exclusions, and effective dates.
A primary residence deserves a service plan based on actual habits. Identify the assistance you would want, such as housekeeping or help preparing for guests. Then ask whether it is available, who provides it, and how it is billed. These are purchasing questions, not assumptions about any building's offerings.
When evaluating Armani Casa Residences Pompano Beach, request written confirmation of included services and separately priced options. Distinguish access to an amenity from the cost of using a service associated with it.
For each selected service, record the quoted price, expected frequency, start date, cancellation terms, and any minimum commitment. Keep occasional entertaining support separate from routine household assistance. Avoid treating a generic annual service allowance as a local benchmark. A tailored schedule is more useful and less likely to conceal duplicate charges.
Keep the owner's insurance line provisional until a broker has reviewed the specific residence and relevant association coverage. Do not assume the master policy eliminates the need for separate owner protection, or treat an association insurance expense as your personal premium.
Request a written explanation of the proposed owner policy's coverage, exclusions, and deductibles, and how it relates to the master policy. Discuss personal belongings, interior finishes, liability, and any separate coverage the broker recommends for the property's circumstances. Resolve these points in the quote rather than presuming they are included.
For cash-flow purposes, enter the quoted premium on its actual payment schedule. Keep deductible exposure visible alongside the premium, but distinct from an annual charge. A countywide average cannot determine the cost or coverage needs of a particular coastal residence.
Property taxes require a buyer-specific estimate, not a copied figure. The Riverside Drive example includes a $170 tax figure without an established period or assessment basis. It is therefore unsuitable as an annual tax budget.
Purchasing a home and establishing a permanent residence are distinct events. A new Broward owner must apply for a new Homestead Exemption; an existing exemption should not be assumed to transfer. Eligibility depends on the residence becoming the owner's permanent home for the relevant tax year. Homestead can reduce taxable value, but it is not a fixed first-year relocation credit.
A Boston property does not create Florida portability benefits. Portability concerns an eligible Save Our Homes assessment difference from a prior Florida homestead, not the Homestead Exemption itself. If you also have a qualifying Florida homestead history, evaluate it separately and submit the additional portability application where applicable.
The applicable portability window requires homestead on the new Florida residence within three tax years of selling or abandoning the previous homestead. March 1 is the general filing date, but the year's county calendar matters. For 2026, Broward's timely exemption deadline was March 2 and its late-filing deadline was September 18. Both dates have passed as of this article's publication; confirm the applicable filing year before assuming any benefit in your budget.
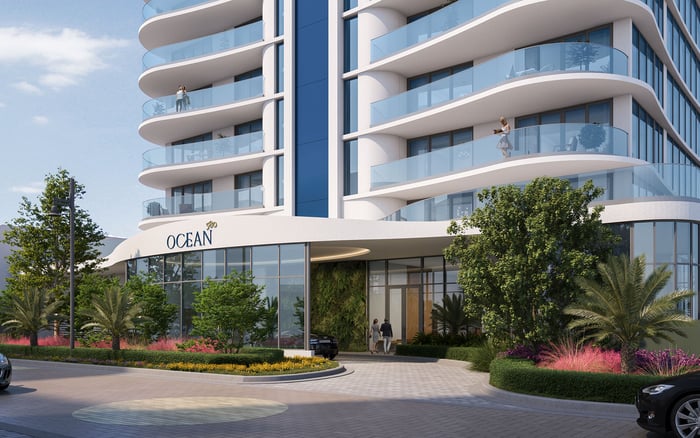
For buyers considering Ocean 580 Pompano Beach, furnishing should begin with the selected residence's dimensions and confirmed delivery condition, not a generic luxury-home allowance. Decide which Boston pieces will move, which rooms must function immediately, and which purchases can wait.
Request itemized proposals for the intended scope, including furniture, window treatments, lighting, installation, and delivery where relevant. Confirm each proposal's inclusions rather than assuming every ancillary expense is covered.
Translate accepted proposals into dated payments. Separate deposits, progress payments, and final balances where the contract calls for them. This prevents the move-in period from appearing artificially inexpensive simply because some balances fall later in the year.
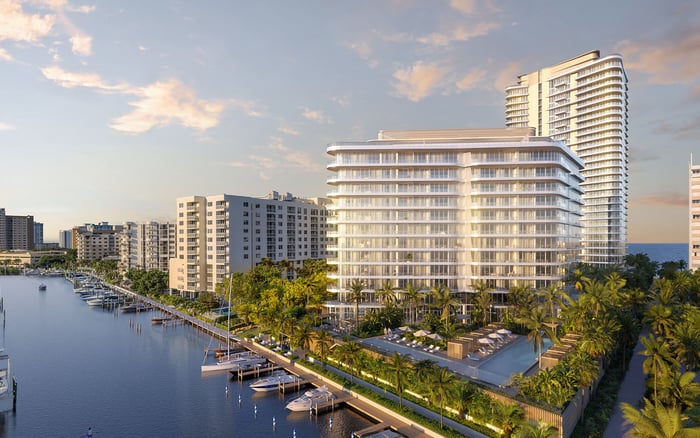
Apply the same framework when reviewing Waldorf Astoria Residences Pompano Beach: one column for confirmed obligations, another for estimates awaiting quotes, and a separate schedule for one-time spending and assessments.
For every line, record the amount, due date, supporting document, and next review point. Distinguish a monthly planning allocation from the date a bill is actually payable. Leave unresolved charges visibly provisional rather than treating them as zero.
Do not finalize the first-year total until taxes, owner insurance, services, furnishing, and assessment exposure are resolved. Financial clarity is part of a well-planned primary residence: it lets you organize the move around living well rather than correcting assumptions.
Explore your Pompano Beach residential options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationThe disclosed dues are $2,063 monthly, equivalent to $24,756 for 12 months at an unchanged rate. Separate assessments and charges are excluded.
The disclosed fees range from $704 to $1,342 monthly, or $8,448 to $16,104 over 12 months at unchanged rates. These are building-specific examples, not a luxury-market benchmark.
Internet is explicitly included in its disclosed association fees. That does not establish that all utilities, insurance components, or optional services are included.
No. Its period and assessment basis are not established, so a buyer-specific property-tax estimate is needed.
No. The property must become the owner's permanent residence for the relevant tax year, and the new owner must apply for a new Homestead Exemption.
No. Florida portability concerns an eligible Save Our Homes assessment difference from a prior Florida homestead, not a Boston property.
Eligible owners need a separate portability application in addition to the new homestead application. The applicable window requires homestead on the new Florida residence within three tax years of selling or abandoning the previous homestead.
The timely deadline was March 2, 2026, and the late-filing deadline was September 18, 2026. Both had passed by October 2, 2026, so confirm the applicable filing year before budgeting a benefit.
Use a residence-specific quote reviewed alongside the association's master policy and enter its actual payment schedule. Keep deductible exposure separate from the premium.
Use written building or vendor quotes rather than generic allowances. Track ongoing services as recurring expenses and furnishing through its separate deposit, progress-payment, and final-balance schedule where applicable.