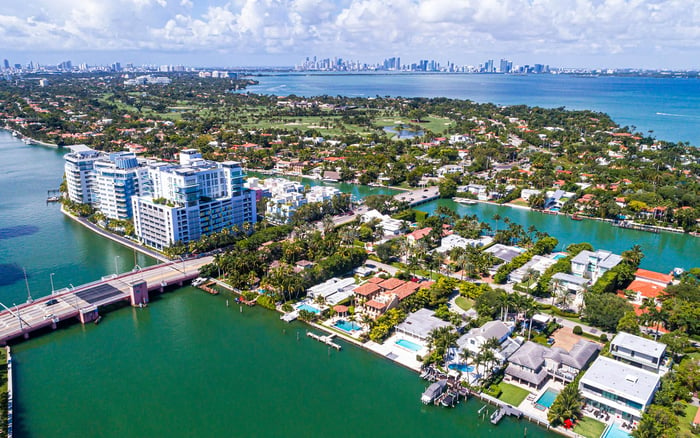
A shared South Florida residence deserves an ownership plan as considered as its interiors. Siblings should align title, funding, family access, and expense responsibilities before the first seasonal stay.
A seasonal residence shared by siblings promises something rare: a familiar address where family traditions can continue without every visit becoming a negotiation. Preserving that ease means separating four questions: who owns the property, who funds it, who may use it, and who decides when circumstances change.
For a family considering Miami Beach, including The Perigon Miami Beach, these questions belong alongside the purchase budget. A beautiful residence cannot resolve an ambiguous family arrangement. The deed, financing documents, association requirements, and a carefully drafted co-ownership agreement should be reviewed together-not treated as interchangeable protections.
The operating provisions below are proposals for a family agreement, not statutory requirements or automatic allocations of liability. Florida counsel should tailor them to the ownership structure and property.
Tenancy in common gives siblings separate fractional interests that may be unequal. Those interests generally pass through each owner's estate rather than automatically to the other owners. Joint tenancy with right of survivorship can instead transfer a deceased sibling's interest automatically to surviving co-owners.
Neither choice should rest solely on the siblings' intention to contribute equally. Decide whether a deceased owner's share should remain with the surviving siblings or pass through that owner's estate. Then have counsel align the deed with those intentions.
If the property becomes a sibling's homestead, Florida's spousal and inheritance restrictions require separate consideration. Homestead property-tax eligibility, creditor protection, and restrictions on transfer or inheritance are distinct issues. Resolving one should not be assumed to resolve all three.
Before closing, document each sibling's proposed contribution to the purchase, closing expenses, furnishings, and initial operating reserve. If contributions differ, specify whether the intended arrangement is unequal ownership, a documented advance, or another structure for counsel to evaluate. Do not leave the treatment of extra contributions to memory.
If financing is contemplated, ask the lender and counsel who will sign each document, what obligations each signer assumes, and whether the intended title structure is acceptable. A private expense-sharing formula does not confirm a lender's requirements.
A useful proposed budget separates fixed carrying costs from stay-specific spending. The family might allocate agreed recurring costs by ownership percentage while assigning personal services or additional cleaning to the sibling requesting them. These are contractual choices, not automatic legal rules.
For a Brickell purchase such as The Residences at 1428 Brickell, test the budget against the property's actual documents. Set contribution dates, spending authority, repair-approval thresholds, and a process for replenishing the family's reserve.
A workable calendar establishes priority before anyone books travel. Consider an annual request deadline, rotating holiday priority, a maximum advance-booking window, and a clear method for resolving overlapping requests.
Specify whether siblings receive equal time or another agreed allocation. Ownership percentage and vacation time need not be the same negotiating question; counsel should document the family's chosen arrangement. Decide whether a sibling can transfer dates to another sibling and when unused reservations return to the shared calendar.
Cancellation rules should distinguish an early release from a last-minute change. Maintenance blackouts also need protected time on the calendar. Assign one calendar administrator, but define the role as administrative-not an unrestricted power to approve or refuse another owner's visits.
Decide whether guests may stay without the inviting sibling present, whose allocation their visit uses, and who handles arrival instructions and departure checks. Propose occupancy limits and procedures for celebrations, then reconcile them with the property's governing requirements.
Condominium declarations, bylaws, and applicable rules govern owners and guests. Family permission cannot override association restrictions. A Surfside buyer considering Ocean House Surfside should therefore review the actual guest and access provisions rather than infer permissions from the residence's presentation.
Staff access warrants a separate protocol. Identify authorized housekeepers, maintenance providers, and other vendors; establish key or credential controls; and specify how scheduled entry is communicated to the occupying sibling. Define emergency-access procedures and a process for withdrawing credentials when a working relationship ends. These are proposed operating safeguards, subject to applicable building requirements.
The agreement should distinguish ordinary wear, accidental incidents, and alleged guest- or vendor-related damage. Consider prompt incident notification, photographs, an inventory of significant furnishings, and a shared repair record. Documentation supports a fair discussion without predetermining fault.
Agree on who may authorize urgent protective work and which nonurgent repairs require joint approval. Ask counsel to draft any proposed allocation of repair costs, deductibles, or uninsured losses, including a process for resolving disputed responsibility.
Do not assume that inviting a guest automatically establishes a sibling's legal liability or that a family agreement determines insurance coverage. Review the relevant policy terms separately. A practical agreement should also address how necessary work is funded while reimbursement remains disputed.
A condominium owner generally cannot avoid the unit's share of common expenses by leaving it vacant or declining to use common elements. A valid special assessment is not optional simply because one sibling objects or visits less often.
For families evaluating Fort Lauderdale, including Four Seasons Hotel & Private Residences Fort Lauderdale, due diligence should cover governing documents, budgets, financial statements, assessment information, insurance records, and available inspection documentation. Review reserve funding, applicable structural-inspection requirements, and pending assessments before estimating carrying costs.
Within the family agreement, propose an assessment-sharing formula, payment deadlines, and a mechanism for addressing missed contributions. Association powers to suspend certain amenities for violations or delinquency are subject to statutory requirements and exceptions. They should never be treated as authority for one sibling to lock out another.
Seasonal visits alone do not satisfy Florida's permanent-residence requirement for the homestead property-tax exemption. Eligibility generally depends on ownership and permanent residence as of January 1, with an application to the county property appraiser. Apportionment may apply among qualifying resident co-owners according to their interests.
If one sibling moves in permanently, revisit the tax analysis, family calendar, and cost allocation with advisers. Before purchase, also ask counsel to address a future sale request, valuation disagreements, and deadlocked decisions. An annual review can keep the written arrangement aligned with family life.
For a considered approach to your next South Florida residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationTenancy in common allows separate fractional interests that can be unequal. Counsel should document the intended ownership shares and treatment of differing contributions.
A tenancy-in-common interest generally passes through the owner's estate, while joint tenancy with right of survivorship can transfer it automatically to surviving co-owners. Homestead-related spousal and inheritance restrictions may require separate analysis.
Seasonal visits alone do not satisfy the permanent-residence requirement. Eligibility generally depends on ownership and permanent residence as of January 1, followed by an application to the county property appraiser.
The family should expressly negotiate its preferred allocation rather than assume a formula. Calendar provisions are proposed contractual arrangements, not statutory booking rules.
The family agreement should address that permission, but condominium governing documents and applicable rules must also be followed. Family approval cannot override association restrictions.
Consider written procedures identifying authorized vendors, controlling credentials, communicating scheduled entry, and handling emergencies. Reconcile those procedures with applicable building requirements.
Responsibility should be evaluated under the circumstances and any applicable agreement, rather than assumed from the invitation alone. Counsel can draft proposed cost-allocation terms, while insurance coverage requires separate review.
Low usage does not make a valid condominium special assessment optional or excuse the unit's common expenses. The family should separately document how siblings share those costs internally.
Association amenity-suspension powers should not be treated as authority for a sibling to lock out a co-owner. Have counsel structure lawful procedures for missed contributions and disputes.
Review the declaration, bylaws, rules, budgets, financial statements, assessment information, insurance records, and available inspection documentation. Reserve funding, applicable structural-inspection requirements, and pending assessments also matter to the budget.