An Edgewater residence strategy begins with qualifying ownership and permanent residence, not an assumed tax benefit. Understand the January 1 eligibility date, the limits of Florida portability, and the deed decisions to resolve before closing.
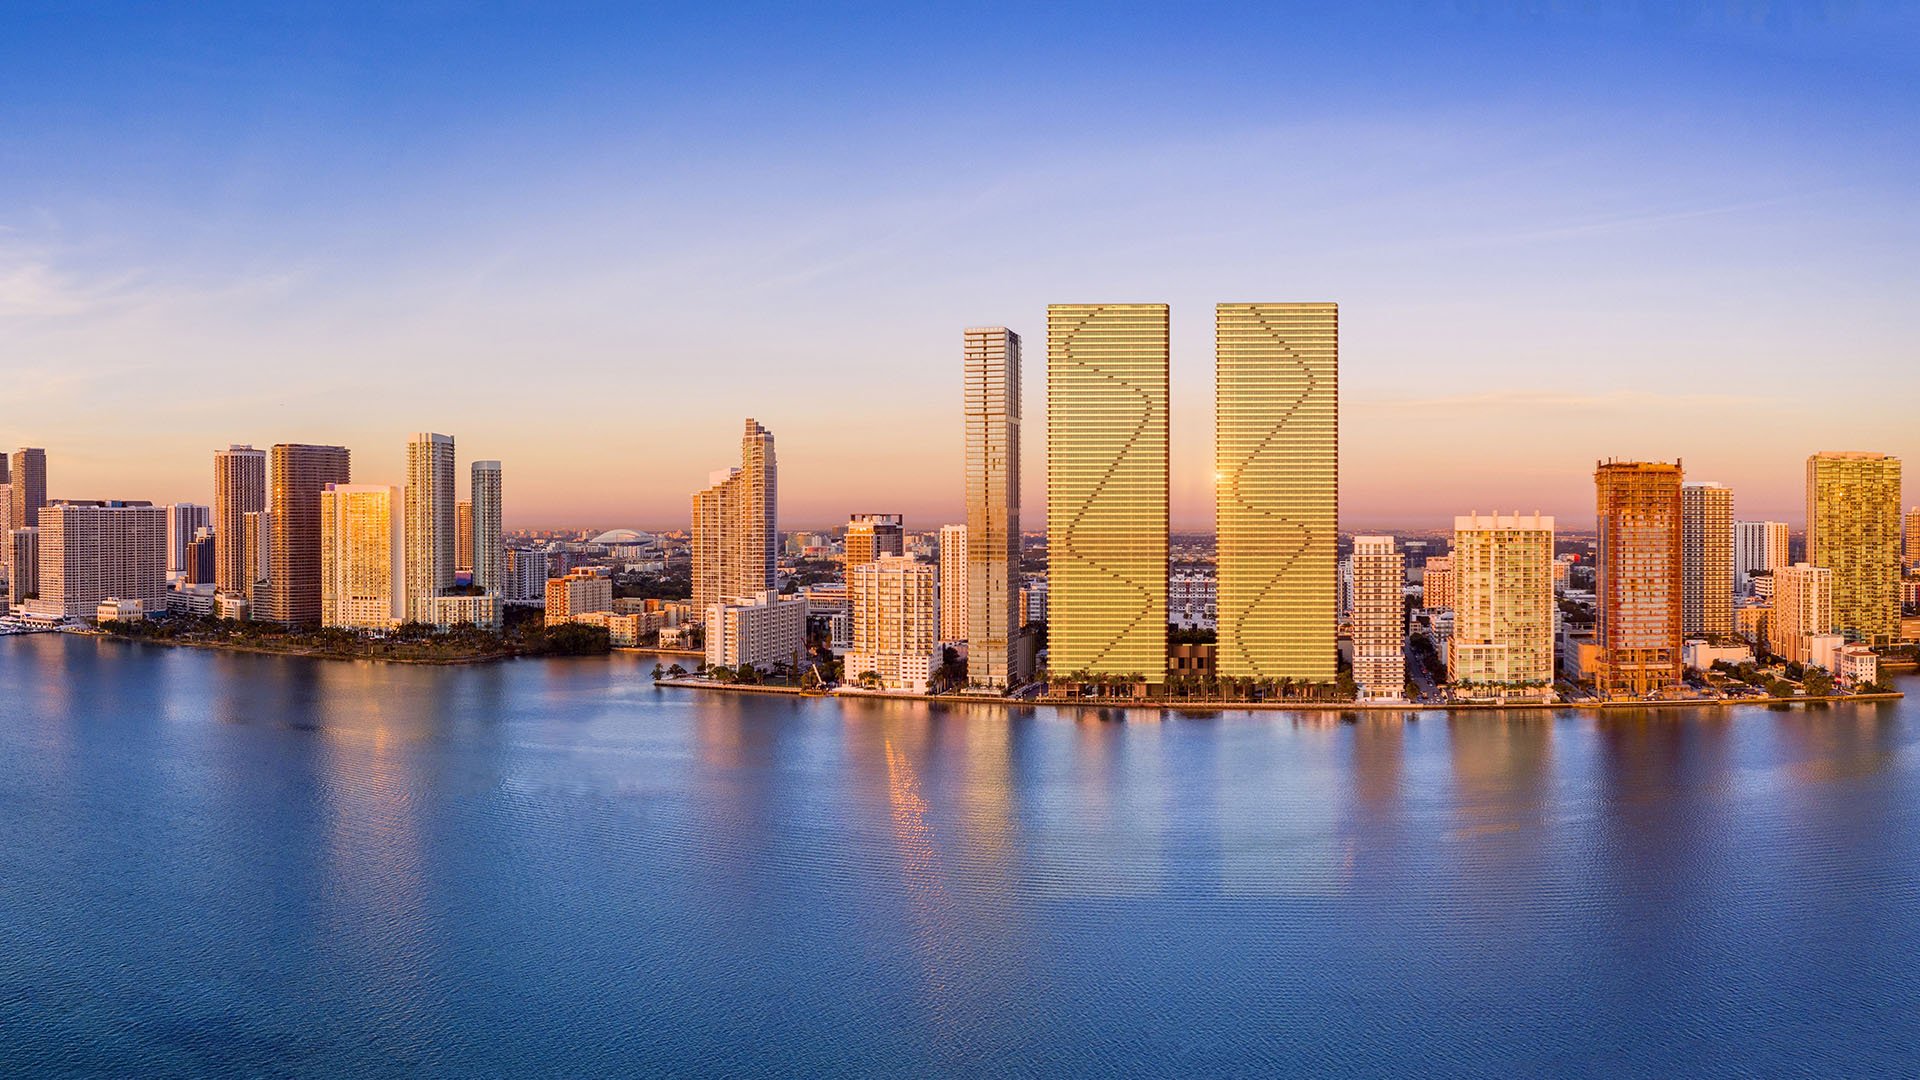
An Edgewater acquisition can be both a lifestyle decision and a carefully structured move of permanent residence. The distinction matters: choosing the apartment, establishing homestead eligibility, and preserving an existing assessment benefit are separate decisions. Coordinate them before closing, rather than reconstructing them when the first tax bill arrives.
The phrase “from Milan” requires one essential distinction. If it means Milan, Italy, that residence cannot supply a Florida Save Our Homes portability benefit. Portability requires a prior qualifying Florida homestead. If Milan refers to a residence in Florida, confirm its actual homestead status rather than inferring eligibility from its name or the owner's occupancy.
For a buyer considering Aria Reserve Miami, the starting point is the former property's record. Obtain its market value, assessed value, and homestead status to establish whether there is a potentially transferable assessment difference to investigate. Without a qualifying former Florida homestead, evaluate the Edgewater purchase for its own exemption eligibility, without assuming portability.
Florida property-tax homestead eligibility generally requires legal or beneficial ownership and use of the property as the owner's, or a dependent's, permanent residence as of January 1. Occupancy alone does not satisfy every requirement. The deed and any related trust documents belong in the planning discussion before signing, not simply in the closing archive.
Individual ownership, beneficial ownership through a trust, and ownership through a business entity are not interchangeable. The practical question is whether the proposed applicant holds the qualifying ownership interest required for the tax exemption.
A revocable trust does not necessarily defeat Florida homestead protection. Beneficial ownership and the trust's terms matter, however, and that principle is not blanket approval for property-tax exemption eligibility. Have counsel examine the actual documents and the intended applicant's rights.
Corporate or partnership ownership is materially different from individual or beneficial ownership. Before placing a primary residence in a business entity, obtain legal review specific to the proposed structure. Property-tax exemption, portability, creditor protection, and restrictions on transfer are related but distinct subjects. Advice about one should not be assumed to resolve the others.
For a purchase after January 1, the usual planning target is qualifying ownership and permanent residence by the following January 1, followed by filing by March 1 of that qualifying year. A purchase agreement or an intention to relocate does not substitute for meeting the ownership and permanent-residence requirements.
For someone evaluating EDITION Edgewater, that means separating the acquisition timetable from the eligibility timetable. Do not assume the purchase year will also be the first year of the buyer's own homestead exemption.
Residency evidence can include a Florida driver license, vehicle registration, voter registration, and other records supporting the permanent address. Treat these as evidence of the actual residence arrangement, not a checklist that independently guarantees approval.
The application also asks about residency-based exemptions claimed elsewhere by the applicant or spouse. Review the household's existing claims and address records together. The ownership documents, actual use, and household declarations should tell a consistent story.
The homestead exemption itself does not transfer when an owner moves. The new residence requires its own application. Portability concerns an eligible homestead assessment difference: the gap between the former property's market value and assessed value.
The maximum transferable difference is $500,000. That is an assessed-value benefit-not $500,000 in tax savings, a reduction in the purchase price, or a reduction in market value. Eligibility may allow transfer of all or only part of the former difference. The ceiling is not a promised deduction.
Portability can apply between qualifying Florida homesteads within one county or across Florida counties. The new homestead generally must be established within three assessment years after abandonment of the former homestead. Because the window is measured through consecutive January 1 dates, have the relevant dates checked rather than treating it as an informal three-year moving allowance.
Save Our Homes is distinct from portability. Beginning in the second year of homestead exemption, it generally limits annual assessed-value increases to the lesser of 3% or the applicable CPI change, subject to exceptions such as new construction. It limits assessment growth under the applicable rules; it does not promise that the total tax bill will rise by no more than 3%.
A seller's current tax bill can be an appealing but misleading reference point. A buyer purchasing after January 1 may temporarily benefit from the seller's exemption and assessment limitation during the purchase year. Those seller benefits are removed the following year.
For a prospective purchase at Villa Miami, build the carrying-cost analysis around the buyer's expected post-purchase assessment and eligible benefits-not an assumption that another owner's assessed value survives the transfer.
Keep three items separate in the financial model: the anticipated post-purchase assessment, the buyer's own homestead eligibility, and any portability amount that may be approved. Until the benefit is confirmed, compare a scenario without portability against one with an estimated eligible transfer. This avoids treating a conditional benefit as committed savings.
The ordinary filing deadline is March 1 of the qualifying tax year. Form DR-501 is the homestead application. An owner seeking portability must also request it through Form DR-501T. Filing for the new exemption alone does not automatically request portability.
Prepare the former property's valuation and homestead information alongside the new residence's ownership and residency records. Where deed terms or beneficial ownership require interpretation, resolve those questions with counsel before relying on a projected exemption.
After the applications are reviewed, verify the approved exemption, assessed value, and portability benefit against the planning assumptions. The household budget should reflect the approved treatment of the new property, not the maximum benefit that might have been available in principle.
The sequence is straightforward: confirm the former homestead, review the deed structure, establish permanent residence, file the applicable applications, and verify the approved assessment. Each step answers a different question. The appeal of the residence itself is no substitute for completing them.
For a considered approach to your next Edgewater residence, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Portability applies between qualifying Florida homesteads, so a residence in Italy cannot supply the assessment difference.
The applicant generally needs qualifying legal or beneficial ownership and use of the property as the owner's or a dependent's permanent residence as of January 1.
The usual target is qualifying ownership and permanent residence by the next January 1, followed by filing by March 1 of that qualifying year.
Evidence can include a Florida driver license, vehicle registration, voter registration, and other records supporting the permanent address. Applications also ask about residency-based exemptions claimed elsewhere by the applicant or spouse.
No. The new property requires its own homestead application, and portability requires a separate request.
No. It is the maximum transferable assessment difference, not a dollar-for-dollar tax saving, and eligibility may allow only part of the former difference to transfer.
The new homestead generally must be established within three assessment years after abandonment of the former homestead. Check the applicable consecutive January 1 dates rather than assuming a rolling three-year period.
Form DR-501 requests the new homestead exemption, while Form DR-501T requests portability. The ordinary filing deadline is March 1 of the qualifying tax year.
A revocable trust does not necessarily defeat Florida homestead protection, but beneficial ownership and trust terms matter. Tax-exemption eligibility requires specific review rather than reliance on general asset-protection principles.
The seller's exemption and assessment limitation may temporarily benefit the purchase year but are removed the following year. Buyers should model their own post-purchase assessment and eligible benefits.