A founder’s home-buying budget should begin with released, usable capital, not a company’s headline sale price. Separate tax exposure, escrow, deferred consideration, and Florida homestead benefits before committing to a South Florida residence.
A company sale and a South Florida home purchase can belong to the same life chapter without sharing a financial timetable. The headline consideration is not a founder’s personal net worth, and neither figure establishes how much cash is available for a residence. The useful starting point is narrower: what capital has been released, what obligations remain against it, and how much can comfortably be committed to the home?
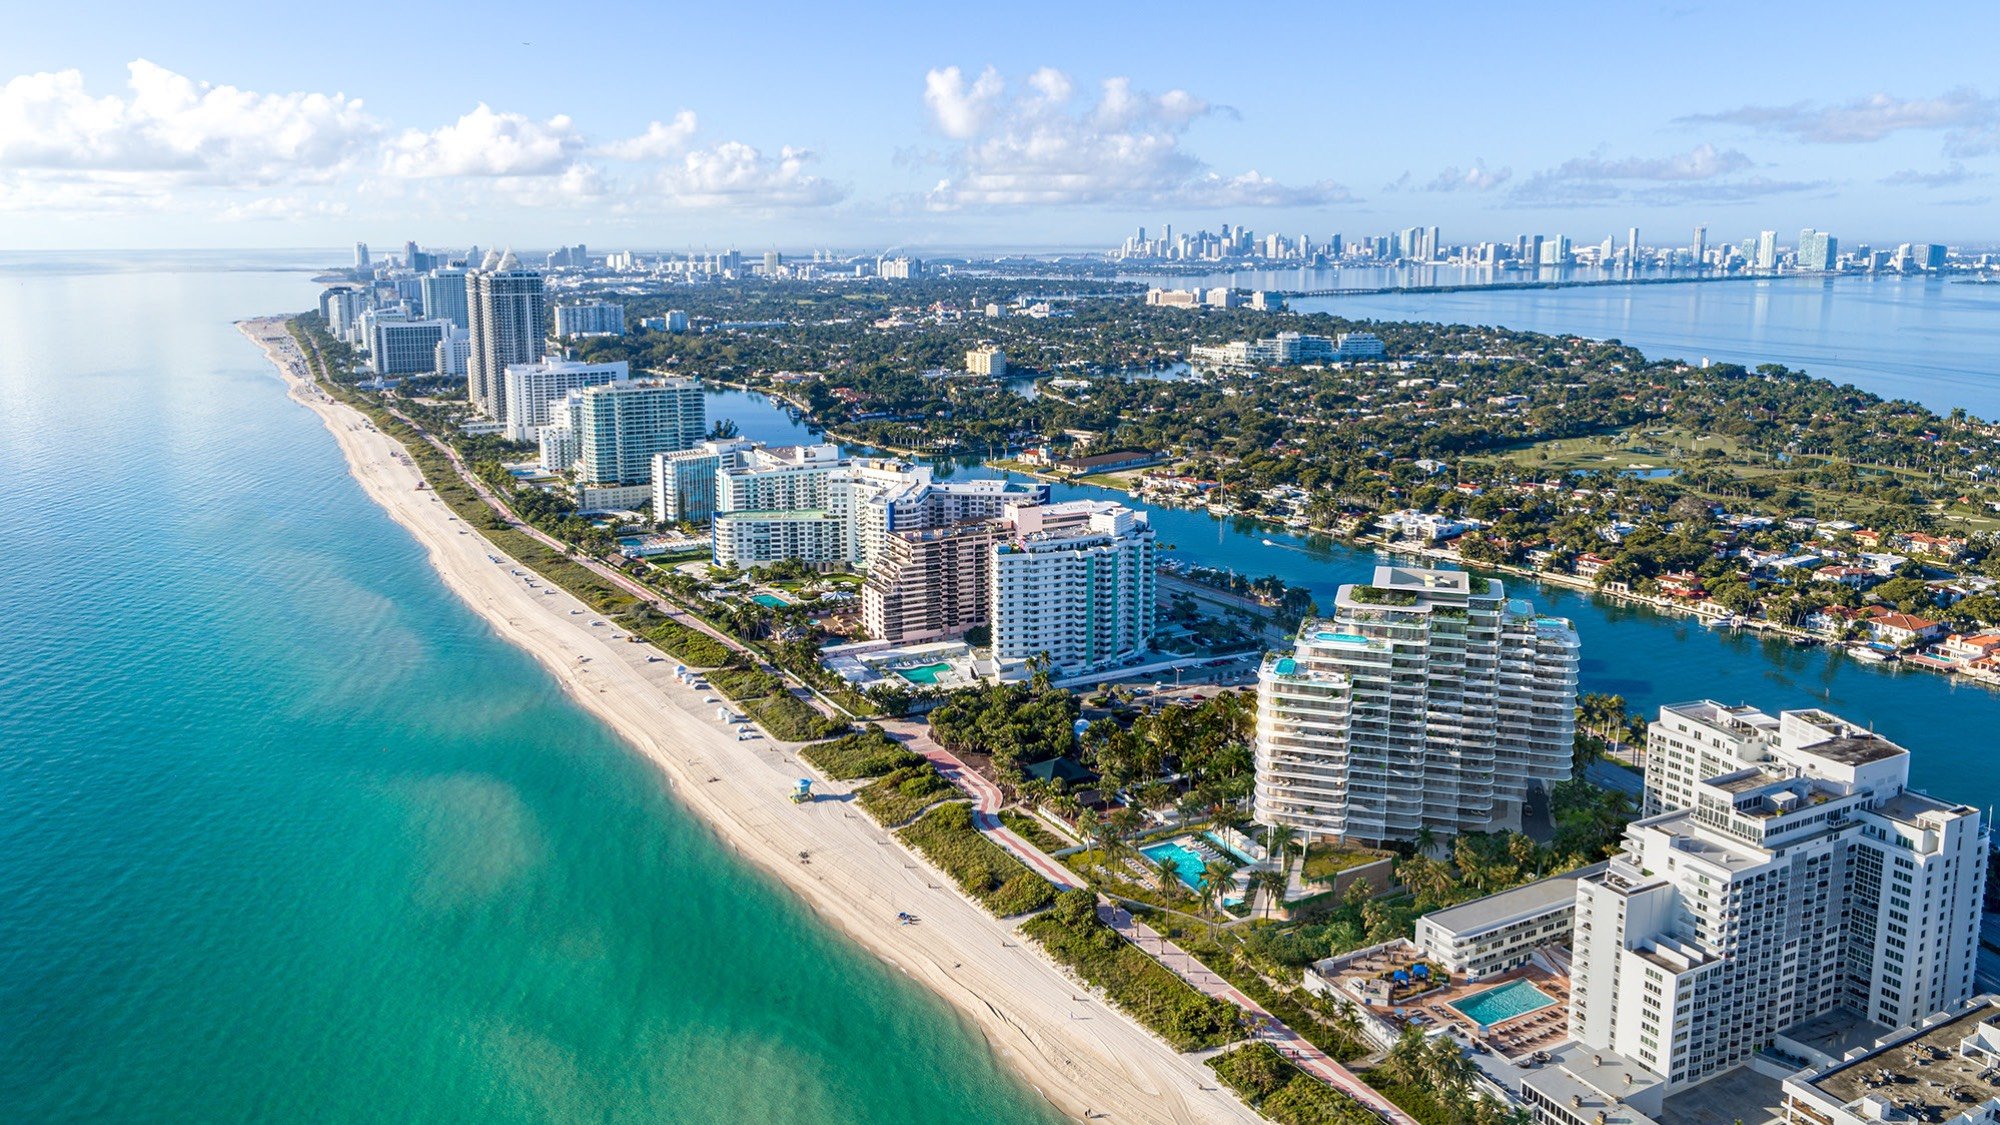
That distinction deserves attention before the architectural shortlist. Whether the search centers on Brickell or Miami Beach, purchasing confidence should rest on documented liquidity rather than an assumed share of an announced transaction. A compelling residence does not resolve uncertainty about the funds intended to purchase it.
Ask the transaction team to prepare a sources-and-uses schedule that traces the money from gross consideration to personal purchasing capacity. It should distinguish ownership allocation, debt and fees, estimated taxes, cash released, escrow, deferred consideration, and rollover equity. Each category answers a different question; combining them into one wealth figure obscures the purchase decision.
For home-budget purposes, request three separate views: money available now, money potentially available later, and value that is not currently cash. These are planning categories, not tax classifications. Their purpose is to keep a future entitlement or retained investment from quietly entering today’s deposit budget.
A buyer considering The Residences at 1428 Brickell should bring the same distinction to the financial brief. Before setting a spending ceiling, identify the amount available after an adviser-reviewed tax reserve and other planned commitments. Evaluate the residence against that usable budget, not a headline valuation.
An escrow balance warrants its own line in the purchase plan. Request transaction-specific confirmation of the amount held, anticipated release date, release conditions, and dispute provisions. A date alone does not establish whether the full balance will become available as expected.
Ask counsel to distinguish a scheduled release from an unconditional entitlement. Then test the home purchase without assuming that escrow funds arrive on the preferred date. If the purchase depends on those funds, make that dependency explicit rather than burying it in a general statement of wealth.
The same discipline applies when reviewing The Perigon Miami Beach. Evaluate the contemplated purchase commitments against confirmed liquidity. Do not assume a particular residence’s payment terms; obtain the actual contract schedule and compare it with the documented release conditions governing the sale proceeds.
Sale price alone does not establish taxable gain. Basis, selling expenses, and applicable tax rules affect the calculation. A simple percentage applied to gross consideration is therefore no substitute for transaction-specific tax advice when setting a home budget.
An installment sale generally involves receiving at least one payment after the tax year in which the sale occurs. For a qualifying transaction, the installment method generally allows gain to be recognized as payments are received. A seller may, however, elect out and recognize gain in the year of sale even when some payments arrive later.
Further distinctions matter. Depreciation recapture can affect the timing and character of taxable gain, so deferred payments do not necessarily defer all associated tax. Nor do installment-sale rules establish blanket treatment for every escrow, earn-out, or deferred-payment arrangement.
Commission two coordinated schedules: one showing when funds may become available, the other showing expected tax obligations under the transaction’s actual treatment. Ask the tax adviser to reconcile them before treating a future payment as either fully spendable or fully reserved. Neither calendar should be inferred from the other.
Once the schedules are reconciled, distinguish the maximum purchase price from the amount you are prepared to commit now. Consider acquisition costs, planned improvements or furnishings, ongoing ownership spending, and the liquidity you wish to retain. These are budgeting decisions to document, not amounts to assume from the exit value.
For a Coconut Grove search that includes Four Seasons Residences Coconut Grove, keep the property comparison connected to the funding review. Ask the advisory team to map each proposed contractual payment to an identified source of funds. Where a payment depends on a future release, show that dependency plainly.
A useful stress test is whether the purchase remains comfortable if conditional proceeds arrive later than hoped or are not released in full. This is not a prediction about the transaction. It distinguishes a purchase supported by existing liquidity from one supported by expectations.
Florida property-tax planning belongs in the ownership analysis, but it is not purchase funding. An eligible permanent residence may qualify for a homestead exemption that reduces taxable value. The Save Our Homes assessment limitation can also restrict annual increases in assessed value for qualifying homesteaded property.
Eligible homeowners may transfer some or all of their accumulated Save Our Homes assessment benefit to another qualifying Florida homestead. The portable benefit represents the difference between the previous homestead’s market and assessed values, transferable up to $500,000. Portability generally requires establishing the new homestead within three assessment years after abandoning the previous one.
That benefit reduces the assessment used for property-tax purposes. It is not cash, additional sale proceeds, or a dollar-for-dollar credit toward the residence. It belongs in the ownership budget, subject to eligibility and the applicable calculation.
For a West Palm Beach search including Alba West Palm Beach, review permanent-residence plans and potential portability separately from acquisition funding. Do not assume that selecting a Florida address automatically establishes eligibility for either benefit.
Before committing, bring the transaction attorney, tax adviser, and home-purchase team back to a single question: which funds are available for this purchase, on which dates, and after which obligations? Keep conditional proceeds and property-tax benefits visible, but outside the confirmed-cash figure unless their treatment has been established.
The goal is not to diminish what a founder has built. It is to ensure that the next residence is supported by capital whose availability is understood, allowing the home to serve its intended purpose rather than become a deadline for an unresolved transaction.
Explore South Florida residences with MILLION through a search grounded in your confirmed purchasing capacity.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. The budget should reflect the founder’s ownership allocation, transaction obligations, estimated taxes, and cash actually available for the purchase.
It should distinguish gross consideration, ownership allocation, debt and fees, estimated taxes, cash released, escrow, deferred consideration, and rollover equity.
Do not assume it is available. Review the holdback amount, release date, release conditions, and dispute provisions before relying on it for a home purchase.
No. Basis, selling expenses, and applicable tax rules affect taxable gain.
An installment sale generally involves receiving at least one payment after the tax year in which the sale occurs. Qualifying transactions generally permit gain to be reported as payments are received.
Yes. A seller may elect out of installment reporting and recognize gain in the year of sale even if some payments arrive later.
No. Depreciation recapture can affect the timing and character of taxable gain, and installment rules do not establish blanket treatment for every deferred arrangement.
An eligible permanent residence may qualify for an exemption that reduces taxable value. The Save Our Homes assessment limitation can restrict annual assessed-value increases on qualifying property.
Eligible homeowners may transfer some or all of their accumulated assessment benefit, up to $500,000. Portability generally requires establishing the new homestead within three assessment years after abandoning the previous one.
No. Portability reduces the assessment used for property-tax purposes; it is not a cash payment or additional sale proceeds.