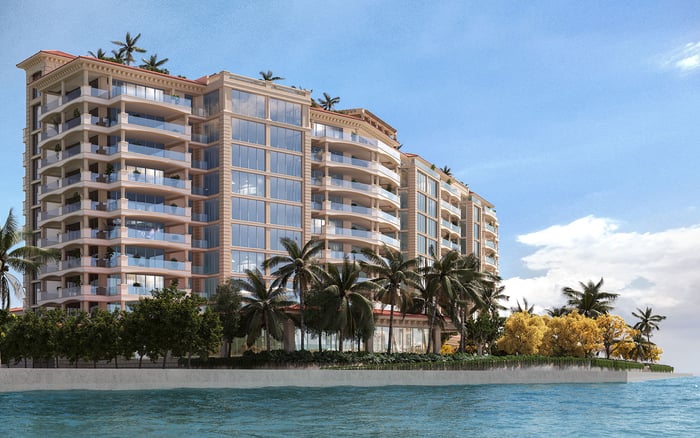
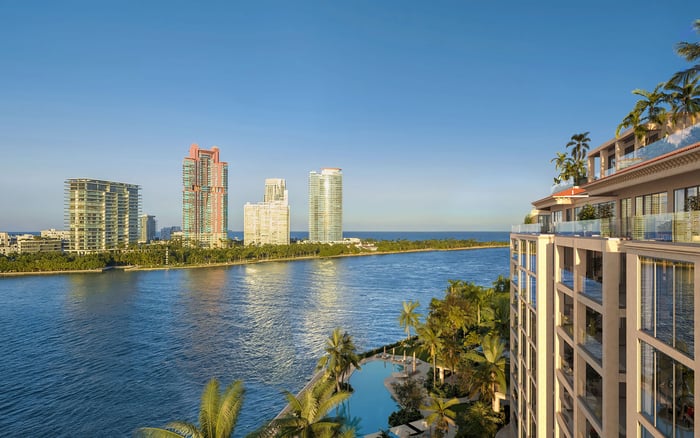
A Fisher Island residence needs an operating plan as considered as its interiors. For Silicon Valley buyers, that means coordinating staff transitions, federal and Florida payroll obligations, property-specific vendor access, and any eligible Florida homestead portability before arrival.
Establishing a Fisher Island base from Silicon Valley is more than a property transaction. It creates a second operating environment for a household whose standards, routines, and expectations may already be finely calibrated. The purchase secures the setting; staff continuity, payroll administration, and vendor coordination determine how comfortably the residence functions.
For a buyer considering Palazzo del Sol Fisher Island, the question is not simply who will prepare the residence, but who will direct the work, authorize spending, maintain records, and resolve exceptions. Assign those responsibilities before the first extended stay. A beautifully prepared home should not depend on improvised arrangements behind the scenes.
Start with three parallel workstreams: people, payroll, and property operations. Name a coordinator for each, then establish a shared arrival calendar. Treat the following steps as a planning framework, not as official Fisher Island or building requirements.
Before asking existing staff to relocate or support a Florida stay, define the household's intended pattern of use. A seasonal base, recurring short visits, and an extended residence can call for different staffing arrangements. Record anticipated dates, duties, reporting relationships, and any periods when California and Florida operations will overlap.
For each role, decide whether continuity is essential, local recruitment is preferable, or an independent service business might be appropriate. Consider who holds practical knowledge of the household, who can maintain it remotely, and who must be physically present. Discuss proposed changes with affected staff before treating the transition as settled.
Separate operational preference from worker classification. Household-worker status depends on the actual working relationship and the employer's control-not merely on an invoice or a contract describing someone as a vendor. A familiar staff member does not become an independent contractor simply because payment arrangements change.
Have the proposed arrangements reviewed before implementation, especially where work continues across both states. Document duties, supervision, compensation arrangements, and scheduling responsibility. This article does not establish California-to-Florida employment-law equivalence; the relocation plan should not assume it.
Federal household-employment tax obligations still apply when a household establishes its Florida base. Begin payroll planning with classification and employer responsibilities, rather than assumptions about the new address.
Household employers may be responsible for Social Security and Medicare taxes on employee wages, subject to applicable rules and thresholds. Federal unemployment tax may also apply. These obligations are separate from Florida's reemployment tax; the payroll budget should not combine them into a single state-level allowance.
Federal income-tax withholding is generally voluntary for household employees: the employee must request it, and the employer must agree. Resolve that decision during onboarding rather than leaving the employee to infer what the first payment includes.
Appoint a payroll administrator and establish a recordkeeping routine covering wage reporting, required year-end forms, and employment-tax records. Have the administrator confirm current federal thresholds rather than carry forward figures from an earlier year. Where staff support more than one residence, arrange a review of the employment and payment structure before the first Florida payroll run.
Florida reemployment tax is employer-paid and funds unemployment benefits for eligible claimants. The initial new-employer rate is 2.7% on the first $7,000 of annual wages per employee. That starting rate and wage base do not represent the full cost of household employment.
Florida generally requires wages subject to reemployment tax to be reported each calendar quarter. Domestic-service employers have a distinct annual reporting provision: Florida law permits them to report wages and pay contributions annually, generally by January 31, with adjustments for weekends and holidays.
That provision does not give every employer permission to file annually. Have the payroll administrator confirm whether the household qualifies and which reporting arrangement applies. Add the resulting deadlines to the calendar of federal payroll responsibilities, with one person accountable for completion and another designated to review it.
For a household evaluating The Residences at Six Fisher Island, establish that administrative calendar independently of the purchase timetable. Acquisition, occupancy, and employment obligations are related planning matters, but they are not interchangeable milestones.
Residence-vendor onboarding should begin with questions, not assumptions. Before booking service visits, request current procedures from the relevant property representative. Ask which procedures, if any, apply to access authorization, transport arrangements, delivery scheduling, insurance documentation, and contractor coordination.
These are suggested due-diligence questions, not statements of island-wide requirements. Do not assume that one residence's procedures apply to another, or that a vendor's previous visit establishes continuing authorization.
When considering Palazzo della Luna Fisher Island, make this inquiry part of residence-specific planning. Build a vendor register documenting the service scope, primary contact, proposed visit dates, spending authority, and household coordinator. Keep confirmed property instructions alongside the register so staff and vendors work from the same information.
A limited preparation visit before a major household arrival offers a useful trial, subject to confirmed access arrangements. Review what worked, what required clarification, and who can authorize changes. The objective is a repeatable process, not an elaborate manual that nobody maintains.
A California property's assessed-value history does not qualify for Florida portability. The benefit concerns an eligible homeowner's prior Florida homestead assessment difference-not the transfer of a Silicon Valley assessment into Florida.
Eligible homeowners may transfer up to $500,000 of that prior Florida assessment difference to a new Florida homestead. This is an assessment benefit, not a $500,000 tax credit. Portability is not automatic, and Miami-Dade's application deadline is March 1.
The portability application uses Form DR-501T, filed with the new homestead-exemption application, Form DR-501. Buyers considering The Links Estates at Fisher Island should keep this review separate from staff and vendor onboarding. Establishing a South Florida base does not, by itself, establish eligibility for a particular property-tax benefit.
Before arrival, bring the household coordinator, payroll administrator, and relevant property contact into one readiness review. Confirm staff assignments, payment arrangements, filing responsibilities, vendor schedules, and unresolved access questions. Maintain a short exception list rather than assuming open items will resolve themselves.
The measure of success is continuity: staff understand their roles, vendors know whom to contact, and the owner is not asked to settle routine administrative questions during a stay. Precision behind the scenes allows the residence to feel effortless without confusing discretion with informality.
For a considered approach to establishing your South Florida base, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Classification depends on the actual working relationship and the employer's control, not simply on invoices or contractual labels.
Yes. Establishing a Florida base does not remove federal household-employment tax obligations.
Social Security and Medicare taxes may apply, subject to applicable rules and thresholds. Federal unemployment tax may also apply separately from Florida reemployment tax.
It is generally voluntary. The employee must request withholding and the employer must agree.
The initial rate is 2.7% on the first $7,000 of annual wages per employee. It is not a complete measure of household employment costs.
No. Quarterly reporting is the general rule, while domestic-service employers have a distinct annual reporting provision whose applicability should be confirmed.
Annual reporting and contributions are generally due by January 31. Weekend and holiday adjustments can affect the deadline.
Ask the relevant property representative about applicable access, delivery, transport, insurance, and contractor procedures. These are planning questions, not presumed island-wide requirements.
No. Florida portability concerns an eligible homeowner's prior Florida homestead assessment difference, not a California property's assessment history.
Eligible homeowners may transfer up to $500,000 of a prior Florida homestead assessment difference, not receive a $500,000 tax credit. Miami-Dade identifies March 1 as the application deadline, with Form DR-501T filed alongside Form DR-501.