A disciplined framework for international buyers to separate currency decisions, contractual funding obligations and FIRPTA-related exit liquidity when considering South Florida preconstruction.
For an international purchaser, choosing a South Florida residence and deciding how to fund it are distinct decisions. The first concerns the property’s place in a personal portfolio; the second, the capital available to satisfy the purchase agreement. Currency planning belongs with the latter, not with a prediction about the address’s desirability.
Begin by distinguishing the amount committed to the residence, the currency in which funds are held, and the cash required at each contractual payment point. If conversion is necessary, ask your advisers to evaluate these obligations together rather than treating the purchase price as a complete funding plan.
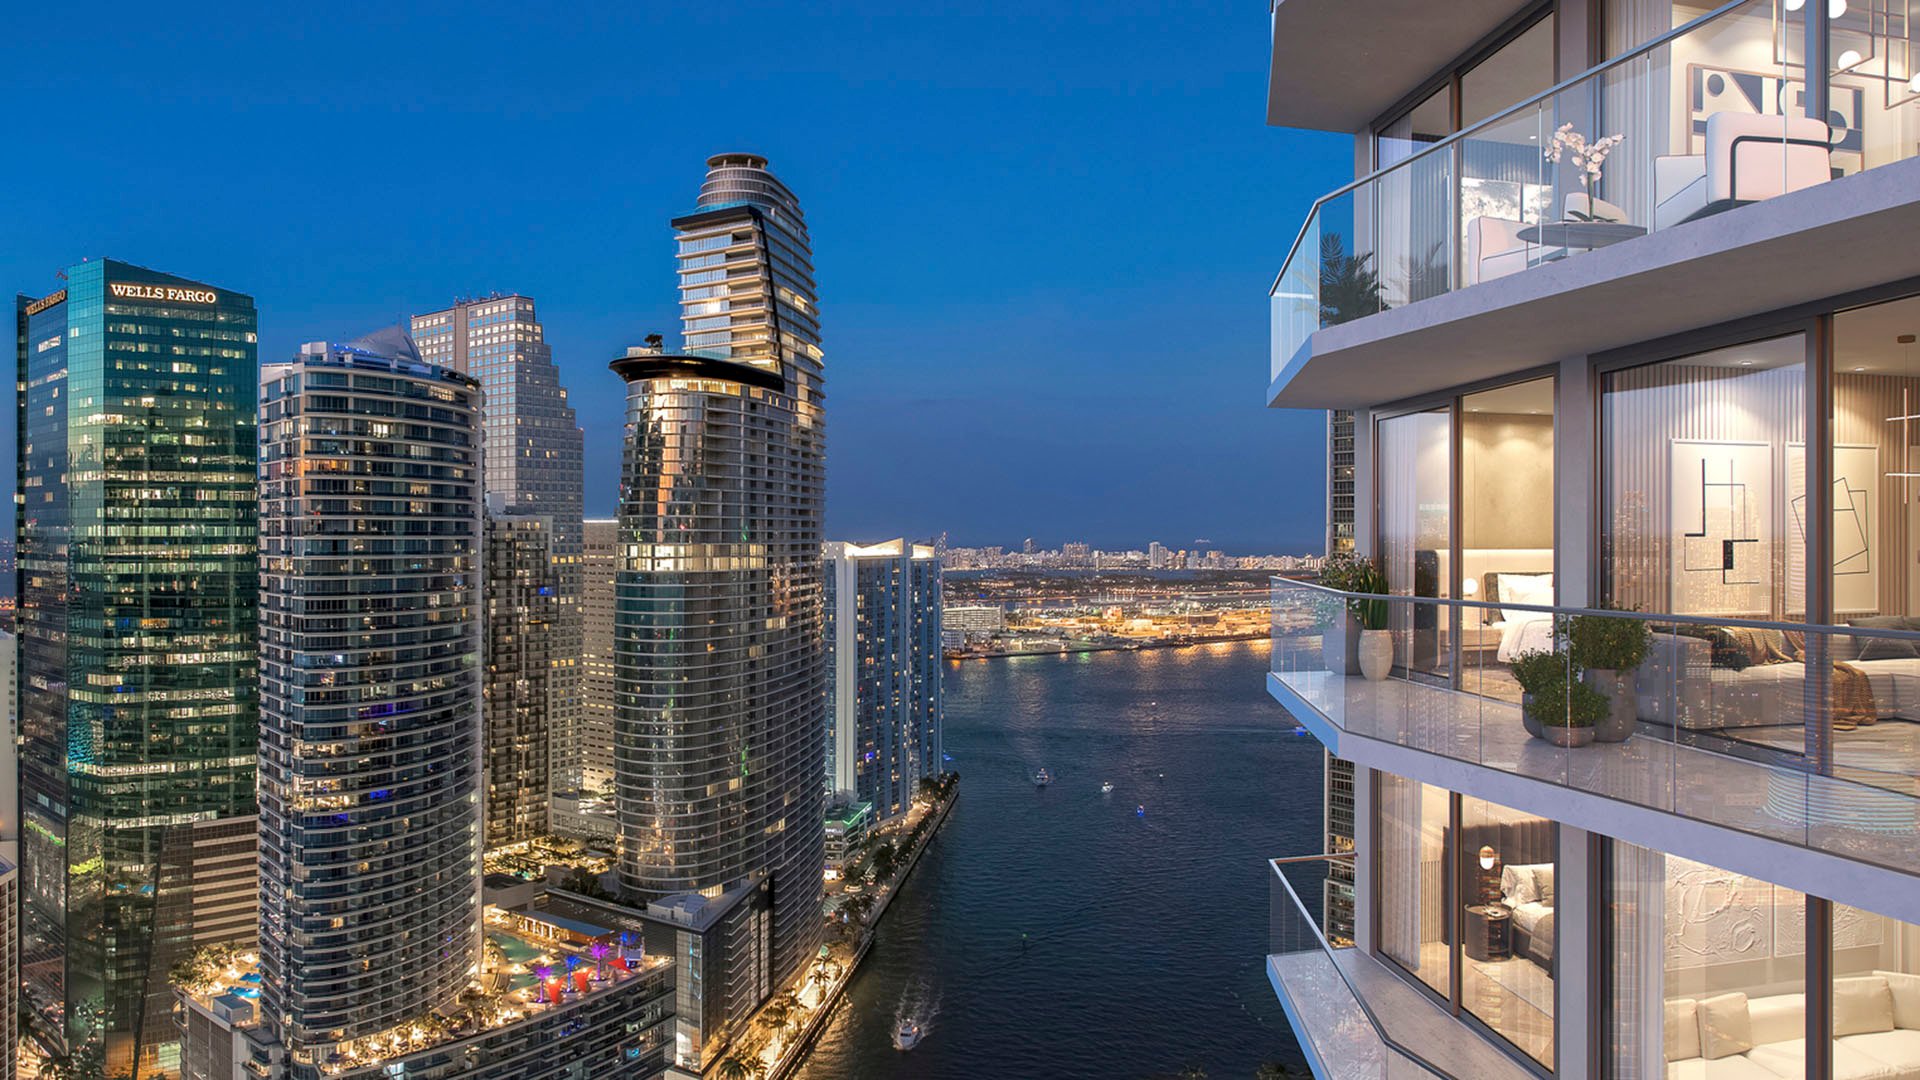
For a buyer considering The Residences at 1428 Brickell, the starting point is the agreement under review. Neither a Brickell address nor a particular project should substitute for a transaction-specific assessment of the buyer’s funding position.
Ask counsel to identify every payment obligation in the proposed agreement, including its amount, currency and due date or contractual trigger. Then ask your financial adviser to map the intended funding against those obligations. The purpose is not to impose a standard deposit schedule, but to establish precisely what this purchase requires.
A useful working document separates money already available for payment from funds that first require conversion. For each obligation, record who will authorize the funding decision and which adviser will confirm the assumptions. Keep contractual requirements distinct from personal preferences about when to exchange funds.
If the agreement changes during negotiations, revisit the funding map before approving the revision. Confirm whether the revised obligation still fits the intended source of capital and the buyer’s broader liquidity priorities.
This exercise should produce clarity, not a market forecast. A buyer should be able to explain how each required payment will be funded without relying on a favorable exchange rate.
Rather than adopting a universal reserve percentage, request a personalized assessment of the proposed commitment. How much home-currency capital are you prepared to allocate? Which funds must remain available for other purposes? What would prompt you to reconsider the funding approach before making a further commitment?
Request comparisons using assumptions selected with your advisers and clearly labeled as illustrations, not predictions. Keep the contractual amount separate from its home-currency equivalent. That distinction clarifies which part of the decision concerns the residence and which concerns conversion.
A purchaser evaluating The Perigon Miami Beach should apply the same discipline. The Miami Beach property decision can remain focused on personal suitability while the funding review addresses the purchaser’s capital constraints.
The goal is not to identify a perfect conversion moment. It is to avoid making the purchase dependent on an assumed exchange-rate outcome.
Before committing, establish who is responsible for each part of the review. Ask legal counsel to interpret the agreement, a financial adviser to assess the proposed funding approach, and a U.S. tax adviser to address transaction-specific tax questions. Do not treat one conversation as a substitute for all three.
Keep a written record of the decisions that matter: the obligations being funded, the assumptions being used and the circumstances that would trigger another review. If an adviser proposes a currency arrangement, request an explanation of its costs, obligations and suitability before deciding whether to proceed.
The same approach applies when considering Alba West Palm Beach. A West Palm Beach purchase deserves its own funding review, not a plan borrowed from another acquisition.
Do not assume a currency decision also resolves the tax position. Funding the acquisition and planning the eventual exit require separate analysis.
FIRPTA applies to dispositions of U.S. real-property interests by foreign persons. For an international purchaser, it deserves attention when planning an eventual resale. It is not an exchange-rate charge, but withholding reduces the cash a foreign seller receives at closing and therefore affects exit liquidity.
The general withholding rate is 15% of the amount realized, subject to exceptions and special rules. Do not apply that percentage automatically to every sale or treat it as a complete calculation of the seller’s tax position. Ask a U.S. tax adviser to determine how the rules apply to the particular transaction.
This distinction matters when discussing future proceeds. A proposed sale price is not the same as cash available to the seller after withholding. Ask advisers to distinguish those figures before considering how much money might subsequently be converted into another currency.
A buyer’s foreign nationality does not itself trigger FIRPTA withholding on an initial purchase from a U.S. developer. The relevant inquiry concerns the seller’s disposition and status, not simply the purchaser’s nationality. Keeping that distinction clear prevents an eventual exit consideration from being mistaken for an automatic acquisition charge.
When assessing FIRPTA obligations, the purchaser must determine whether the seller is a foreign person. The purchaser is generally the withholding agent and can be liable for failing to withhold when required. These responsibilities deserve attention whether you are buying from a foreign seller now or preparing to become the seller later.
Buyers generally use Forms 8288 and 8288-A to report and pay tax withheld on purchases of U.S. real-property interests from foreign sellers. A withholding-certificate application may be used to request reduced or eliminated withholding where applicable. Foreign sellers need taxpayer identification numbers to request reduced withholding and meet applicable FIRPTA requirements.
Coordinate reporting forms, identification requirements and any withholding-certificate application before closing. Do not build an exit funding plan on the assumption that reduced withholding will be available.
A considered purchase plan should answer two distinct questions: how will the contractual obligations be funded, and what must be reviewed before eventual sale proceeds can be treated as available capital?
For the first, use the agreement and your own financial circumstances. For the second, obtain transaction-specific U.S. tax advice rather than treating withholding as the final tax answer. Keep currency assumptions visible in both discussions, but do not confuse them with contractual terms or tax obligations.
For a discreet conversation about South Florida residences and your acquisition priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationBegin with the proposed purchase agreement and identify each payment’s amount, currency and contractual timing. Review the intended funding with your advisers.
Use the actual agreement under review rather than assuming a standard schedule. Ask counsel to identify each payment obligation and any contractual trigger.
The article does not recommend a universal percentage. Ask your advisers to assess the proposed commitment against your funding needs and liquidity priorities.
No. A buyer’s foreign nationality does not itself trigger FIRPTA withholding on an initial purchase from a U.S. developer; the seller’s status and disposition matter.
No. FIRPTA withholding concerns a foreign person’s disposition of U.S. real property, but it affects the seller’s cash available at closing.
The general rate is 15% of the amount realized. Exceptions and special rules mean it should not be applied automatically to every transaction.
The purchaser is generally the withholding agent and must determine whether the seller is a foreign person. The purchaser can be liable for failing to withhold when required.
Buyers generally use Forms 8288 and 8288-A to report and pay tax withheld on purchases of U.S. real-property interests from foreign sellers.
A withholding-certificate application may request reduced or eliminated withholding where applicable. Coordinate taxpayer identification requirements and the application before closing.
No. Obtain transaction-specific U.S. tax advice before resale rather than treating withholding as a complete calculation of the seller’s tax position.