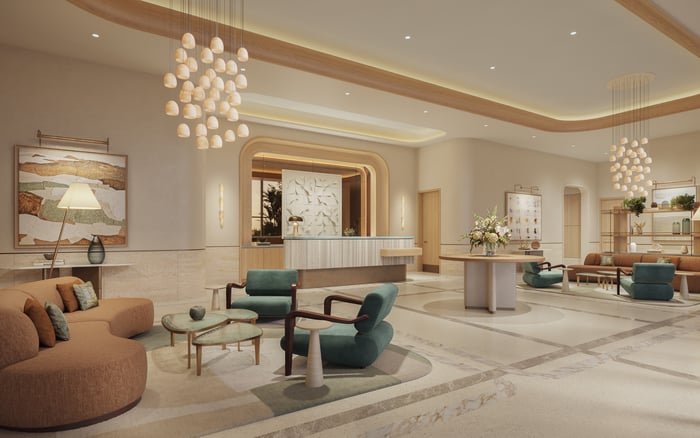
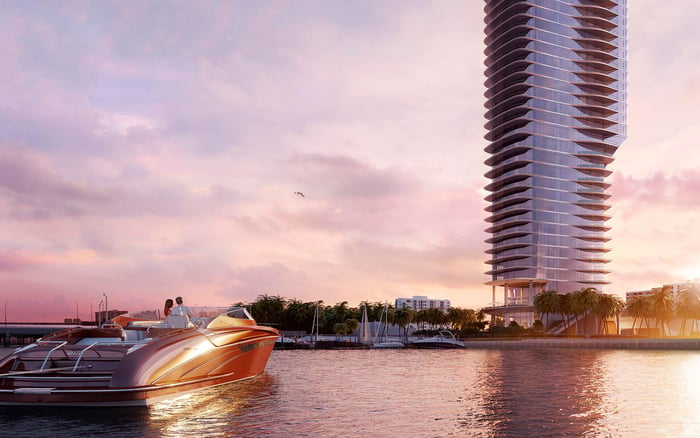
For married buyers establishing a permanent Florida residence, contract review should align closing dates, ownership, residency evidence and trust provisions while keeping tax eligibility, creditor protection and inheritance restrictions distinct.
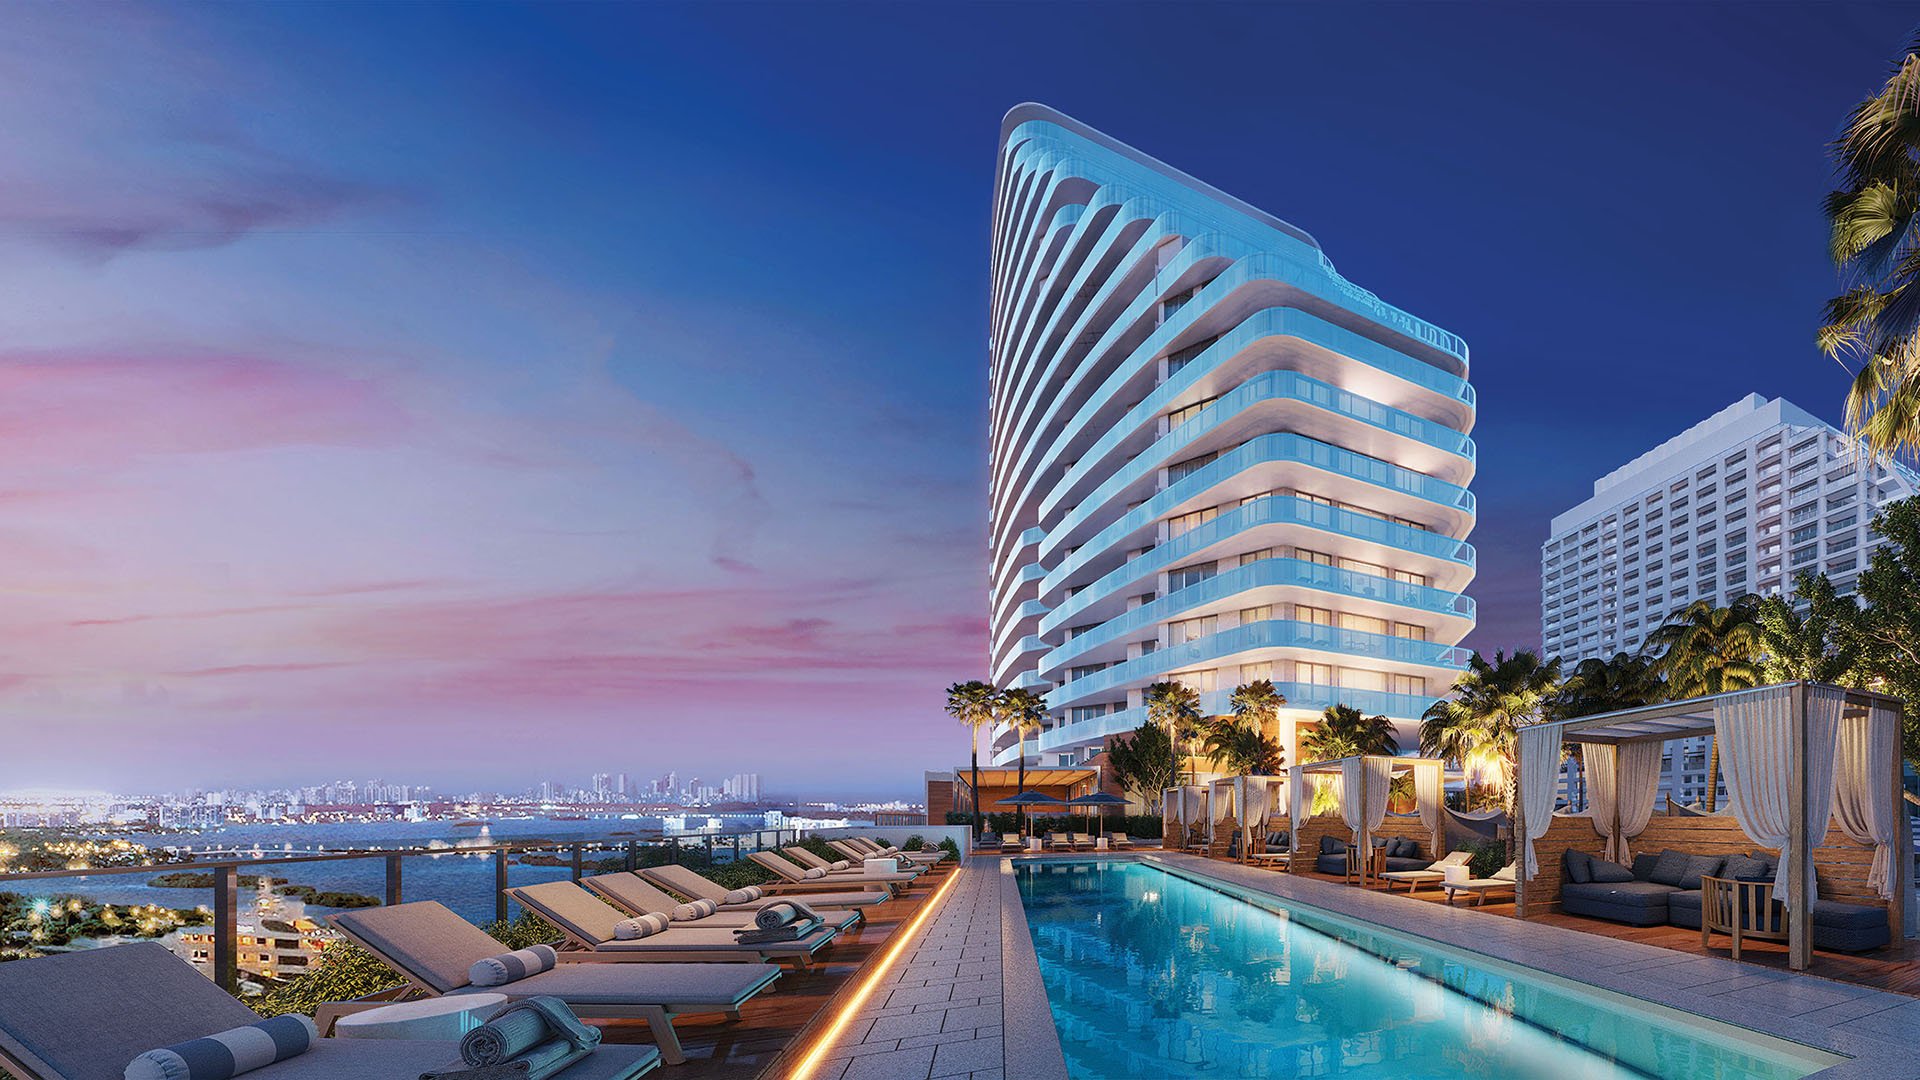
For a married couple establishing Florida domicile, selecting a South Florida residence is both a lifestyle decision and a legal planning exercise. The contract should support the intended permanent home, proposed ownership structure and family estate plan. Those objectives deserve attention before earnest money becomes nonrefundable-not when the closing documents arrive.
A residence at The Residences at 1428 Brickell may belong on a couple’s Brickell shortlist, but the planning questions remain personal: Who will acquire title? When will the property become the permanent residence? What should happen when either spouse dies?
Property-tax eligibility, constitutional creditor protection and restrictions on inheritance require separate analyses. A satisfactory answer under one does not establish the others. Contract review should coordinate those questions without treating “homestead” as a single, universal approval.
Florida’s property-tax homestead exemption generally requires legal or beneficial title in equity and permanent-residence status as of January 1 of the tax year. Acquiring the residence after January 1 generally means waiting until the following tax year to meet that annual qualification date.
For buyers, the practical task is to compare the expected closing date with the actual move. Signing a purchase agreement does not satisfy the title and residence requirements. Nor does purchasing a Florida home, by itself, establish it as the applicant’s permanent residence.
A couple considering Park Grove Coconut Grove should therefore distinguish the acquisition calendar from the relocation calendar. A Coconut Grove address can be part of the plan; eligibility still depends on the couple’s circumstances and the applicant’s qualifying interest.
Ask counsel to assess whether the proposed title and occupancy timeline support the intended tax year. Do not build the purchase budget around an exemption that has not yet been established.
The buyer named in the contract, the grantee named in the deed and any trustee taking title should fit one coherent ownership plan. If the couple intends a trust to hold the residence, review that intention before assuming the buyer’s identity can be changed at closing.
Check the assignment provision and identify any contractual steps needed to accommodate the intended grantee. Review title, financing, inspection and attorney-review protections before the deposit becomes nonrefundable. These are contract-review priorities, not assurances that every agreement contains those protections.
For a proposed trust acquisition, confirm the trust’s exact name and date, the acting trustee’s authority, occupancy provisions and intended distribution. The central property-tax question remains whether the arrangement gives the applicant the legal or equitable interest required for the exemption.
The objective is consistency across documents. The purchase agreement should not contemplate one ownership structure while the lender, deed and estate plan contemplate another. Resolve discrepancies before the transaction reaches its least flexible stage.
Permanent residence should be supported by a consistent factual record. Potential evidence includes a Florida driver license, utility records, school records, bank-address documentation and a recorded Declaration of Domicile. No single item should be treated as a substitute for the underlying residence requirement.
Confirm documentation requirements with the property’s county. Do not assume that a requirement to supply three forms of residency identification is a universal statewide checklist.
For a couple evaluating Four Seasons Hotel & Private Residences Fort Lauderdale, the Fort Lauderdale purchase and residency documentation should be coordinated, not treated as unrelated tasks.
Homestead applications generally require Social Security information for both the applicant and spouse, even if the spouse is not on title or does not occupy the property. The couple should also disclose and resolve competing residency-based exemptions elsewhere, which can jeopardize eligibility. A complete review considers both spouses’ circumstances, not just the name on the deed.
A property-tax exemption is not a comprehensive creditor-protection opinion. Ask counsel to analyze constitutional homestead protection separately, including how the actual title, residence and trust arrangement affect the conclusion. Neither a luxury purchase nor a trust label supplies that analysis.
An irrevocable trust is not automatically a creditor-protection solution. Under the general rule, a settlor’s creditor may reach the maximum amount distributable to or for the settlor’s benefit. The operative terms matter more than the document’s name.
A different, narrower issue arises concerning a deceased owner’s protected homestead held in a trust. In the circumstances covered by the applicable rule, a trust’s power of sale or general direction to pay debts does not, by itself, expose protected homestead to the decedent’s creditors or estate expenses.
That rule should not be expanded into blanket protection for every revocable or irrevocable trust. The useful question is not simply whether the residence is “protected,” but which protection is being evaluated, for whom and under which circumstances.
Florida homestead restrictions can limit disposition at death when the owner is survived by a spouse or minor child. A devise to the surviving spouse is permitted when there is no minor child, subject to applicable statutory qualifications. Do not assume that a will or trust overrides those restrictions.
For buyers considering Alina Residences Boca Raton, the Boca Raton acquisition should be reviewed alongside the intended succession plan. Counsel should test the proposed distribution against the family’s actual circumstances rather than assume an existing estate document remains suitable.
Placing homestead in a revocable trust does not automatically eliminate its protections or remove restrictions on disposition at death. An impermissible disposition through a covered trust can cause title to pass under Florida’s homestead succession rules rather than through the trust’s intended distribution.
Before closing, the couple should have a coordinated understanding of buyer and grantee identities, trustee authority, financing requirements, the permanent-residence timeline and intended succession. Any later transfer into a trust deserves its own review rather than being treated as routine paperwork.
The strongest outcome is not merely a completed purchase. It is a residence whose contract, title and estate planning support the couple’s intentions without promising protections that require separate legal analysis. This is planning information, not an opinion on a particular contract; outcomes depend on residence, title, family circumstances, financing and trust terms.
For a discreet introduction to South Florida residences that suit your next chapter, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationJanuary 1 of the tax year generally controls. The applicant must have the required legal or beneficial title in equity and permanent-residence status by that date.
Acquiring the residence after January 1 generally means waiting until the following tax year to meet the annual qualification date. Ownership alone does not satisfy the permanent-residence requirement.
No. Purchasing the property alone is insufficient; the applicant must also satisfy the permanent-residence requirements.
Potential evidence includes a Florida driver license, utility records, school records, bank-address documentation and a recorded Declaration of Domicile. Confirm the documentation requirements with the property's county.
Homestead applications generally require Social Security information for both the applicant and spouse, even when the spouse is not on title or does not occupy the property.
Yes. A competing residency-based exemption elsewhere can jeopardize eligibility, so existing exemptions should be disclosed and resolved.
Confirm the trust's exact name, date, trustee authority, occupancy provisions and intended distribution. Align the contract and deed with an ownership structure that supplies the applicant's required legal or equitable interest.
No. A revocable trust does not automatically remove those restrictions, and an impermissible disposition through a covered trust can result in title passing under Florida's homestead succession rules.
No. Under the general rule, a settlor's creditor may reach the maximum amount distributable to or for the settlor's benefit.
Not necessarily. Florida restricts devise when the owner is survived by a spouse or minor child; a devise to the surviving spouse is permitted when there is no minor child, subject to applicable statutory qualifications.