A considered move from Greenwich to Palm Beach Gardens begins with more than a property search. Coordinate homestead eligibility, deed vesting, beneficiary instructions and accessible capital, then build a residence-specific operating budget before closing.
For a Greenwich household considering Palm Beach Gardens, the consequential decision is not simply which residence to buy. It is how that residence will function within the family's financial life: permanent home or seasonal retreat, protected asset or source of capital, personal sanctuary or property intended for the next generation.
The purchase, estate plan and operating budget should be designed together. A residence can be central to family life without becoming the family's only readily identifiable store of wealth. Palm Beach Gardens is the setting; disciplined ownership makes the transition durable.
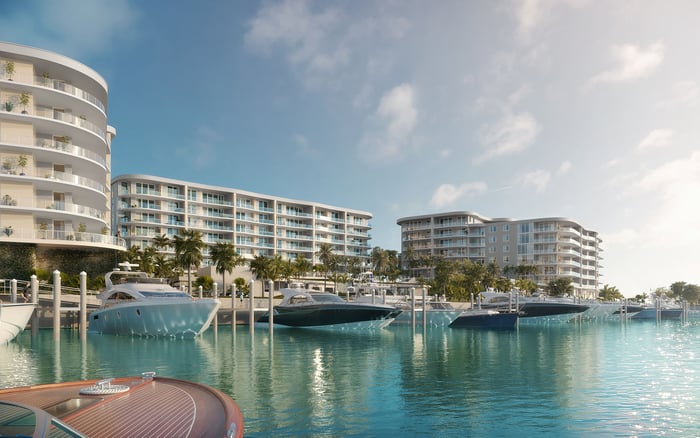
When considering The Ritz-Carlton Residences® Palm Beach Gardens, begin with the same questions you would bring to a private estate: who will own it, who may occupy it, who should inherit it and which assets will pay its bills?
Buying in Florida does not automatically confer homestead benefits. Qualifying ownership, permanent Florida residency and use as a permanent residence are required. The usual application deadline for the property-tax homestead exemption is March 1. Evaluate a seasonal purchase without assuming those benefits.
Keep four concepts separate: property-tax relief, limits on assessment growth, creditor protection and inheritance restrictions. None substitutes for probate planning.
Have advisers estimate the property's homestead exemption benefit rather than assuming a standard dollar saving. Confirm eligibility and the applicable exemptions before incorporating tax relief into the operating budget.
Save Our Homes limits annual increases in a qualifying homestead's assessed value to 3% or the applicable inflation rate, whichever is lower. That is an assessment limit, not a promise that the total tax bill cannot rise more quickly. Eligible portability applies to benefits accumulated between qualifying Florida homesteads, not a benefit imported from Greenwich.
Ask advisers to evaluate the two-state residency position separately. A Florida purchase does not, by itself, settle the question of domicile.
Before approving vesting, have Florida counsel reconcile the proposed deed with the trust, marital circumstances and intended beneficiaries. Tenancy by the entirety can provide married owners with additional creditor protection, but that choice belongs within the broader estate plan.
A revocable trust can hold a Florida homestead, provided it is drafted to preserve occupancy rights and eligibility. Do not assume an existing trust document addresses every Florida-specific issue.
Inheritance requires particular attention when an owner is survived by a spouse or minor child. Florida homestead law restricts how the primary residence may be left in those circumstances. A preferred beneficiary instruction cannot be considered in isolation from those restrictions.
Qualifying homestead equity generally receives protection from most creditor claims, with exceptions including mortgages, property taxes and mechanics' liens. Protection may extend to qualifying beneficiaries, depending on the plan and applicable rules. Do not assume heirs automatically retain the deceased owner's assessment cap or tax savings.
Title vesting and title insurance warrant coordinated but separate review. Before closing, ask the title professional and counsel to explain the proposed insurance documents in relation to the intended owner.
Request written answers to practical questions: What coverage is proposed? Which exceptions and exclusions require attention? What is the quoted premium? If ownership will involve a trust, or a later transfer is contemplated, what treatment needs confirmation?
The objective is not to choose an ownership structure based on an assumed insurance outcome. It is to align the deed, estate documents and insurance arrangements before signing. Keep the relevant documents together for future advisers and family decision-makers.
A homestead-focused estate strategy can preserve the residence as a protected family asset while maintaining liquidity elsewhere. Protection and accessible cash solve different problems.
Ask the advisory team to map three things: the anticipated property obligations, the person authorized to address them and the assets intended to fund them. Then consider whether that arrangement works during incapacity and after death.
Revocable trusts, payable-on-death or transfer-on-death accounts, and retirement-account beneficiary designations can help coordinate transfers outside probate. Review them together rather than assuming they automatically produce a coherent result.
No single reserve amount suits every estate. Model a property-specific funding period with advisers, including any estate-tax obligations they identify. The practical test is whether the family could retain the residence without relying on an immediate sale to meet its expenses.
Separate acquisition costs, financing cash flow and ongoing residence expenses. Principal and interest belong in the household cash-flow model, but they are not the same as the cost of operating the property.
Build the budget around the selected residence: property taxes, homeowners insurance, association dues, utilities and maintenance. Keep financing payments visible but separate, and avoid treating a general purchase-cost illustration as a luxury-residence quote.
Obtain property-specific insurance quotes rather than relying on broad annual allowances. Construction, roof age and wind mitigation can affect cost. Larger residences also warrant their own utility estimates rather than reliance on modest-home allowances.
For buyers extending the comparison to West Palm Beach, apply the same worksheet to Alba West Palm Beach. Request the actual residence budget and identify which expenses fall outside association dues. Do not apply a Palm Beach Gardens model to another property unchanged.
Association dues may cover common-area maintenance, security, reserves, management, building insurance and bundled utilities. A lower monthly figure does not establish a lower total ownership cost.
Compare current dues and documented inclusions for each shortlisted residence. Different bundled services make headline monthly amounts an incomplete basis for comparison.
In Avenir, buyers may encounter both HOA dues and a community development district assessment on the property-tax bill. Elsewhere, ask the same question about additional obligations. Do not assume dues include golf membership, initiation fees, club charges or special assessments.
If Forté on Flagler West Palm Beach joins the shortlist, compare documented obligations rather than presumed service levels. Before committing, assemble one coordinated file: proposed vesting, beneficiary review, title-insurance answers, property-specific costs and a liquidity plan. The right residence should serve the family's life without leaving its continuity to chance.
Explore a considered South Florida property search with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Eligibility requires qualifying ownership, permanent Florida residency and use of the property as a permanent residence.
The usual deadline is March 1. Confirm your property's eligibility and application requirements before relying on the exemption.
No. Have advisers estimate the property's benefit and confirm the applicable exemptions before including tax relief in the budget.
No. It limits annual increases in a qualifying homestead's assessed value to 3% or the applicable inflation rate, whichever is lower.
Yes, but careful drafting is needed to preserve the owner's occupancy rights and homestead eligibility. Coordinate the trust and deed with Florida counsel.
Not without considering applicable restrictions. Florida homestead law limits how the residence may be left when the owner is survived by a spouse or minor child.
No. Do not assume that inheriting the residence automatically preserves the deceased owner's assessment cap or tax savings.
Ask about proposed coverage, exceptions, exclusions and the quoted premium. Request confirmation of how contemplated trust ownership or later transfers would be treated.
Protected home equity and accessible cash serve different purposes. Assets outside the residence can be planned to fund property obligations without depending on an immediate sale.
No. Confirm included services and separately investigate utilities, owner-paid insurance, club charges and assessments; Avenir buyers may also face a community development district assessment.