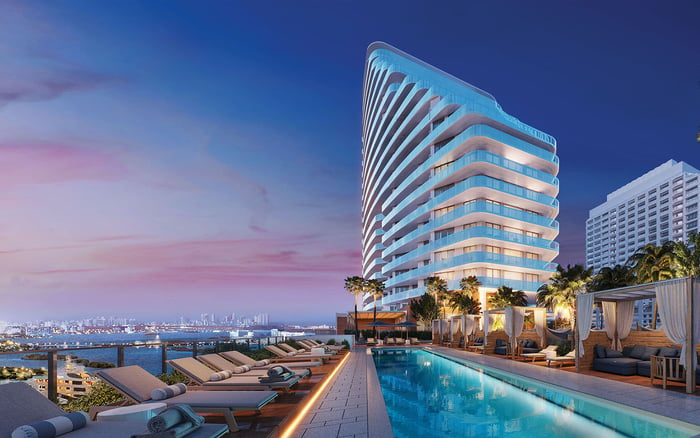
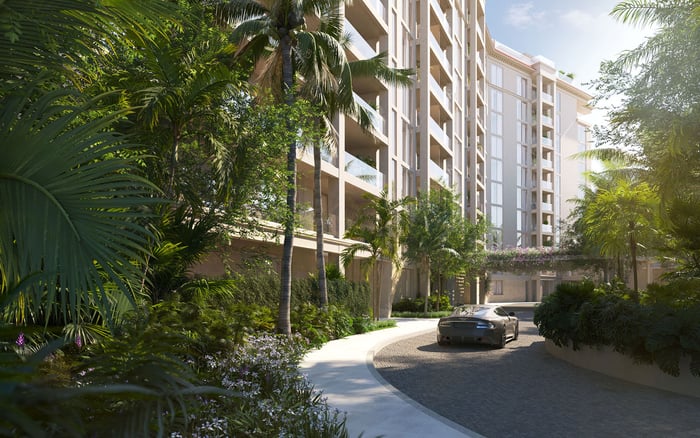
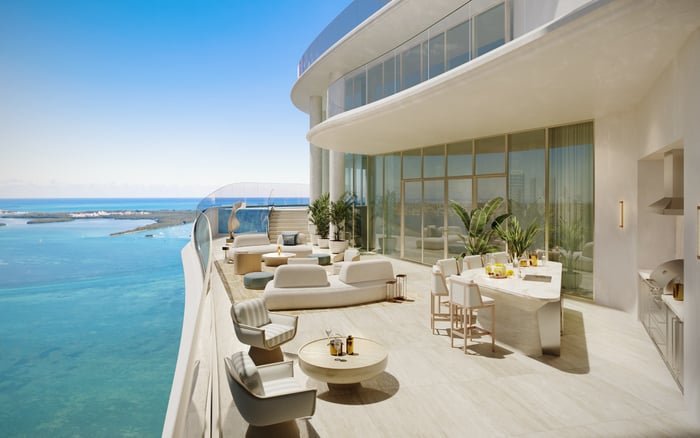
A discerning penthouse search begins with service expectations and ends with verified operating costs. These Fort Lauderdale fee disclosures offer useful comparisons, alongside a framework for evaluating reserves, insurance and the true scope of high-service ownership.
For a buyer seeking an effortless South Florida residence, a penthouse’s appeal extends beyond its elevation. It is the prospect of arriving without logistical friction, entertaining with support and leaving with confidence. Yet the operating structure that makes ownership feel seamless must be funded month after month.
The best fit is not necessarily the lowest-fee residence. It is the home whose verified services justify its carrying costs, supported by a budget that accounts for insurance, reserves and ongoing operations. The penthouses below are candidates and comparables with disclosed fees, not a ranking of confirmed high-service offerings or stabilized associations.
That distinction matters. A disclosed monthly assessment is a starting point for underwriting, not proof that future obligations are contained. Buyers should first define the service they value, then determine whether the association can sustain it at a cost they accept.
Hotel-style staffing, valet, concierge, spa facilities and restaurant operations materially increase condominium carrying costs. For owners who use these services regularly, the premium may be entirely rational. The question is whether the monthly assessment delivers the experience they expect.
For typical two- to three-bedroom luxury homes in non-branded resale buildings, general monthly fee ranges run around $1,500-$3,000. Entry-level branded residences fall around $2,500-$4,500, while full-service hospitality-branded residences run around $4,000-$8,000 or more.
These are comparison bands, not verified penthouse budgets. An unusually large residence should not be judged against a typical two-bedroom assessment, and the upper end of a general range is not a ceiling.
For buyers considering Four Seasons Hotel & Private Residences Fort Lauderdale, the essential step is to obtain the specific residence’s current fee and documented service inclusions. General hospitality-branded cost ranges cannot substitute for those records.
Broader South Florida high-rise assessment averages describe a wider market, not a luxury-penthouse cost target.
The following residences illustrate the breadth of disclosed monthly assessments. The figures are listing snapshots; fees, availability and asking prices may change. None should be treated as a confirmed recommendation for high-service ownership without a review of its service package and association finances.
This Fort Lauderdale penthouse has a disclosed HOA fee of $4,350 monthly. It provides a concrete figure against which to test a buyer’s ownership budget, but the amount alone establishes neither staffing levels nor included services nor financial stability.
The next step is to reconcile that disclosure with the current association fee and latest budget. A seemingly comfortable monthly figure becomes meaningful only when the obligations behind it are understood.
The disclosed asking price is $5.15 million, with an HOA fee of $7,421 monthly. Acquisition price and recurring assessment deserve separate evaluation: willingness to pay the purchase price does not automatically make the monthly fee appropriate for the buyer’s intended use.
The review should establish what the assessment includes and how operating expenses, insurance and reserves contribute to it. The disclosed amount does not, by itself, demonstrate superior service.
This residence carries a disclosed HOA fee of $12,652 monthly, the highest of these four snapshots. It illustrates why general branded-residence fee bands should never be treated as penthouse spending limits.
A higher assessment is neither proof of exceptional service nor evidence of poor value. It calls for a clear accounting of the services, expenses and funding obligations behind the fee.
At $1,743 monthly, this penthouse offers a lower-fee contrast. It should not, however, be characterized as a high-service bargain without confirmation of a comparable service package.
Its role in the comparison is to sharpen the buyer’s priorities. If a lower-fee home lacks the desired support, the question becomes whether the owner is comfortable arranging that support separately.
For purchasing purposes, stabilized should describe a budget whose major recurring expenses and reserve obligations have been examined-not a promise that assessments will remain unchanged. Rising insurance costs and reserve-funding requirements are major contributors to South Florida condominium assessment increases.
Begin with the latest adopted condominium budget and confirmation of the current unit-specific fee. An older listing figure should not anchor the decision. Review reserve balances, special-assessment history, insurance expenses and structural-reserve funding together, rather than accepting any single figure as reassurance.
Ask how the association funds its obligations and whether the current assessment reflects them. A low monthly fee is not automatically conservative if material costs remain unresolved. Equally, a larger assessment may be acceptable when its purpose is clearly documented and aligned with the buyer’s expectations.
Resale buyers should apply the same discipline regardless of a building’s reputation. Familiarity with an address does not replace a review of its current finances.
When extending a search to Brickell, a buyer considering St. Regis® Residences Brickell should distinguish brand appeal from the specific services and expenses attached to the residence under consideration. Request written inclusions rather than assuming every desired service falls within the association assessment.
The same principle applies in Sunny Isles Beach when evaluating The Ritz-Carlton Residences® Sunny Isles. Ask which services are included, which carry separate charges and what staffing coverage is documented. These are questions to verify, not assurances about a particular property’s operating model.
A useful comparison keeps three categories separate: recurring association assessments, services the owner expects to purchase separately, and potential additional association obligations. Combining them too early can obscure why one residence appears less expensive than another.
A meaningful penthouse shortlist pairs each fee with verified service scope and financial documentation. It should also resist false precision: without confirmed unit sizes, an HOA-per-square-foot comparison is not reliable. The four disclosed figures above establish neither service equivalence nor a value ranking.
The strongest choice is the residence whose support suits the owner’s daily life and whose costs remain acceptable after scrutiny. That is a more durable definition of luxury than either the lowest assessment or the most expansive amenity promise.
For a discreet conversation about aligning your penthouse search with service expectations and ownership costs, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo definitive ranking is established for these candidates. The best fit requires verification of the residence’s service package, current assessment and association finances.
The disclosed fee is $4,350 monthly. Buyers should confirm the current unit-specific assessment and review the latest condominium budget.
The disclosed asking price is $5.15 million, with a monthly HOA fee of $7,421. Both figures are snapshots and may change.
The disclosed HOA fee is $12,652 monthly. That amount alone does not establish the quality or extent of included services.
Its disclosed HOA fee is $1,743 monthly, but a comparable high-service package has not been established. The lower assessment should be treated as a contrast, not proof of better value.
General guidance places these residences around $4,000–$8,000 or more monthly. This is not a penthouse-specific benchmark or spending ceiling.
Review the latest budget, current association fee, reserve balances, special-assessment history, insurance expenses and structural-reserve funding. Stabilized does not mean future assessments cannot increase.
Hotel-style staffing, valet, concierge, spas and restaurant operations materially increase carrying costs. Insurance expenses and reserve-funding requirements also contribute to assessment increases.
Not without confirmed unit sizes. A useful comparison also requires verified service inclusions and association financial documentation.
No. Broader high-rise assessment averages describe a wider market and should not be applied as luxury-penthouse cost targets.