ORA’s differing advertised deposit schedules make unit-specific contract review essential. Buyers should compare payment amounts, milestone timing and closing liquidity while separating inflation’s effect on future payments from its effect on ownership costs.
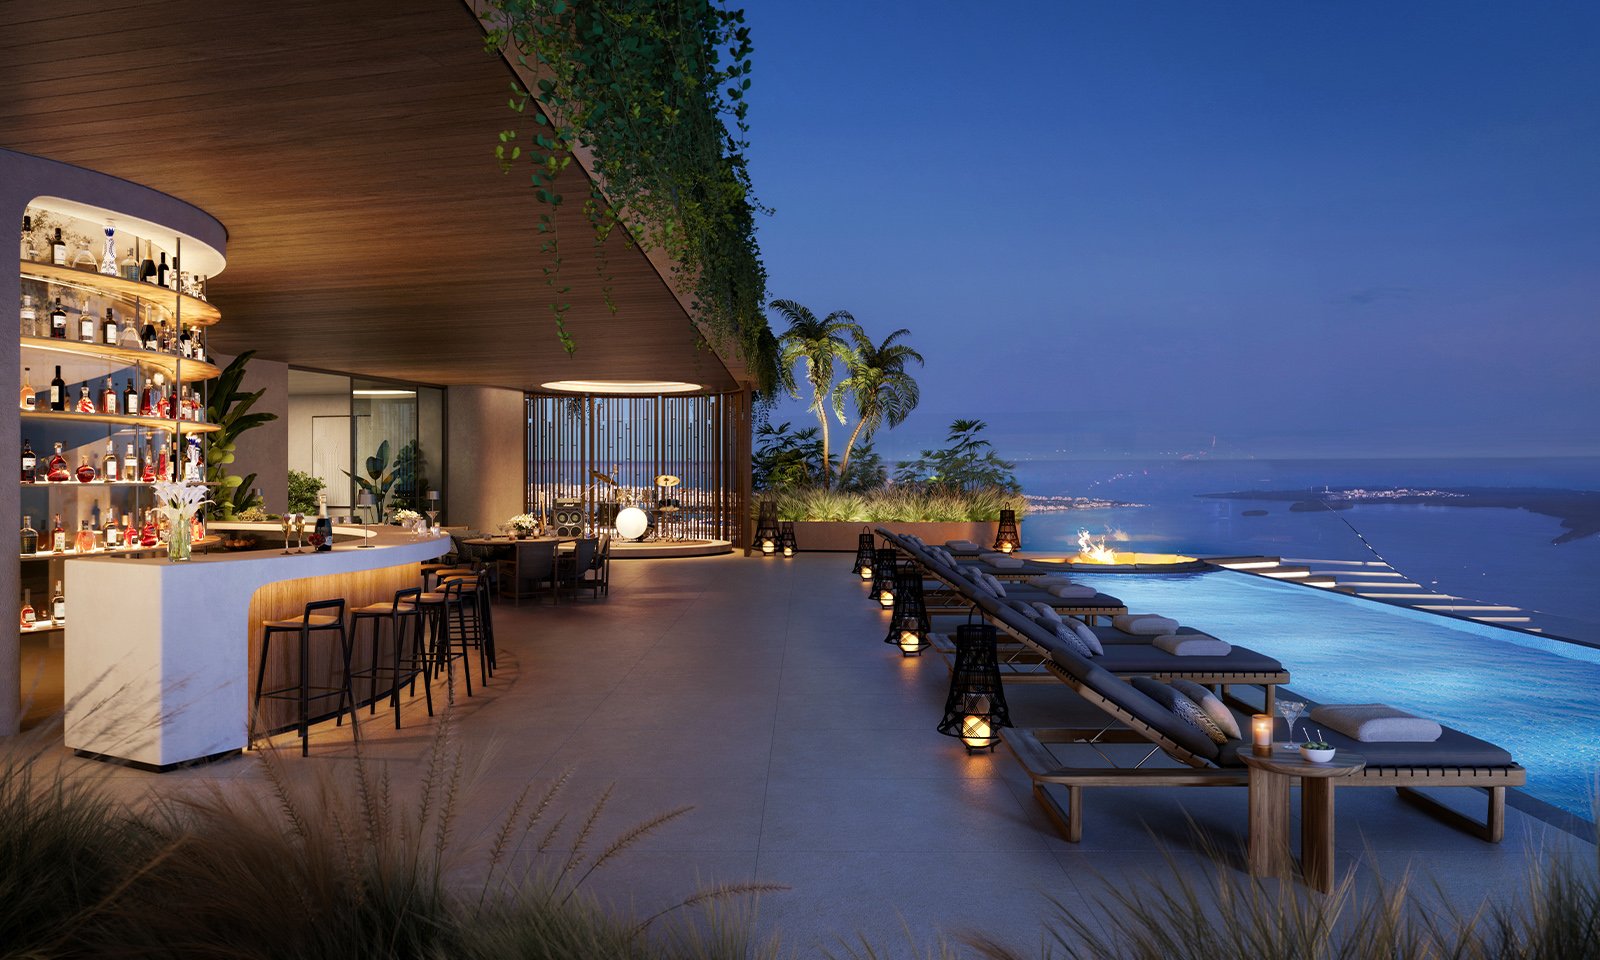
The appeal of ORA by Casa Tua Brickell begins with its hospitality identity and Brickell address. Planned by Fortune International Group at 1210 Brickell Avenue, the development’s August 2025 specifications called for a 77-story, 533-residence tower. Those are dated specifications, not verified final construction figures.
For a buyer, however, the decisive document is not the presentation. It is the unit-specific purchase agreement, read alongside the reservation paperwork and payment schedule. Advertised schedules differ in both the amount committed before closing and the milestone that triggers payment. Those differences affect liquidity even when the headline purchase price is identical.
Here, “reserve schedules” means reservation and purchase-deposit schedules, not condominium association reserves. The essential exercise is to translate every percentage into dollars, establish when those dollars become payable and identify what remains uncertain.
Advertised starting prices include studios from $950,000, one-bedrooms from $1.2 million, two-bedrooms from $1.5 million and three-bedrooms from $3 million. A separate advertised range runs from $990,000 to $4 million. Neither establishes the price at which a particular residence can be purchased today.
Launch pricing started at $800,000 in 2023. Comparing that figure with a later advertised minimum does not demonstrate same-unit appreciation. Unless the residence, specifications, incentives and contract terms match, the comparison is between marketing snapshots, not investment outcomes.
Request a dated quotation identifying the residence and purchase price, with incentives, inclusions and additional buyer charges stated separately. Reconcile that quotation with the agreement. Confirm whether the price is fixed, and have counsel identify any provisions that could change the buyer’s total obligation.
A buyer also considering Cipriani Residences Brickell should apply the same discipline to each proposal. Compare documented terms-not an advertised minimum at one property with a unit-specific quotation at another.
ORA’s advertised payment schedules are not uniform. One shows 10% at reservation, 10% at contract, 20% at groundbreaking, 10% at top-off and 50% at closing. Another shows 20% at contract, 20% at groundbreaking, 10% at the 10th floor and 50% at closing.
A third shows 20% at contract, 10% at groundbreaking, 10% at top-off and 60% at closing. A fourth shows 20% at contract, 20% at groundbreaking, 10% at top-off and 50% at closing.
The distinction is substantive: the third schedule totals 40% before closing; the others total 50%. The third schedule should not be treated as a confirmed available offer. Nor do these discrepancies establish why the schedules differ or which version applies to a particular buyer.
At a hypothetical $1.5 million contract price, used solely to illustrate the arithmetic, 40% means $600,000 funded before closing, versus $750,000 at 50%. The corresponding purchase-price balances are $900,000 and $750,000, before other closing obligations. That $150,000 difference changes when capital is needed, not the assumed purchase price.
Reservation treatment requires equal care. One advertised schedule lists a 10% reservation deposit and expressly requires confirmation of refundability. Do not assume that a reservation payment is refundable or automatically additional to a stated contract deposit. Obtain written confirmation of how any reservation payment is credited.
A payment at the 10th floor is not equivalent to one at top-off. Although both may represent 10% of the price, they correspond to different construction stages and potentially different funding timelines. Ask how each milestone is defined, how notice is delivered and how much time the agreement allows for payment.
The advertised calendar also requires reconciliation. An older schedule placed contracting in September 2023, groundbreaking in Q3 2024, top-off in Q1 2027 and closing in Q1 2028. A separate advertised delivery date is April 2029. These are marketing dates-not evidence that the listed milestones occurred or binding confirmation of a closing date.
Build a cash-flow calendar from the current documents, distinguishing estimated dates from contractual triggers. Test earlier payment notices as well as a later closing. An earlier milestone can accelerate a cash requirement; a delay can leave previously committed capital unavailable for longer.
Inflation affects this purchase in more than one direction. If a future payment is contractually fixed, inflation can reduce its purchasing-power value. That does not make the payment smaller in nominal dollars or establish that the residence will appreciate.
Meanwhile, association charges, insurance, property taxes and management expenses may rise. A favorable view of deferred purchase payments can therefore coexist with a less favorable operating budget. Treat these as separate calculations rather than allowing one inflation assumption to stand in for the entire investment case.
For each deposit, record the dollar amount, expected payment date, funding source and opportunity cost. Model borrowing expense where relevant. Estimate ongoing ownership expenses separately, using sensitivity cases rather than an unsupported inflation forecast. Avoid counting financing expense and opportunity cost twice for the same funds.
When comparing ORA with The Residences at 1428 Brickell, use consistent assumptions about holding period, liquidity and operating-cost growth. This is a comparison framework, not a claim that the projects share deposit terms or ownership economics.
Ultimately, a higher nominal resale price is not sufficient evidence of a positive real return. Acquisition costs, financing, carrying expenses, disposal costs and inflation all belong in that assessment.
Before committing funds, have counsel review refundability, escrow arrangements, permitted uses of deposits, default provisions, extension rights and closing obligations. Do not infer escrow protection or a right to cancel from the existence of a reservation form.
A $36.08 million loan announced in July 2024 was characterized as pre-development financing. It should not be treated as confirmation of a completed construction-financing package. Likewise, the roughly 45% presold description from July 2024 coincided with plans to convert reservations into contracts. It does not automatically establish binding sales or guarantee completion.
ORA’s early positioning included short-term rentals. For a buyer factoring rental income into the purchase decision, marketing is only a starting point. Review governing documents and applicable rules, then test management expenses and potential income conservatively. Do not assume rental proceeds will fund ownership costs.
The most useful comparison is a single cash-flow schedule supported by the current quotation and agreement. It should show every payment and its trigger, reservation credits, the remaining purchase-price balance and separately estimated closing costs. Maintain a liquidity plan for timing changes and operating-cost increases.
The objective is not to select the smallest advertised initial deposit. It is to understand the full commitment and ensure that the residence fits both the buyer’s lifestyle and capital plan.
For a discreet perspective on your next South Florida residence, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationIt refers to reservation and purchase-deposit payments, not condominium association reserves. The focus is the amount and timing of a buyer’s purchase commitments.
ORA is planned at 1210 Brickell Avenue in Miami’s Brickell neighborhood, with Fortune International Group as developer.
Public marketing includes studios from $950,000, one-bedrooms from $1.2 million, two-bedrooms from $1.5 million and three-bedrooms from $3 million. These figures do not establish current unit-specific contract pricing.
No. Public presentations differ on reservation treatment, construction payment triggers and whether 40% or 50% is funded before closing; the applicable terms require written confirmation.
No. It appears in a public presentation but should not be treated as available without confirmation in the buyer’s current documents.
Refundability requires confirmation in the reservation documents. Buyers should also establish how that payment is credited toward later deposits.
The 10th floor and top-off are different construction stages. An otherwise identical percentage can require funding on a different timeline depending on the contractual trigger.
April 2029 is an advertised delivery date, while an older presentation listed Q1 2028 closing. Neither should substitute for review of the agreement’s timing and extension provisions.
No. Inflation can reduce the purchasing-power value of a fixed future payment while increasing ownership expenses, and nominal appreciation alone does not establish a positive real return.
Early positioning included short-term rentals, but buyers should review governing documents and applicable rules. Rental income assumptions should also account for management and other ownership expenses.