A pre-completion assignment deserves more than a signed transfer. Buyers should negotiate when funds become nonrefundable, establish an accepted signing route, distinguish lender approvals, and verify every wire independently.
Taking an assignment before completion requires a buyer to evaluate both the residence and the contractual position being acquired. The view may be compelling; the transfer mechanics deserve equal attention. Before assignment consideration becomes nonrefundable, the buyer should understand which approvals remain outstanding, how documents will be signed and who bears the cost if the proposed route fails.
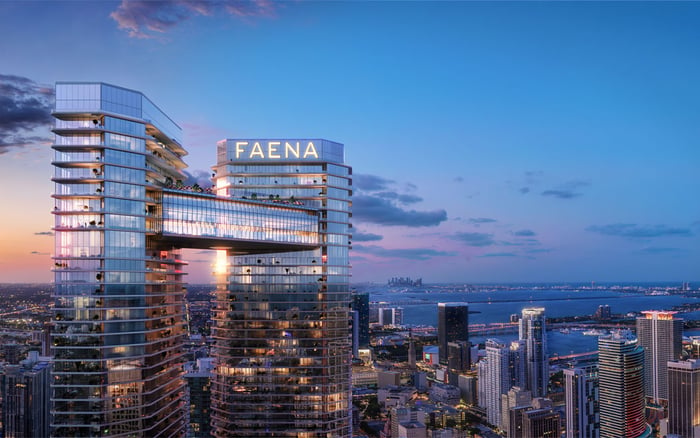
For a buyer considering a residence such as The Residences at 1428 Brickell, the distinction is between enthusiasm for Brickell and acceptance of a particular assignment agreement. A project's inclusion here does not establish that an assignment is available or permitted.
The protections below are proposed negotiating positions, not automatic Florida rights. Transaction counsel should tailor them to the purchase contract, assignment documents and participants' written requirements.
Begin by asking counsel to reconcile the original purchase agreement, amendments, payment records and proposed assignment. The commercial questions are straightforward: what contractual position is being transferred, what money has already been paid, what remains payable and what representations will the assignor make about that history?
The proposed agreement should separately identify deposit reimbursements, any assignment premium and future purchase obligations. Rather than treating those amounts as a single payment, ask counsel to specify the recipient, holding arrangement, release trigger and treatment of each if the transaction cannot proceed.
Consider negotiating for assignment consideration to remain refundable until identified approvals and document acceptance are obtained. The agreement should specify which failures permit termination, how refunds are handled and whether any costs remain with the buyer. Refundability should never be assumed merely because completion lies ahead.
Ask counsel to identify any consent required under the governing documents, who must request it, what constitutes satisfactory evidence and the delivery deadline. A verbal assurance should not substitute for the agreed written deliverable.
The same discipline applies when evaluating Miami Beach residences such as The Perigon Miami Beach. The property search and the assignment review are distinct exercises; neither the address nor the presentation resolves questions about consent or release.
Proposed protections can include an outside date, a negotiated exit if consent is not obtained and an express allocation of obligations arising before the transfer. Counsel should also address whether the assignor remains liable and whether any release is contemplated. Indemnification for inaccurate representations or specified prior breaches is another negotiating point, not an automatic remedy.
Treat remote signing as a question of acceptance, not simply convenience. Before scheduling a session, ask transaction counsel to confirm the proposed method for each document and obtain confirmation from the parties expected to accept it, including the lender and closing team where applicable.
The written signing plan should identify the signer, signing location, document version, proposed notarization method and any delivery requirements. Establish who will resolve a rejected signature package and who will pay for a replacement signing, courier service or delay.
Consider negotiating a document-acceptance milestone before assignment funds are released. This does not mean every remotely executed document is acceptable or unacceptable. It means the buyer should not assume acceptance before the relevant reviewers have considered the actual arrangement.
Where overseas execution raises an apostille question, ask counsel whether one is needed for the specific document and intended use. Do not assume every foreign-signed document requires one, or that obtaining one resolves every execution concern. Have the closing team identify its requirements before committing to the timetable.
If someone proposes signing through a power of attorney, request advance review of the instrument and proposed transaction. Counsel should address the authority being relied upon and obtain confirmation of acceptability from the relevant participants, rather than leaving the issue until funding day.
For a buyer whose search includes Bentley Residences Sunny Isles in Sunny Isles Beach, travel convenience should remain separate from document readiness. A negotiated fallback might allocate time and expense for an alternative signing route if the first proposal is rejected.
Keep three questions distinct: whether the lender accepts the proposed financing and assignment arrangement, whether it approves the closing agent and what title insurance covers. Selecting an agent does not itself establish lender acceptance of the transaction.
Ask counsel to confirm who may select the closing or title agent and what lender approval is required. Separately, seek written clarity on transaction-specific financing conditions and negotiate the consequences if those conditions cannot be satisfied.
Florida title insurance protects owners or lenders against losses arising from defective or invalid title, liens and other legal claims against title. It is not a substitute for negotiated assignment protections.
A closing protection letter may cover specified losses caused by fraud, theft, dishonesty or misappropriation by the issuing agent or approved attorney while handling funds or documents. Its conditions and exclusions matter. Ask the closing team to explain the actual letter rather than assuming blanket fraud coverage.
The payment protocol deserves the same attention as the contract. Examine the sender's full email address and verify instructions using an independently verified telephone number. A number supplied only within the wiring email is not an independent channel.
New or changed instructions require independent verification before payment. Pressure to wire immediately to avoid an alleged closing failure is a warning sign, as is an account name that does not match the expected recipient. Investigate discrepancies before sending funds, then independently confirm receipt with the closing agent.
Whether the search includes Rivage Bal Harbour or another residence, the discipline should remain unchanged. If funds are diverted, immediately contact the bank's fraud or wire department and request a recall. Notify the closing attorney and title company, preserve emails and payment records, and report the incident to the FBI's Internet Crime Complaint Center. Delay makes recovery more difficult.
Before committing, ask counsel for a concise schedule linking each payment to the agreed approvals, document acceptance and verification steps. Identify who must act, by when and what happens if a milestone is not met. The objective is not more paperwork; it is less ambiguity about whose capital is exposed.
For a considered South Florida property search, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationDo not assume it is refundable. Negotiate the approval conditions, termination rights and refund treatment expressly in the assignment agreement.
No. Counsel should review the governing purchase documents and identify any required consent for the specific proposed transfer.
Continuing liability and any release should be addressed expressly in the negotiations. They should not be treated as automatic protections for the incoming buyer.
No. Have counsel confirm the proposed signing method for each document and obtain acceptance from the relevant transaction participants before arranging execution.
Do not assume a universal requirement. Ask counsel to determine what is needed for the particular document and its intended use.
Request review before the planned signing and funding. Counsel should address the authority being relied upon and confirm acceptability with the relevant participants.
No. Closing-agent approval is distinct from acceptance of the proposed financing and assignment arrangement, which should be addressed separately.
It protects owners or lenders against losses arising from defective or invalid title, liens and other legal claims against title. It is not a substitute for negotiated assignment protections.
No. It may cover specified misconduct by the issuing agent or approved attorney, subject to the letter's conditions and exclusions.
Immediately contact the bank's fraud or wire department and request a recall. Notify the closing attorney and title company, preserve records, and report the incident to the FBI's Internet Crime Complaint Center.