For a Paris-based buyer, a Downtown Miami second home requires more than a dollar purchase price. Contract-specific deposits, euro funding decisions, escrow provisions and closing reserves should form one coordinated acquisition plan.
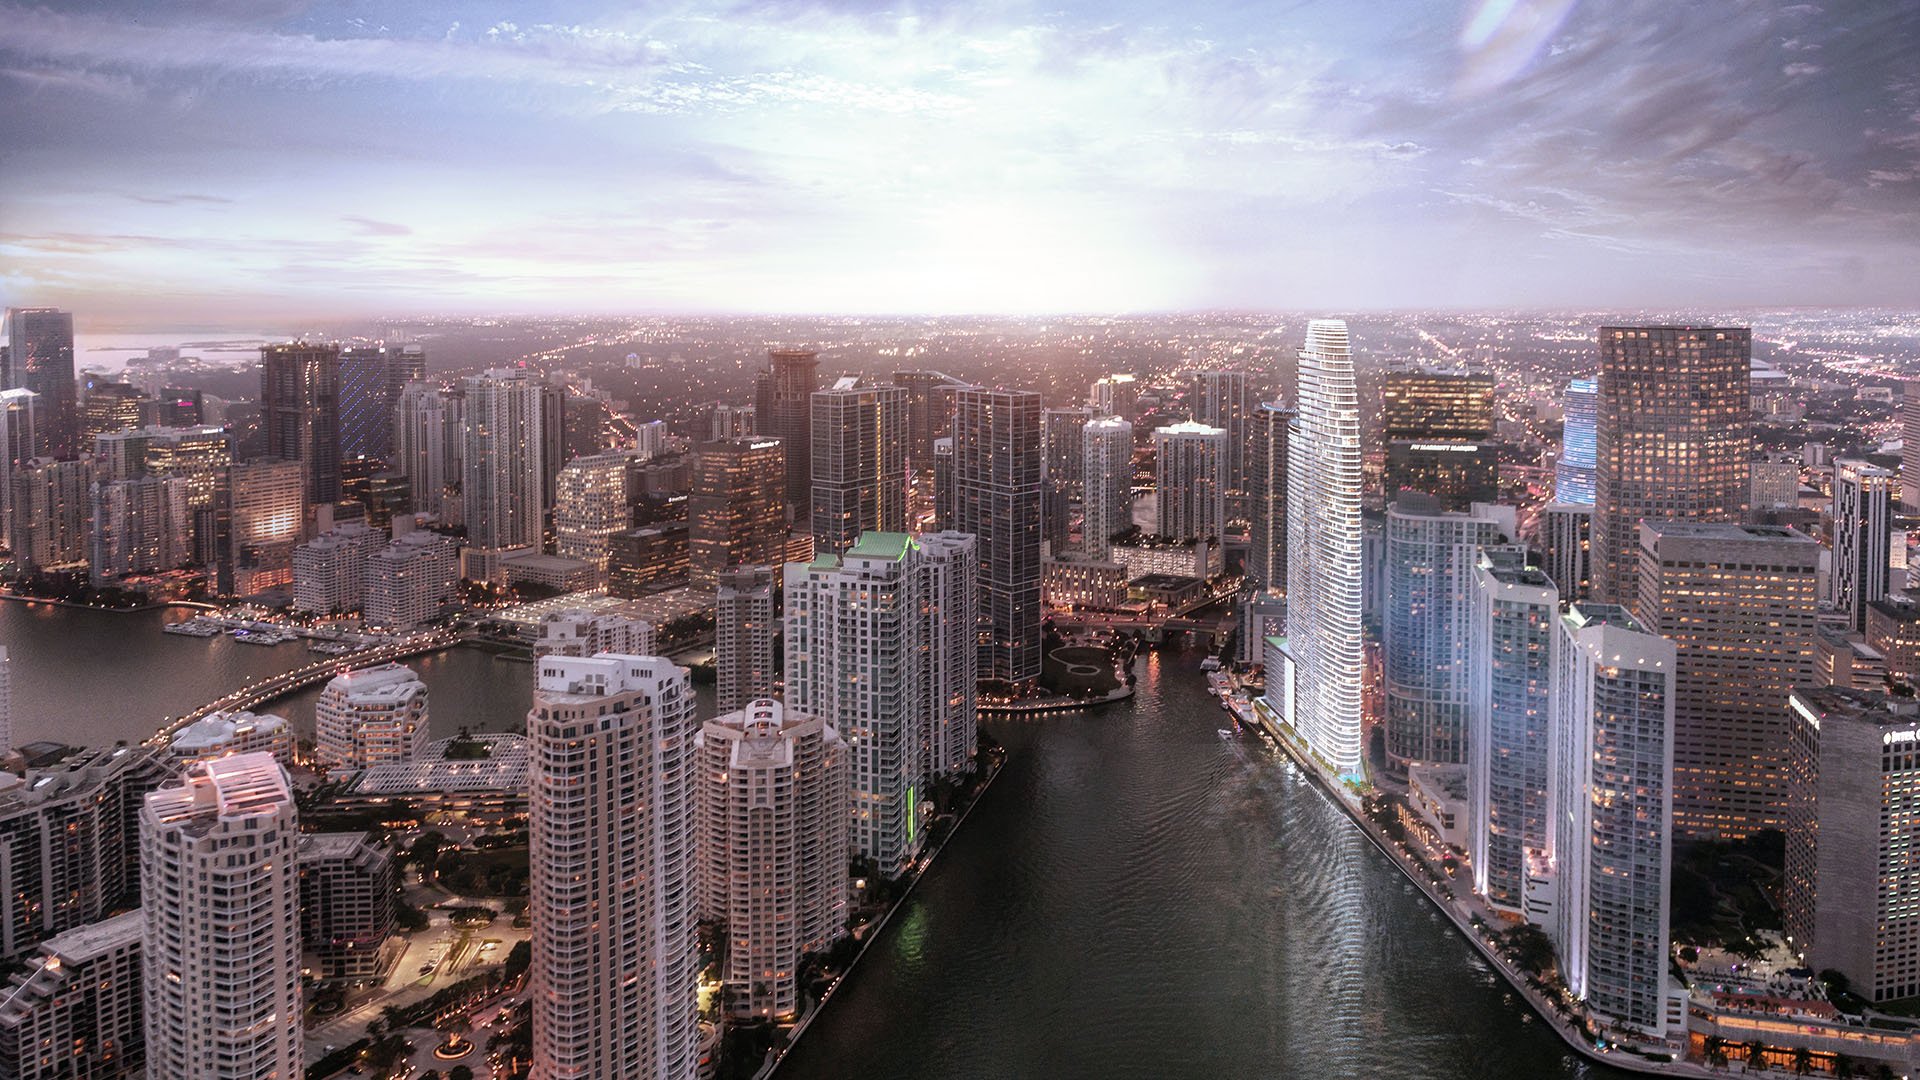
For a Paris-based buyer considering Downtown Miami, the financial question is not simply what a residence costs in dollars. It is how much must be available, when payment is due and which obligations remain after the keys arrive. A euro-denominated balance sheet and a dollar-denominated purchase agreement should be considered together, not as separate decisions.
That distinction matters when comparing residences such as Aston Martin Residences Downtown Miami with other shortlisted options. Planning should begin with the actual transaction documents, not an assumption that every residence follows the same funding calendar. A compelling address does not make payment timing interchangeable.
Financial readiness means distinguishing accessible capital, dollars committed to deposits, the remaining purchase balance and ownership expenses. Combining them into one headline budget can obscure when each amount must become available.
Miami pre-construction schedules are contract-specific. Illustrative structures require approximately 30%-50% of the purchase price before closing, but neither that range nor any particular construction trigger should be treated as universal.
One example is 20% at contract execution, 10% at groundbreaking, 10% at top-off and 60% at closing. Other structures begin with a reservation payment, followed by a 10% contract deposit and subsequent installments. These are planning examples, not quotations for any development mentioned here.
When considering Casa Bella by B&B Italia Downtown Miami, request the current written payment schedule for the specific purchase. It should identify reservation amounts, contract deposits, later milestones and the closing balance. The agreement should also establish deadlines, recipients, permitted payment methods and the consequences of late payment or delayed construction milestones.
Translate those terms into a working calendar. For each obligation, distinguish a fixed date from a construction event, and ask counsel how the notice and payment provisions operate. That distinction gives currency planning a contractual foundation.
A euro asset balance is not the same as dollars available to meet a purchase obligation. The useful question is not whether an exchange rate feels attractive, but whether the funding plan can meet the agreement’s requirements without relying on a favorable currency move.
Ask your banking and currency advisers to distinguish funds already available from assets requiring another step before payment. Then map each dollar obligation against the euro amount needed at the exchange rate under consideration. When a rate is expressed as dollars per euro, dividing the dollar payment by that rate gives the euro principal required, before applicable charges.
This is a budgeting relationship, not a forecast. No single conversion date or hedging strategy follows from a property’s deposit schedule alone. Whether to convert at once, in stages or through another arrangement is a question for qualified advisers working from your circumstances and the contract.
The objective is clarity about the payment obligation, not confidence in a currency prediction. Ask advisers to explain execution terms, costs and any continuing obligations before choosing an arrangement.
Deposit timing and deposit protection are separate questions. Do not assume that every installment remains untouched in escrow until closing.
Florida’s condominium framework generally provides escrow treatment for initial payments up to 10% of the purchase price before substantial completion, subject to statutory alternatives and release rules. Amounts above 10% may be available for actual construction costs under applicable legal and contractual provisions. Have Florida counsel verify the current requirements and explain how they apply to the proposed agreement.
For a buyer evaluating Waldorf Astoria Residences Downtown Miami, the relevant questions are contractual: who holds each payment, when it may be released, what use is permitted and what remedies apply. A deposit percentage alone answers none of them.
The final purchase installment is not the full closing requirement. Indicative Miami new-construction closing-cost estimates run approximately 3%-4.5% of the purchase price, with financing, project terms and contractual allocations affecting the actual figure. Treat this as an initial budgeting range, not a guaranteed ceiling.
Potential charges include title insurance, recording fees, attorney fees, financing costs, developer or administrative fees, and prepaid or prorated operating expenses. Some developments charge a developer-related fee of approximately 1.25%-1.75%. Do not automatically add that range to the broader closing estimate: some items may overlap.
Request an itemized estimate separating the unpaid purchase balance from transaction charges and association-related contributions. Initial working-capital contributions may also apply; one illustrative structure is approximately two months of association charges, but the governing documents must establish the actual obligation.
Keep closing funds distinct from post-closing liquidity. Neither the deposit schedule nor a percentage estimate determines the appropriate ongoing cash cushion for a particular household.
A resale comparison deserves its own review, not a borrowed pre-construction budget. Older condominium buildings warrant particular attention to reserves and assessments because structural obligations can generate special assessments or higher recurring charges.
Florida condominium buildings of three stories or more may be subject to milestone inspections and Structural Integrity Reserve Study requirements. Before the applicable review deadline, obtain the declaration, budget, financial statements, reserve information, insurance certificates and relevant inspection and reserve-study documents. Review pending assessments, litigation disclosures and board minutes as well.
These materials help identify obligations the asking price alone cannot reveal. Counsel should explain any assessment allocation or unresolved obligation rather than leaving it implicit in the buyer’s overall reserve estimate.
When reviewing Faena Residences Miami Downtown Miami alongside other candidates, compare more than headline prices. Put each proposed transaction on the same basis: deposits before closing, remaining balance, itemized closing charges and disclosed ownership obligations.
A disciplined Paris-to-Miami purchase is not built around guessing the perfect exchange rate. It rests on an agreement understood in detail and a funding plan reviewed against its obligations. That keeps the residence itself, rather than a last-minute liquidity decision, at the center of the move.
Explore your Downtown Miami second-home options with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Percentages, deadlines and construction triggers are contract-specific, so buyers need the actual written schedule for their purchase.
Illustrative schedules require approximately 30%–50% of the purchase price before closing. The executed agreement determines the actual amount.
One illustrative structure is 20% at contract, 10% at groundbreaking, 10% at top-off and 60% at closing. It is not a quotation for any project in the article.
The purchase schedule does not establish an ideal conversion date. Review exchange execution with qualified advisers against the contract’s actual dollar obligations.
If the exchange rate is expressed as dollars per euro, divide the dollar obligation by that rate. Applicable charges must be considered separately.
Not necessarily. Payments above 10% may be available for construction costs under applicable provisions, and counsel should verify the agreement and current legal requirements.
Approximately 3%–4.5% of the purchase price is an indicative new-construction range. Actual costs depend on financing, project terms and contractual allocations.
No. A developer-related fee may overlap with items already included, so an itemized estimate is needed to avoid double counting.
Yes, initial association or working-capital contributions may apply. Approximately two months of association charges is one illustrative example, not a universal requirement.
Review the declaration, budget, financial statements, reserves, insurance and relevant inspection and reserve-study documents. Pending assessments, litigation disclosures and board minutes also deserve attention before the applicable review deadline.