A coordinated residence and yacht plan starts with a realistic post-sale tax estimate, written berth terms, and a cash-flow calendar that extends beyond closing into the next assessment year.
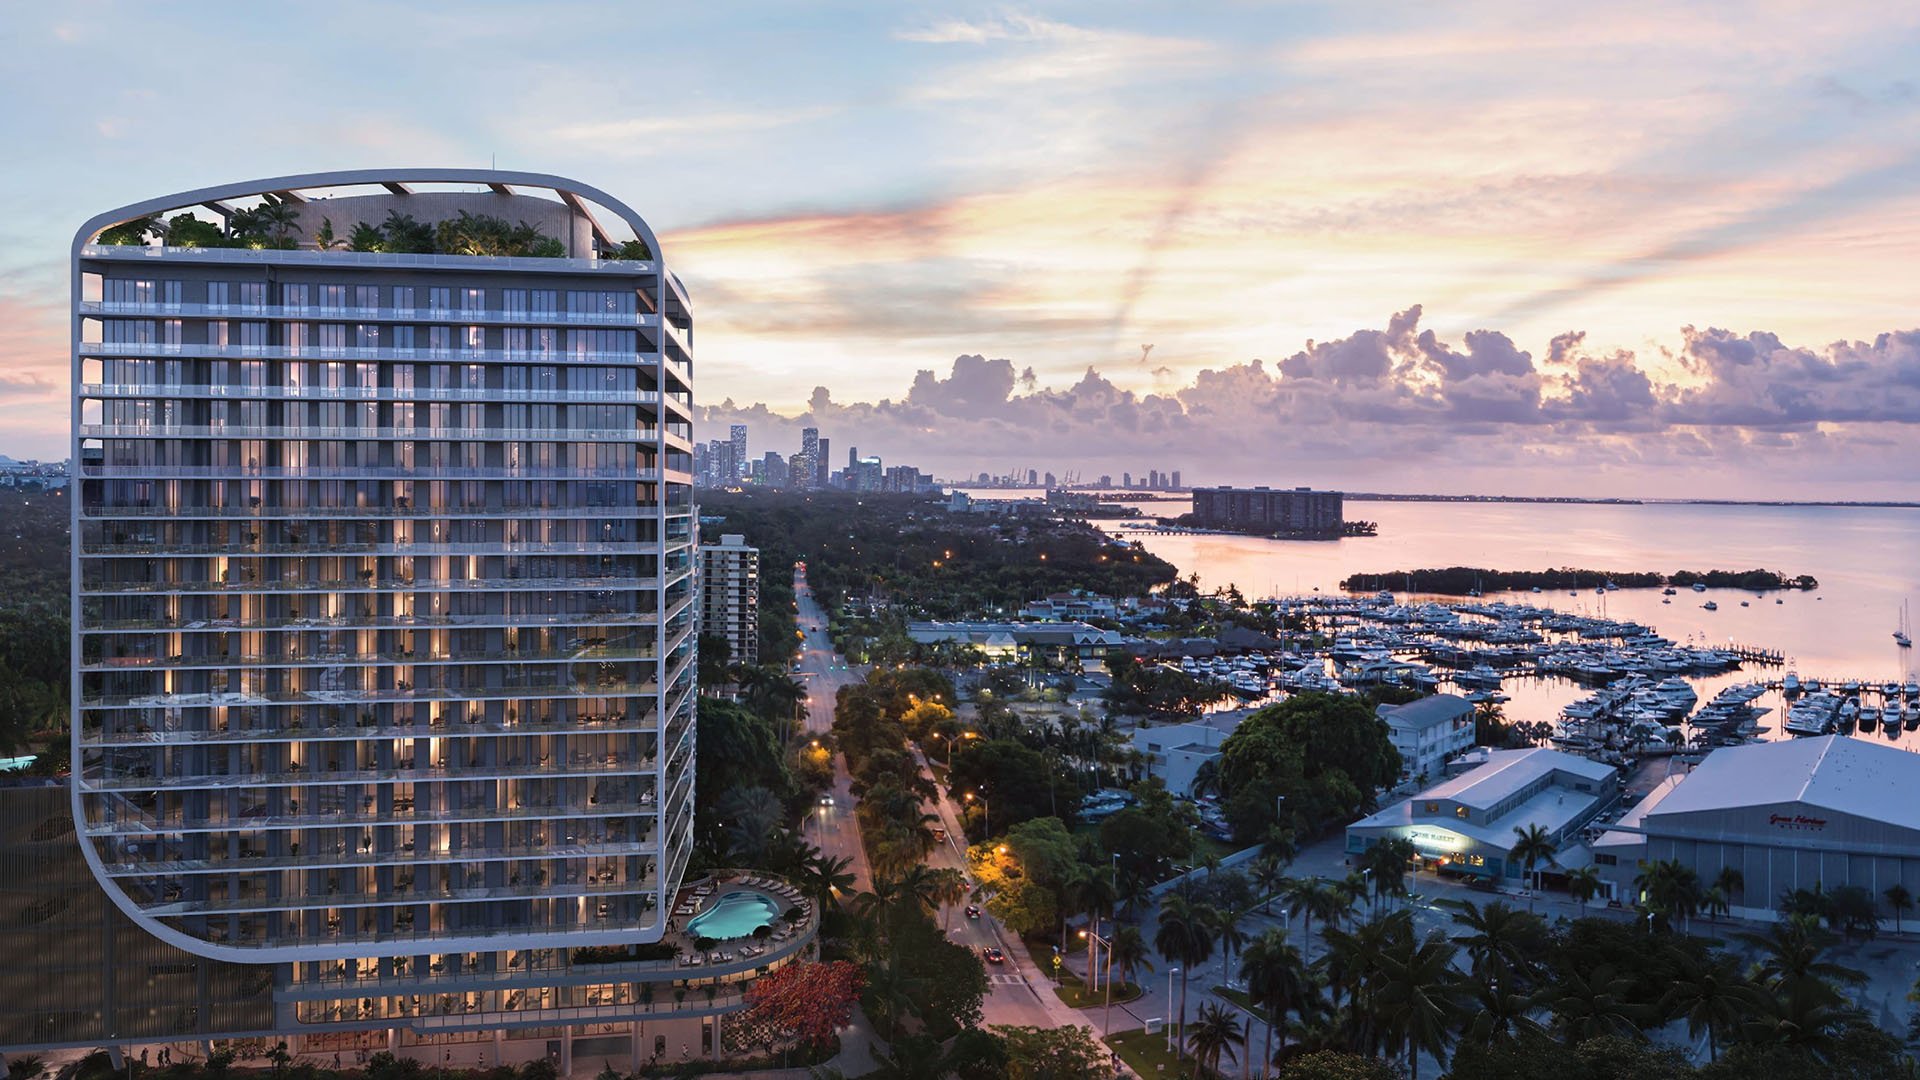
For a yacht owner, a South Florida residence is only part of the acquisition. The berth, its contractual availability, and the timing of both commitments deserve equal attention. The objective is not simply to close, but to begin ownership with a workable plan and sufficient liquidity for obligations that may arise afterward.
Treat the residence and marina as separate contracts within one financial calendar. A residential purchase does not, by itself, establish dockage rights. Nor is the seller’s property-tax bill a dependable forecast of the buyer’s carrying costs. Resolve both assumptions before they shape a purchase decision.
For a buyer considering Una Residences Brickell, the question extends beyond the residence: what written arrangements will support the intended boating routine, and what will ownership require after the next assessment? This is a diligence framework, not an assertion of berth availability at any particular project.
A sale generally resets a property’s assessed value to market value for the following tax year. The resulting bill can differ materially from the seller’s, particularly where a long-held homestead has benefited from Save Our Homes.
For qualifying homesteaded property, annual assessed-value increases are generally limited to 3% or the applicable Consumer Price Index change, whichever is lower. Over time, that protection can leave assessed value substantially below market value. Buyers should not assume the seller’s protected assessment becomes their own.
The distinction remains important after purchase: Save Our Homes is an assessment cap, not a guarantee that the total tax bill cannot rise by more than 3%.
Florida’s annual assessment date is January 1. Ask your advisers to distinguish the purchase-year position from the following assessment year, rather than present a single annual tax allowance. The planning horizon should extend through the next post-sale assessment, even when it falls outside the initial ownership budget.
Apply the same discipline to a Coconut Grove search that includes Vita at Grove Isle. Evaluate the residence on its merits, but underwrite taxes using the buyer’s anticipated assessment, not the seller’s existing bill.
Review closing prorations, lender escrow estimates, and the owner’s cash reserve separately. A tax figure on a closing worksheet does not confirm the eventual post-sale bill.
Ask the closing agent and, where applicable, the lender to identify the tax year, assessed value, and assumed exemptions underlying each estimate. Then request a comparison with a post-sale assessment scenario. Establish whether the estimate reflects the buyer’s likely circumstances or relies on the seller’s existing bill.
Useful instructions for the advisory team include:
Identify the contractual basis for the closing tax proration.
Explain the assumptions used for the initial escrow estimate.
Clarify how any later adjustment would be handled under the relevant documents.
Distinguish funds collected at closing from reserves the buyer should retain independently.
Do not presume a lender-specific escrow formula or a contractual proration outcome. An all-cash buyer can apply the same discipline through a separate tax reserve, without relying on a lender’s collection schedule.
If a berth is essential to the purchase, seek written confirmation before committing to the residence closing. Confirm availability for the intended dates, suitability for the vessel, acceptable dockage terms, deposits, and recurring charges. Ask counsel to review the agreement’s cancellation, insurance, renewal, and commencement provisions rather than assume customary terms.
For a buyer evaluating Onda Bay Harbor, choosing a residence and securing the required boating arrangement are distinct decisions. Keep anticipated dockage separate from confirmed contractual rights.
Coordinate the two calendars explicitly. Ask what happens if the residential closing moves, the vessel arrives earlier than expected, or the proposed berth is unavailable. Seek written treatment of those scenarios and identify any resulting cash exposure before making deposits.
A useful first-year plan distinguishes when money is committed from when it is spent. Organize residence and yacht obligations into four stages, labeling each estimate as confirmed, provisional, or awaiting documentation.
Contract stage.
Record residence and marina deposits, their due dates, and any restrictions on recovery identified in the agreements. Do not treat money committed under one contract as available for the other.
Closing stage.
Reconcile the residence funds required with prorations, any initial lender escrow collection, and dockage payments due in the same period. Have the team identify potential duplication between estimates and amounts already collected.
First 90 days.
Set aside a distinct allowance for household setup and yacht-related transition costs. Base it on actual quotations and operating requirements, rather than a generic percentage of the purchase price.
First-year carrying costs.
Maintain separate lines for residence expenses, recurring dockage, yacht operations, and the anticipated property-tax reset. Keep any additional reserve visible rather than burying it in a single monthly ownership figure.
For a West Palm Beach search that includes Alba West Palm Beach, this structure also helps prevent a marina-specific quotation from becoming an assumed regional rate. Budget against the intended berth’s written terms, not another facility’s schedule.
Buyers generally must apply for homestead exemption by March 1 for the relevant tax year. Miami-Dade offers online applications for homestead and other listed homeowner benefits. Confirm eligibility and the applicable year; do not assume every residential purchase qualifies.
An eligible owner may transfer up to $500,000 of a prior Florida homestead’s assessment difference to a new Florida homestead. This is an assessment benefit, not a $500,000 reduction in the tax bill. Miami-Dade requires homestead exemption to be established on the new property within three assessment years after abandoning the previous homestead exemption.
If the acquisition involves selling an existing home, check for deferred taxes as well. Under Miami-Dade’s homestead tax-deferral program, a sale can make deferred taxes plus interest due and payable. Account for that possibility before committing expected sale proceeds to the next closing or marina contract.
Miami-Dade mails its Notice of Proposed Property Taxes, commonly called the TRIM Notice, each August. Use it to compare the proposed assessment with the purchase model and review the treatment of anticipated benefits. Owners seeking a preliminary assessment review can contact the county property appraiser.
The strongest private-client plan assigns responsibility for each follow-up: tax review, benefit applications, escrow questions, and marina renewals. Closing should transfer ownership, not end financial oversight.
For a considered approach to South Florida residences and the lifestyle they must support, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationA long-held homestead may have an assessed value substantially below market value because of Save Our Homes. A sale generally resets assessed value to market value for the following tax year.
The annual assessment date is January 1. Buyers should distinguish purchase-year taxes from the following post-sale assessment year.
No. For qualifying homesteaded property, it generally limits annual assessed-value increases to 3% or the applicable Consumer Price Index change, whichever is lower, rather than capping the total tax bill.
Ask which tax year, assessed value, and exemptions support the estimate. Request a comparison with a post-sale assessment scenario rather than assuming the seller’s bill reflects future costs.
Buyers generally must apply by March 1 for the relevant tax year. Eligibility and the applicable year should be confirmed for the individual purchase.
An eligible owner may transfer up to $500,000 of a prior Florida homestead’s assessment difference. This is not a dollar-for-dollar reduction in the tax bill.
Homestead exemption must be established on the new property within three assessment years after abandoning the previous homestead exemption. Other eligibility requirements also apply.
Seek written confirmation of availability, vessel fit, dockage terms, deposits, and recurring charges. Have the actual agreement reviewed for cancellation, insurance, renewal, and commencement provisions.
Separate contract-stage spending, closing funds, first-90-day setup costs, and first-year carrying costs. Keep the anticipated tax reset and yacht operations visible as distinct budget items.
Compare the proposed assessment and anticipated benefits with the purchase model. Miami-Dade owners seeking a preliminary assessment review can contact the county property appraiser.