A discreet guide to exchanging into a South Florida residence, with precise distinctions between investment use, rental permission, entity records, bank due diligence, and federal tax deferral.
For a private client acquiring a South Florida residence through a tax-deferred exchange, the essential distinction is between a property that permits rentals and one held for investment. A desirable address, an entity on title, and a rental provision in condominium documents do not, by themselves, establish federal exchange qualification.
Section 1031 applies to qualifying real property held for investment or productive business use. Both the relinquished and replacement properties must satisfy that purpose. Personal property and intangible assets generally no longer qualify under the post-2017 rules. The planning question is not simply whether a residence can earn rent, but whether its intended and actual use support the exchange.
For a client considering 2200 Brickell, the property review should separate local rental permission from federal tax treatment. Confirm condominium restrictions, licensing, lender terms, and insurance independently. Inclusion in a residential shortlist establishes neither rental eligibility nor exchange suitability.
The federal dwelling-unit safe harbor provides a defined framework for demonstrating investment or business use. For a replacement dwelling, ownership must continue for at least 24 months immediately after the exchange. During each of the two consecutive 12-month periods, the dwelling must be rented to another person at fair-market rent for at least 14 days.
Personal use in each period must not exceed the greater of 14 days or 10% of the days rented at fair-market rent. These are separate annual tests, not totals that can be pooled across two years. Family occupancy and below-market use can count toward personal use, making an accurate calendar more valuable than an informal recollection of visits.
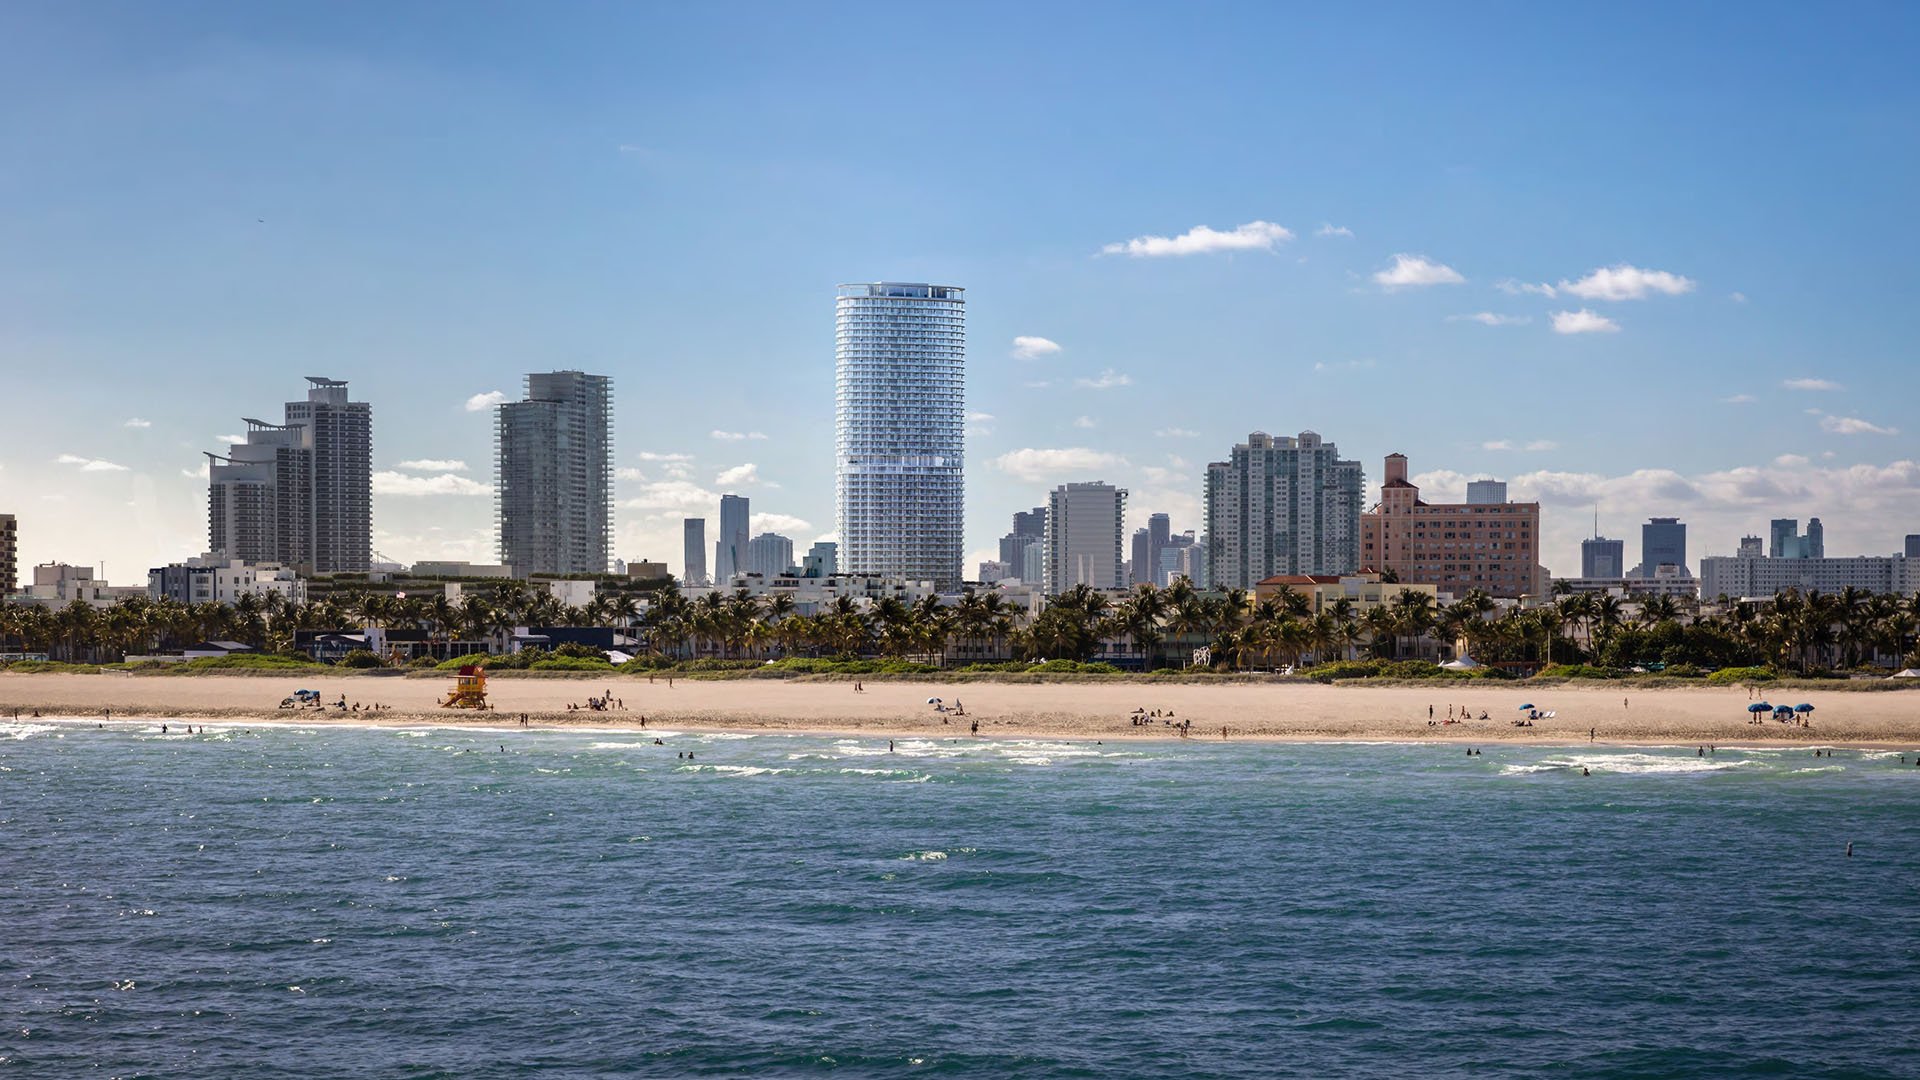
A Miami Beach search that includes Five Park Miami Beach should therefore begin with a realistic occupancy plan, not merely a preferred seasonal schedule. Preserve leases, rent receipts, market-rent support, management records, and personal-use calendars.
A relinquished dwelling has corresponding requirements during the 24 months immediately before the exchange. Missing the safe harbor does not automatically defeat qualification, but it removes that protection and leaves the outcome dependent on applicable law and the particular facts.
Replacement property must be identified in writing within 45 days after transfer of the relinquished property. It must be received by the earlier of 180 days after that transfer or the federal return due date, including extensions, for the transfer year. The return deadline can therefore shorten the acquisition window.
A qualified intermediary can hold proceeds and coordinate a deferred exchange under the applicable agreement. The structure must guard against actual or constructive receipt of sale proceeds. Receiving those proceeds directly can turn the transaction into a taxable sale.
Before the relinquished property's closing, align the intermediary, tax adviser, closing counsel, lender, and authorized entity signatories. Make the identification deadline, acquisition deadline, funding arrangements, and document responsibilities explicit. A residence that cannot be received within the applicable window warrants particular scrutiny, regardless of its appeal.
Section 1031 generally defers gain rather than eliminating it. The replacement property's basis reflects the deferred gain, carrying the tax history into the new holding. Cash or other non-like-kind property received in an otherwise qualifying exchange can trigger current gain recognition.
Mortgage relief can also produce taxable gain when it is not offset by replacement-property debt or other qualifying consideration. Have the tax adviser model the debt and consideration before agreeing to the final funding structure. The relevant comparison extends beyond the headline values of the two properties.
An exchange must be reported on Form 8824 with the federal return for the year in which it occurred. Keep the exchange agreement and closing documentation together with the figures supporting that filing. A coherent transaction file should connect the acquisition economics with the intended rental operation.
An entity can add a separate layer of documentation without resolving the underlying investment-use question. Before changing the taxpayer or entity holding title during an exchange, obtain transaction-specific tax advice. No single conclusion applies to every LLC structure or ownership change.
As a planning checklist, assemble formation documents, the operating agreement, ownership records, authorizing resolutions, tax identification details, beneficial-owner identification, and exchange documents. This is not a uniform federal filing requirement. It is a practical way to establish who owns the entity, who controls it, and who may authorize the transaction.
For an acquisition under consideration at Four Seasons Hotel & Private Residences Fort Lauderdale, the same discipline applies: reconcile the proposed titleholder, financing applicant, signatories, and exchange paperwork before closing. Ask counsel to confirm applicable entity-maintenance obligations, and keep records current when ownership or management changes.
Federal customer due diligence rules generally require covered financial institutions to identify and verify individuals owning 25% or more of a legal-entity customer, together with one individual exercising significant managerial control, subject to applicable exemptions and relief. Ownership and control are distinct inquiries.
Covered institutions must maintain written procedures reasonably designed to identify and verify beneficial owners. Their responsibilities also include understanding the nature and purpose of customer relationships, ongoing monitoring for suspicious activity, and relevant customer-information updates.
The 2026 account-opening exceptive relief permits institutions to limit repeated beneficial-owner identification and verification in specified circumstances, rather than automatically repeating it for every new account. It does not eliminate ongoing diligence or prevent a bank from requesting updated ownership and control information. Confirm the bank's actual requirements before relying on previously delivered documents.
Bank diligence and federal beneficial-ownership reporting are distinct regimes. A completed bank ownership certification is not proof that separate reporting obligations have been satisfied. Likewise, a reporting exemption should not be assumed to remove bank documentation requirements. Obtain an entity-specific assessment of current obligations and exemptions.
For a West Palm Beach search including Forté on Flagler West Palm Beach, coordinate that assessment with the ownership structure before acquisition. Rental permission, tax qualification, entity maintenance, and bank compliance each require their own review.
Reverse-exchange accommodation arrangements can involve an exchange accommodation titleholder and a qualified exchange accommodation agreement, with a 180-day safe-harbor limit. They require specialized review before an acquisition-first commitment. A private letter ruling describing a particular arrangement is not generally precedential authority or universal approval of another client's structure.
The private-client objective is a residence whose ownership, use, financing, and documentation remain consistent with the exchange plan after closing-not simply an elegant acquisition on closing day.
For a discreet conversation about your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Both the relinquished and replacement properties must be held for investment or productive business use, and rental permission alone does not establish that purpose.
It must be owned for at least 24 months immediately after the exchange. Rental and personal-use conditions must also be satisfied in each of the two 12-month periods.
Each qualifying 12-month period requires at least 14 days rented to another person at fair-market rent. Personal use must not exceed the greater of 14 days or 10% of fair-market rental days.
Yes, family occupancy and below-market use can count toward the personal-use limit. Preserve a detailed calendar alongside leases and rent records.
No. Qualification then depends on applicable law and the specific facts rather than safe-harbor protection.
Identify replacement property in writing within 45 days after transferring the relinquished property. Receive it by the earlier of 180 days after transfer or the federal return due date, including extensions, for that year.
A qualified intermediary can hold proceeds and coordinate a deferred exchange. Actual or constructive receipt of the proceeds can turn the transaction into a taxable sale.
Section 1031 generally defers gain rather than eliminating it. Cash, non-like-kind property, or unoffset mortgage relief can trigger current gain recognition.
Covered institutions generally identify and verify owners holding 25% or more and one individual with significant managerial control, subject to exemptions and relief. They may also seek updated information under ongoing compliance procedures.
No. It limits repeated identification and verification in specified circumstances, but does not eliminate ongoing bank diligence or determine separate federal beneficial-ownership reporting obligations.