A practical framework for aligning a South Florida purchase with actual occupancy, mortgage eligibility, appraisal exposure, title ownership, and negotiated closing protections.
The distinction between a Florida primary residence and a South Florida second home begins with a practical question: where will you actually live? A property that becomes your principal home calls for a different financing and residency analysis than one reserved for seasonal visits. The choice should follow your intended use, not your preferred loan terms or tax treatment.
For a buyer considering The Residences at 1428 Brickell, the first discussion should address occupancy, rental intentions, and ownership structure-not financing terms. Align those decisions early, then ask the lender and Florida counsel to evaluate them together. Mortgage classification, homestead eligibility, title ownership, and contractual closing rights are related, but not interchangeable.
Conventional agency mortgage guidelines distinguish principal residences, second homes, and investment properties. A principal residence is the property the borrower occupies as their primary home-not simply the property they elect to finance on primary-residence terms.
Occupancy and transaction type affect financing eligibility. A written comparison is therefore more useful than a general assurance that one category is preferable. Ask the lender to compare down payment, reserves, pricing, qualification, appraisal requirements, and condominium review for each scenario that genuinely fits your plans.
These agency requirements are not universal mortgage rules. Jumbo, portfolio, and other programs may differ. For a luxury purchase, identify the program being offered before applying a conventional rule to the transaction. Do not assume a universal second-home pricing premium or identical requirements across lenders.
Under this conventional agency framework, a qualifying second home must be a one-unit dwelling suitable for year-round occupancy, occupied by the borrower for part of the year, and under the borrower’s exclusive control. Timeshares and arrangements that give a management firm control over occupancy do not meet those requirements.
Rental activity warrants a precise conversation. Rental income cannot be used to qualify the borrower under this second-home framework. Receiving rent does not automatically eliminate second-home treatment, however, provided that income is excluded from qualification and all other requirements remain satisfied.
When considering The Perigon Miami Beach, apply the same discipline: describe your intended personal occupancy and any proposed rental arrangement to the lender. A project name or location does not establish eligibility. Ask counsel to review any occupancy-management agreement before relying on a second-home classification, and request the lender’s determination for the specific loan program.
Florida homestead eligibility rests on qualifying ownership and good-faith permanent residence-not purchase price or purchase timing alone. A primary-residence mortgage classification does not, by itself, establish that the separate homestead requirements have been met.
In Miami-Dade, eligibility requires legal or equitable title and permanent residence as of January 1. Supporting evidence can include Florida identification and other residency records required by the county. The deed or other instrument supporting ownership must also be recorded in the county’s official records before the exemption is allowed.
For a buyer weighing a permanent move to Coconut Grove and considering Park Grove Coconut Grove, the practical task is to align actual residence, ownership documentation, and the relevant eligibility date. Verify the exemption applicable to the tax year with the county rather than building a budget around a general headline amount. Seasonal use alone is not a substitute for permanent residence.
Ask the lender when valuation can be ordered, which appraisal requirements apply, and how a valuation below the contract price would affect the proposed financing. Request a written explanation of the resulting cash requirement rather than assuming the original financing plan will hold.
Next, have counsel address that possibility in the purchase contract. Consider negotiating an appraisal contingency, a defined opportunity to renegotiate, or a termination remedy. These are requested protections, not automatic rights. Their availability and effect depend on the executed agreement.
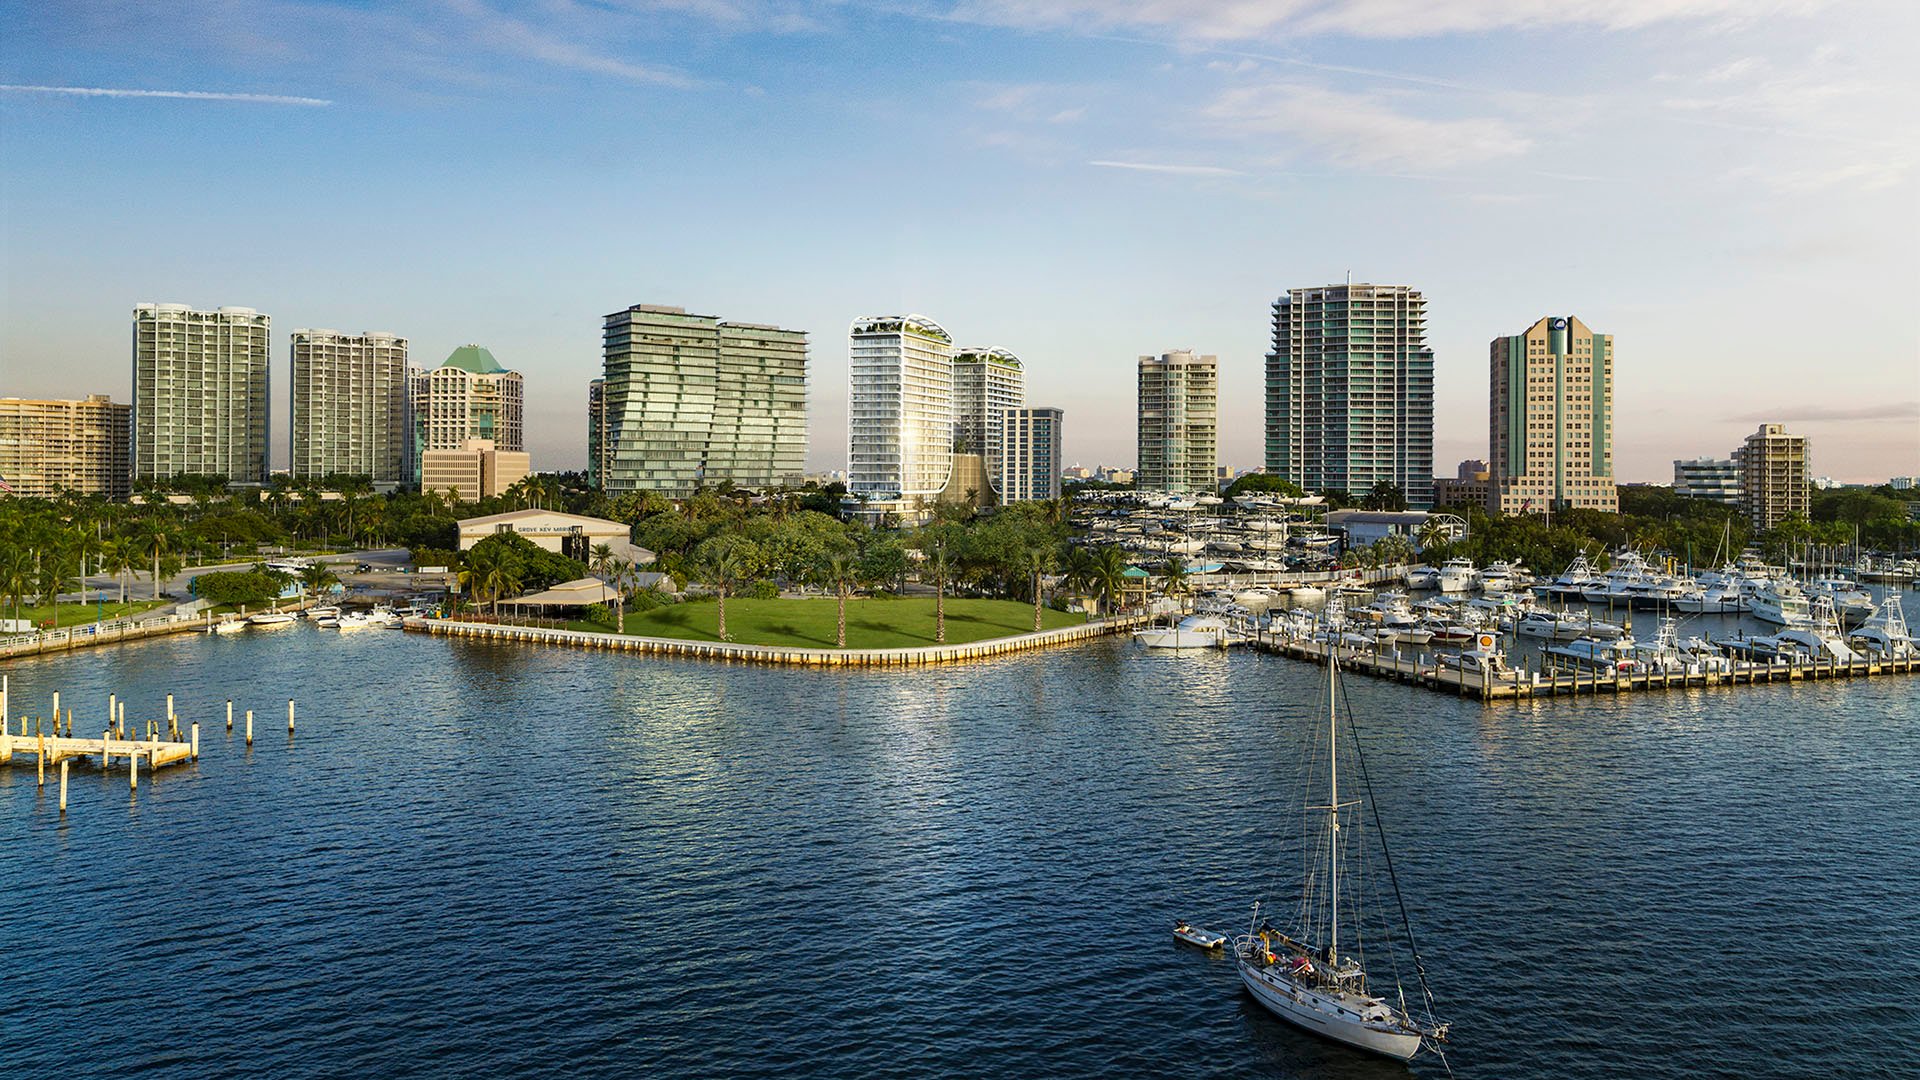
Waterfront appeal should not replace a financing stress test. Set a ceiling on the additional cash you would be willing to contribute, and discuss it before a valuation issue becomes urgent. Preparing for either result does not require assuming a particular luxury-property adjustment or valuation outcome.
Even a well-qualified buyer should ask whether the condominium meets the lender’s requirements. Association insurance coverage and financial health can create mortgage-approval barriers separate from the borrower’s income, assets, or credit profile.
For a Fort Lauderdale purchase, including consideration of Four Seasons Hotel & Private Residences Fort Lauderdale, request project review early. This is a diligence recommendation, not a statement about that property’s eligibility. Ask the lender which association documents it needs, who will obtain them, and when the review should be completed.
Keep borrower approval, valuation, and condominium review as separate checkpoints. Request written confirmation of each; progress on one does not confirm all three.
Review individual, joint, trust, and LLC ownership with both the lender and Florida counsel before finalizing the proposed structure. Ask whether the intended borrower and title holder are acceptable under the actual loan program and consistent with the intended homestead application.
Trust ownership requires particular documentary attention: Miami-Dade requires supporting trust documentation for a homestead claim involving property held in trust. Do not assume every trust arrangement receives identical treatment.
Likewise, do not treat LLC ownership as an automatic solution for financing, homestead, or creditor protection. Obtain transaction-specific advice, including a review of any proposed ownership change after closing. The objective is a structure that supports the intended use without relying on untested assumptions.
Closing flexibility should be explicit. Ask counsel to coordinate financing deadlines, appraisal remedies, association-document review periods, and any extension rights with the lender’s anticipated schedule. If an extension matters, negotiate its conditions and duration. Do not assume a delay creates a right to more time.
Before signing, assemble one coherent plan: truthful occupancy classification, written financing terms, a defined appraisal-risk budget, acceptable title ownership, and a realistic closing timetable. The practical choice is the one that fits both your life and the transaction you can document.
For a discreet conversation about your South Florida residential search, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationNo. Principal-residence classification must reflect the property you actually occupy as your primary home, subject to the applicable loan program.
Under the conventional agency framework discussed here, it must be a one-unit, year-round dwelling occupied by the borrower for part of the year and under the borrower’s exclusive control.
Rental income cannot be used for qualification under the second-home framework described here. Receiving rent does not automatically disqualify the property if all other requirements are met and the income is excluded.
No. Jumbo, portfolio, and other loan programs may use different requirements, so confirm the rules for the specific program being offered.
No. Homestead requires a separate assessment of qualifying ownership and good-faith permanent residence, along with the applicable documentation and timing requirements.
Miami-Dade requires legal or equitable title and permanent residence as of January 1 for homestead eligibility. Supporting residency documentation is also required.
Trust ownership requires review of the ownership arrangement and applicable eligibility requirements. Miami-Dade requires supporting trust documentation for such applications.
Yes. Association insurance coverage and financial health can create mortgage-approval barriers independently of the buyer’s qualifications.
Ask the lender how a lower valuation would change financing and required cash. Have counsel negotiate any desired appraisal contingency or remedy before signing.
Do not assume it does. Any extension rights, including their conditions and duration, should be addressed expressly in the purchase agreement.