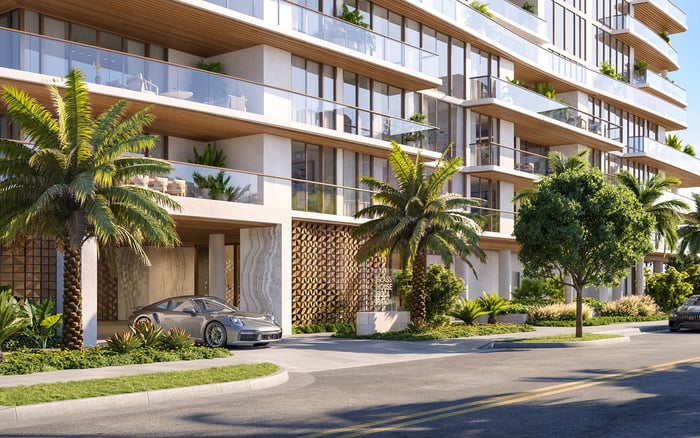
ALINA buyers should budget beyond monthly dues. A practical framework separates recurring association costs, confirmed upfront contributions and purchase deposits, while identifying the questions that must be resolved before closing.
At Alina Residences Boca Raton, the appeal is a downtown condominium setting with resort-style amenities and buildings at 200, 210 and 220 SE Mizner Boulevard. The financial question is more precise: how much cash should a buyer allocate beyond the purchase price, and when must it be available?
Monthly association dues are only one component. An upfront capital contribution can increase the cash due at closing without appearing in the monthly figure. A payment described as working capital also needs clarification before it enters the budget. The label alone establishes neither its amount nor its purpose or relationship to other charges.
This guide covers association costs for the first 12 months after closing, plus applicable upfront association charges paid at closing. Earlier purchase deposits belong in a separate acquisition timeline. Keeping the two distinct clarifies the first-year requirement without understating cash already committed.
Disclosed monthly dues at ALINA vary materially by residence. These four snapshots show why a community-wide estimate cannot replace the figure for the unit under consideration:
| Residence | Disclosed monthly dues | First 12 months if unchanged | | --- | ---: | ---: | | 220 SE Mizner Boulevard #411 | $2,299 | $27,588 | | 220 SE Mizner Boulevard Unit 220 | $2,753 | $33,036 | | 220 SE Mizner Boulevard Villa 101 | $3,852 | $46,224 | | 210 SE Mizner Boulevard #604 | $5,537 | $66,444 |
These figures reflect different dates; they are not verified current quotes. Villa 101’s HOA and capital-contribution information is expressly subject to change and requires verification. Obtain a current, written, unit-specific breakdown before treating any annualized amount as a funding commitment.
The annual column is arithmetic, not a forecast. It assumes monthly dues remain unchanged throughout the period and excludes the upfront contribution and any separately confirmed association charges.
For the new-construction offering at 220 SE Mizner Boulevard PH904, HOA and capital contribution are due at closing. That establishes a payment obligation for that offering, but not an amount a buyer can budget: neither a dollar figure nor a calculation formula is specified.
Do not budget the contribution as two or three months of dues, assume it is automatically five figures, or apply the PH904 terms to every ALINA purchase. An unpriced obligation should remain explicitly unresolved in the worksheet, not entered as zero.
Request written confirmation of the amount or formula, recipient account, permitted uses and applicability to the transaction. Establish whether the payment is separate from prepaid dues and whether another closing line represents the same obligation.
Treat working capital with the same precision. If the term appears in the transaction documents, determine whether it describes the disclosed capital contribution or a separate payment. That relationship is not established for ALINA. Do not assume working capital replaces reserves, and do not add two differently named charges until their relationship is clear.
The association planning model is straightforward:
First-12-month association subtotal = 12 months of applicable dues + confirmed upfront contribution + separately confirmed association charges.
For Villa 101, the illustrative starting point is $46,224 + the confirmed contribution, assuming unchanged monthly dues. Add any distinct, confirmed association charges. This is an association subtotal, not the buyer’s total ownership cost.
If dues collected at closing cover months already included in the 12-month calculation, they change the timing of the cash outflow, not the total dues allowance. Record them at closing in the cash schedule, then reduce the corresponding post-closing dues payments. Otherwise, a seemingly conservative budget counts the same expense twice.
Keep other ownership and acquisition categories outside this subtotal. Obtain transaction-specific estimates for taxes, insurance, financing costs where applicable, closing expenses and personal setup costs. Neither the dues figure nor the contribution terms establish those amounts.
A useful purchase worksheet has three clearly labeled columns: cash already deposited, remaining cash due at closing and expenses payable after closing. Each payment should appear once, with its purpose and any applicable credit identified.
A historical ALINA payment schedule called for 30% at contract execution, another 10% ten days after commencement of the top-slab pour, and the balance at closing. This is not a confirmed current schedule. The executed agreement and current closing statement should determine the buyer’s actual payment timing.
The principle is simple: deposits credited toward the purchase price reduce the remaining purchase balance. They are not additional costs to add to the full price. Association contributions, by contrast, require separate treatment unless the transaction documents explicitly identify an applicable credit.
The same distinction is useful when comparing ALINA with Glass House Boca Raton. Compare documented cash schedules rather than importing one project’s deposit or contribution assumptions into another.
For #604, disclosed HOA inclusions cover common areas, elevators, janitorial services, grounds and structural maintenance, management, parking, pest control, pool and recreational facilities, roof maintenance, sewer, trash and water. This gives useful context for the recurring charge.
It does not establish identical coverage for every residence or mean that every optional service is included. Request the applicable inclusion schedule and identify any separately charged services relevant to your intended use.
For buyers also considering The Residences at Mandarin Oriental Boca Raton, apply the same discipline: compare documented inclusions alongside dues and upfront payments. A monthly figure is most useful when its scope is clear; do not presume an equivalent fee structure.
The PH904 new-construction terms do not establish whether a contribution applies on resale. Confirm the obligation for the actual transaction rather than treating a previous offering’s terms as a community-wide transfer rule. For a second-home budget, distinguish confirmed fixed obligations from discretionary spending rather than scaling the dues allowance to planned occupancy.
Before authorizing closing funds, reconcile the current dues figure, contribution terms, prepaid periods, distinct association charges and purchase-price credits. Keep unresolved items explicit. The goal is not merely a larger cash cushion, but a clear schedule showing what is payable, why it is payable and when it leaves the account.
For a considered approach to your Boca Raton purchase, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationALINA is a luxury condominium community in downtown Boca Raton, with buildings at 200, 210 and 220 SE Mizner Boulevard and resort-style amenities.
The association budget covers the first 12 months after closing plus applicable upfront association charges paid at closing. Earlier purchase deposits are tracked separately.
Villa 101’s disclosed dues are $3,852 per month, equivalent to $46,224 over 12 months if unchanged. Current costs require verification.
No. They are snapshots from different dates, so buyers should obtain a current written breakdown for the specific residence.
PH904 has an explicit new-construction disclosure stating that HOA and capital contribution are due at closing. It does not establish the requirement for every ALINA transaction.
The disclosure does not specify an amount or calculation formula. A numerical allowance requires written transaction-specific confirmation.
That relationship is not established by the available disclosures. Confirm the payment’s purpose, recipient account and whether working capital describes the same obligation or a distinct charge.
Dues paid at closing for months within the first 12-month period belong within that period’s dues total. Record the closing payment and reduce the corresponding post-closing payments to avoid double-counting.
The earlier 30% and 10% staged payments are historical marketing, not a confirmed current schedule. Use the executed agreement and current closing statement for actual payment timing.
No. Taxes, insurance, applicable financing costs, closing expenses and personal setup costs need separate transaction-specific estimates.