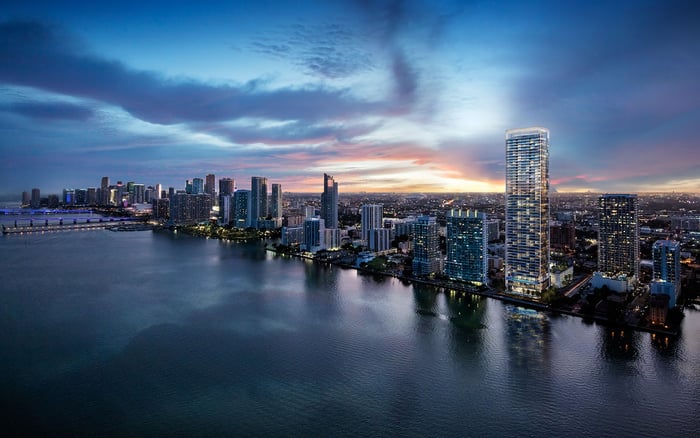
A disciplined family-office purchase plan connects Design District living with individualized residency records, title review, residence management, and written storm authority before closing.
A Miami Design District purchase should begin with a family decision, not simply a property shortlist: will this be a seasonal retreat, a permanent home, or a residence used differently by several family members? The answer shapes the ownership review, travel calendar, management brief, and emergency arrangements. For a family office, the objective is effortless use backed by clearly assigned responsibilities.
When considering Kempinski Residences Miami Design District, separate the appeal of the address from the operating questions that need documented answers. Who will occupy the residence? Who may authorize work? What happens when the principal is abroad? These are purchase criteria, not details to defer until the keys arrive.
The framework below is a suggested operating plan. Residency, homestead, and condominium rules require separate legal and tax review; none should be inferred from a project's name or presentation.
Write a concise acquisition brief identifying the intended users, expected periods of occupation, proposed ownership, and annual operating budget. Distinguish the family's lifestyle preferences from its tax objectives. A shared household calendar can organize visits, but it cannot establish each user's residency position.
Florida residency is program-specific. Requirements for taxes, tuition, and other purposes are not interchangeable, and ownership alone does not establish a person's true, fixed, and permanent home. A seasonal residence can remain exactly that without being presented as evidence of a completed residency change.
Apply the same brief when evaluating Miami Tropic Residences. Ask which documents and arrangements would support the intended use rather than assuming that branding supplies a private management service. The purchase decision should reflect both how the family wants to live and what its advisers can substantiate.
Do not treat 183 days as a universal Florida residency test. The analysis depends on the jurisdiction and tax question involved. Have tax counsel identify the rules applicable to each family member before turning a seasonal itinerary into a compliance calendar.
As an operating practice, maintain separate travel records for each relevant user. Record actual arrivals, departures, and locations; retain supporting travel documentation; and reconcile changes after each visit. A planned itinerary and an actual travel record serve different purposes.
Assign one family-office contact to coordinate those records with advisers. That person should flag proposed schedule changes for review, not independently decide how a jurisdiction counts a day. Document any storm-related relocation and refer it for advice rather than assume a particular tax treatment.
Keep multistate income-tax residency, the homestead property-tax exemption, and creditor-protection questions in separate files. A conclusion in one does not resolve the others.
Florida's homestead property-tax exemption generally requires qualifying legal or beneficial title and permanent residence by January 1. Qualifying residence may include that of a legal or natural dependent. A buyer who purchases and establishes permanent residence by that date may qualify for the tax year's exemption after applying to the county property appraiser.
January 1 is an eligibility reference point, not a substitute for the application process. Before scheduling a closing around that date, ask counsel to review whether the intended ownership and actual residential circumstances support the proposed claim.
Trust or entity ownership deserves particular attention before closing. Assume neither automatic eligibility nor automatic disqualification; qualifying title and residence must be examined.
Build a residency file alongside the closing file. The homestead application requests information concerning driver licenses, vehicle registration, and voter registration. A purchase contract is not the complete record. Supporting documents should reflect the underlying circumstances, not replace them.
For a condominium acquisition, examine governing documents, financial records, insurance policies, minutes, and applicable inspection and reserve-study materials. Associations can collect assessments and maintain, repair, and replace common elements or association property. Those responsibilities do not eliminate the need to define who looks after the private residence.
If the search extends to Edgewater and Villa Miami, carry the same diligence questions into the comparison. Evaluate the applicable documents and proposed management arrangements without assuming that services, access procedures, or emergency protocols are identical across properties.
A suggested residence-manager brief should cover vacant-home inspections, maintenance scheduling, vendor access, humidity monitoring, inventory, and incident reporting. Specify the inspection cadence, evidence of completion, and escalation route. Confirm how keys and credentials are controlled and how vendors obtain permitted entry.
Define arrival and departure procedures as well: preparation for occupancy, open maintenance items, and the handover to vacant-home care. Require written confirmation of who performs each task. Service expectations are useful only when responsibility is clear.
Review building insurance alongside the owner's insurance arrangements. Association property insurance does not cover every unit-owner exposure and should not be treated as complete protection for the residence and its contents.
Prepare a written authorization matrix naming the primary emergency decision-maker and backup approver, with routine spending limits and emergency spending authority. Assign association communications, insurer notifications, vendor coordination, and relocation arrangements to identified people. Establish what the team should do if an approver cannot be reached.
Obtain the building's hurricane-protection specifications before planning protective work. Residential condominium boards must adopt building-specific specifications, which may address color, style, and other relevant requirements. Private instructions should accommodate those requirements rather than presume unrestricted installation rights.
The family-office matrix governs its own team. It does not override evacuation orders, association emergency powers, or access restrictions. Under applicable declared-emergency conditions, disaster plans may include shutting down elevators, utilities, security, or air-conditioning systems. Entry or occupancy may also be restricted subject to statutory conditions, and an association may require evacuation when a mandatory order applies.
Plan for financial consequences as well as physical access. Applicable emergency powers can permit removal of wet or damaged materials, including some normally within the owner's responsibility. They can also permit special assessments without an owner vote and, under statutory conditions, borrowing secured by association assets when operating funds are insufficient.
Before the first stay, consolidate the ownership review, individual travel-record process, association documents, insurance review, management brief, and storm authorization into one controlled operating file. Identify unresolved decisions and assign an accountable person to each.
Readiness is not measured by the volume of paperwork. It is whether the family can arrive comfortably, leave confidently, and make timely decisions without confusing personal authority with the building's legal powers.
For a discreet conversation about aligning a Miami residence with your family's purchase priorities, connect with MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationProperty ownership alone does not establish permanent residency. Florida residency requirements vary by program and must be evaluated for the particular purpose involved.
No universal 183-day Florida residency test should be assumed. Advisers should identify the jurisdiction-specific rules relevant to each individual's tax position.
Separate records are a useful operating practice because family members may have different travel patterns and tax circumstances. A household booking calendar does not replace individual records.
Florida's homestead property-tax exemption generally requires qualifying title and permanent residence by January 1. The buyer must also apply to the county property appraiser.
No. Counsel should review the proposed title structure and residential circumstances before closing rather than assume eligibility.
Review governing documents, financial records, insurance policies, minutes, and applicable inspection and reserve-study materials. Define private residence-management responsibilities separately.
A suggested written brief covers vacant-home inspections, maintenance, vendor access, humidity monitoring, inventory, and incident reporting. It should also specify spending authority and escalation procedures.
Association property insurance does not cover every unit-owner exposure. Review it alongside the owner's insurance arrangements to identify coverage needs.
Its internal authorization cannot override evacuation orders or applicable association access restrictions. Ownership does not guarantee continuous access during a storm.
Applicable association emergency powers can permit special assessments without an owner vote. Subject to statutory conditions, they can also permit borrowing secured by association assets when operating funds are insufficient.