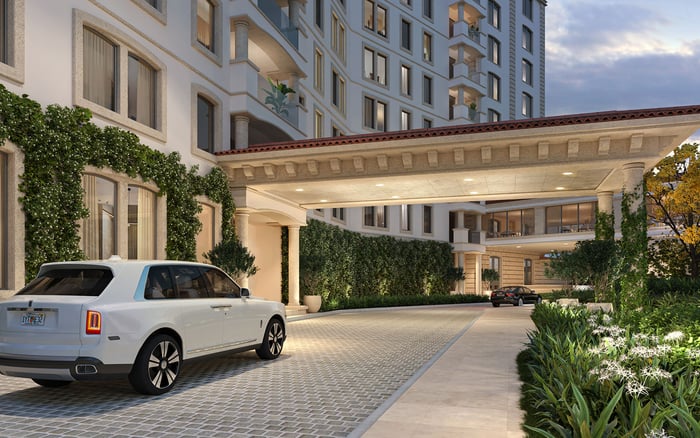
A document-first checklist for Palazzo della Luna buyers, covering move reservations, vendor insurance, refundable deposits, and the boundary between association and unit-owner coverage.
A carefully planned arrival should feel effortless. For a buyer at Palazzo della Luna Fisher Island, that ease begins before the first delivery-with a file establishing who may enter, what insurance management requires, which payments are refundable, and how any damage will be documented.
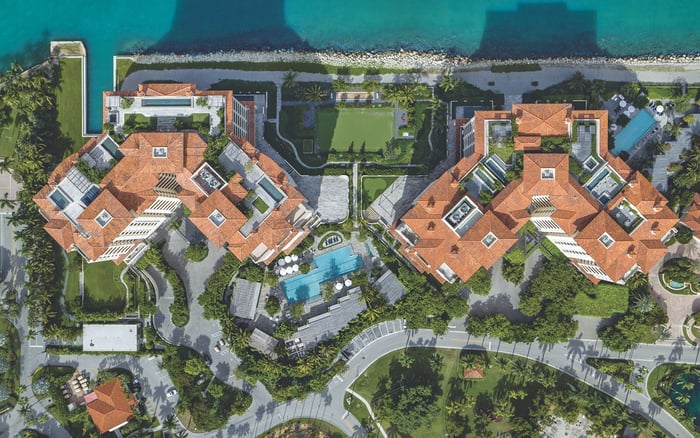
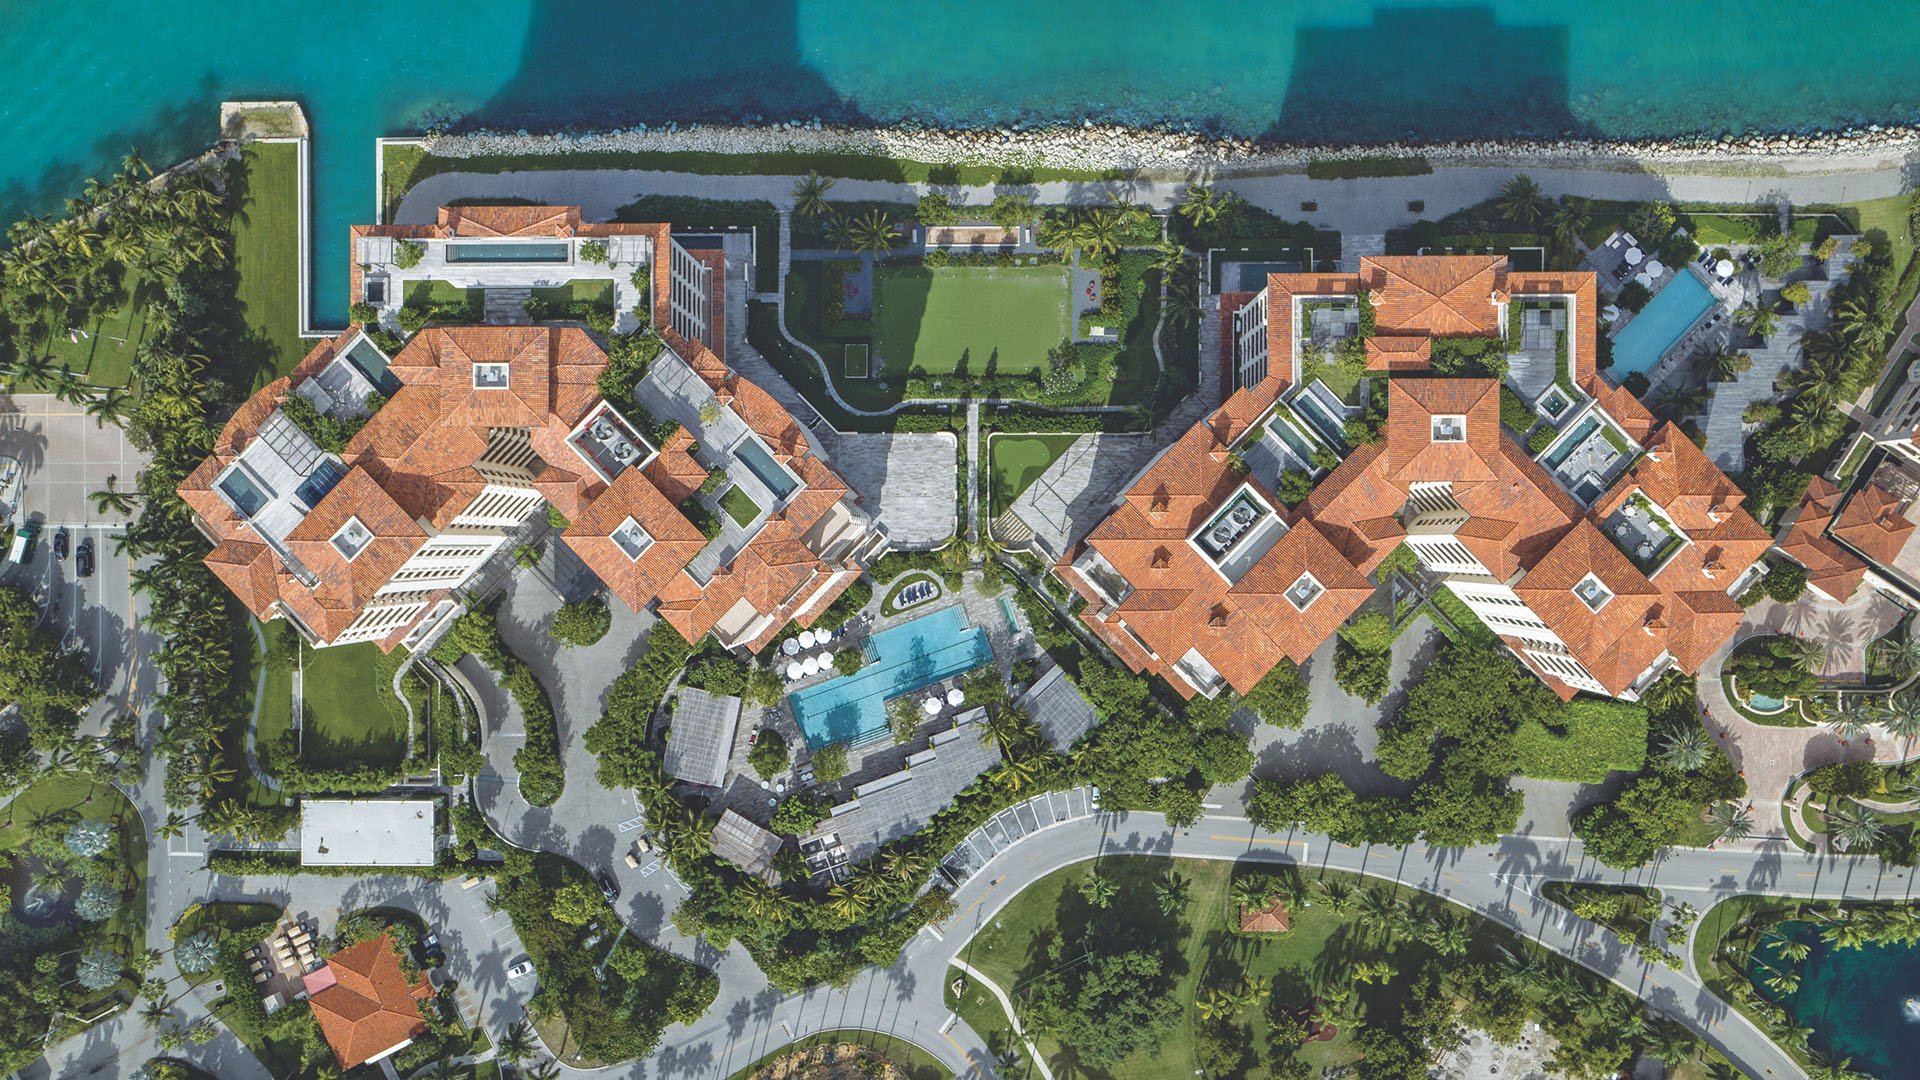
Palazzo della Luna's listed address is 6800-6899 Fisher Island Drive, Fisher Island, FL 33109. The address identifies the destination, not the operational terms of a move. Deposit amounts, refund deadlines, insurance limits, move hours, elevator rules, and required endorsements should all be confirmed in current written instructions.
The central principle is simple: a reservation, an insurance certificate, and a damage deposit answer different questions. None substitutes for the others.
Request the condominium's declaration, bylaws, rules, and amendments, followed by its current move-in and delivery packet. An initial overview may help orient the buyer, but the working checklist should rest on the governing documents and management's written directions.
Ask management to identify the version currently in use and clarify any apparent conflicts between forms. Keep the response with the purchase and move records so the buyer, attorney, mover, and household representative work from the same instructions.
For purchasers also considering Palazzo del Sol Fisher Island, the same document-first discipline applies, but policies should never be carried over from one condominium to another. A familiar location or comparable residence does not establish identical insurance, scheduling, or deposit terms.
Ask which activities require separate scheduling: the household move, furniture deliveries, repairs, maintenance, and contractor visits. Confirm the required notice period, permitted hours, elevator arrangements, access procedures, and the person authorized to approve the booking.
Obtain written confirmation identifying the approved date, activity, vendor, and any outstanding conditions. Before committing to a nonrefundable vendor reservation, ask whether approval depends on cleared funds, accepted insurance documents, or another step.
Do not assume a notice period used elsewhere applies here. Ask when a reservation becomes final and what happens if the closing date changes. If several vendors will attend on different days, confirm whether each visit needs its own approval. This keeps a furniture installation from being mistaken for an already authorized household move.
Request management's written insurance requirements before asking the mover or contractor to issue a Certificate of Insurance. The certificate should identify the policies, issuing insurers, policy numbers, coverage limits, and effective dates. Compare those details with the planned work and scheduled arrival.
Ask management to specify the commercial general-liability limit and exact additional-insured wording, including the legal names of any entities to be included. Clarify which endorsements are required rather than assuming a certificate alone completes the submission.
Also ask whether vendors with employees must provide workers' compensation coverage and whether vehicle use triggers automobile-liability requirements. Confirm any insurer eligibility standards management applies. These are questions for this building, not universal private-condominium requirements.
Before the move, obtain written acceptance of the submitted insurance file. An emailed certificate establishes submission; it does not establish management's acceptance for the scheduled activity.
Request a written fee and deposit schedule distinguishing refundable security from nonrefundable charges. Ask whether the owner, mover, and contractor face separate deposits, who must pay each one, and who receives any refund.
The checklist should address custody of the funds, payment method, refund conditions, permitted deductions, inspection procedures, and repayment timing. Ask what documentation accompanies a deduction and how the payer may challenge it. The word refundable is useful only when the release conditions are clear.
Clarify how damage exceeding the deposit would be handled. Do not assume the deposit caps responsibility or replaces insurance; have the relevant language reviewed. If the documents contain an unusual indemnity, waiver, additional-insured provision, or broad deduction right, ask the buyer's attorney or insurance adviser to assess it before signing.
Ask management how pre-move and post-move inspections are conducted, who participates, and which areas are included. Request a way to record existing damage before work begins, particularly along any approved delivery route.
As a practical safeguard, preserve dated photographs and a written condition record, subject to building rules. Ask management to acknowledge any pre-existing marks or defects, and retain that acknowledgment with the reservation and deposit receipt.
After the activity, request the inspection outcome and written confirmation of whether any damage is alleged. If a deduction is proposed, ask for the location, supporting photographs, repair description, and cost documentation. A clear record helps distinguish a newly claimed incident from an earlier condition without presuming responsibility.
Move-in insurance is only one part of ownership planning. Request the association's master property-insurance summary or declarations page and have an insurance adviser review how it relates to coverage for the residence.
Florida condominium law distinguishes association-insured property from specified unit-owner property and finishes. Buyers should not assume the master policy covers everything inside the home. Ask the adviser to identify the relevant boundaries and any coverage questions raised by the planned furnishings, finishes, or work.
A purchaser comparing The Residences at Six Fisher Island should bring the same question to that review without assuming shared policy terms. Compare the clarity of each ownership file, not an inferred uniform standard across Fisher Island.
If an association's vendor damages the residence during repairs, request the contractor agreement, scope of work, and relevant insurance information. Those documents can help establish responsibility and identify potentially available coverage; they do not, by themselves, resolve a claim.
Preserve communications, photographs, inspection records, and any repair proposals. Ask the attorney or insurance adviser to review the contractual and coverage questions before accepting a deduction, release, or proposed resolution.
The closing discipline is straightforward: assemble the governing documents, accepted vendor insurance, confirmed reservation, payment receipts, condition record, and refund terms in one accessible file. Before booking movers, resolve the operational questions in writing. The result is not merely a tidier transaction, but a more controlled transition into the residence.
For a discreet perspective on South Florida ownership, explore MILLION.
If branded residences are on your mind — as a home or as an allocation — we would be glad to share what we are seeing, privately.
Begin a quiet conversationRequest the declaration, bylaws, rules, amendments, and current move-in and delivery packet. Use those documents and management's written instructions to establish the applicable requirements.
Confirm the current notice period directly with management in writing. Do not apply another condominium's reservation timetable.
It should identify the policies, issuing insurers, policy numbers, coverage limits, and effective dates. Compare those details with management's written requirements.
Ask management for Palazzo della Luna's current commercial general-liability requirement. A limit used by another condominium does not establish this building's minimum.
Request management's exact additional-insured requirements and legal entity names. Have the vendor's insurance representative address any required wording and endorsements.
Ask whether workers' compensation applies to vendors with employees and whether automobile liability is required for vendors using vehicles. Verify both against the building's written instructions.
Obtain the current written fee and deposit schedule from management. Confirm whether separate owner, mover, or contractor deposits apply.
Request the written refund timetable, inspection conditions, permitted deductions, and dispute procedure before paying. Confirm who holds the funds and who receives the refund.
Do not assume it does. Florida condominium law distinguishes association-insured property from specified unit-owner property and finishes, so have an insurance adviser review the boundary.
Request the contractor agreement, scope of work, and relevant insurance information. Preserve photographs and communications to support a review of responsibility and available coverage.